Warrior (HCC): Q3 2026 Earnings
Warrior Met Coal’s Blue Creek mine cut costs to about $93 a ton, offsetting a wider discount for High Vol A coking coal as US supply expands.
Warrior Met Coal’s Blue Creek mine cut costs to about $93 a ton, offsetting a wider discount for High Vol A coking coal as US supply expands.
@FishtownCap Could $UNFI and $CHEF merge or too much overlap already
Why has $LULU never tried to buildout specialized yoga studios or acquire a chain like Corepower? Seems like it would be a great way to get more stable / recurring revenue via memberships and a good opportunity to cross sell products and attract the companies core clientele (fit yoga girls? I don't even know anymore man)
@FishtownCap Are there any decent food brand stocks any more? $MDLZ also seems troubled
Better re-framing of question. Why would someone be short $DRVN and long $VVV? Take 5 better franchisee economics...Trades at ~ 20 percent maintenance yield vs mid singles...Motivated Sponsor... It's not zero sum but....
@SurfShopCapital Thoughts on $PURR here?
Buying PayPal $PYPL when Wall Street idiots sell this off and waiting for another takeover rumor to dump it back to them is like taking candy from a baby. https://t.co/q4OLppPbgm https://t.co/vVLuLhy0w1
Aurelion Research increased healthcare exposure and sees opportunities in banking and defense, alongside research on Alcoa, Nike, ONON and…
L3Harris booked $19.3 billion of Q3 orders, lifting backlog to $53.2 billion, raised FY26 guidance and cut its 2028 free-cash-flow target…
Oracle’s CDS spreads exceed 320 basis points as debt approaches $135 billion and fiscal 2027 capex targets $95 billion, amid heavy reliance…
 David Desjardins 1 click
Site Centers' $3 per-share return-of-capital distribution and December delisting leave a discounted liquidation stub, with two properties…
Coupang’s product-commerce growth rose 9% as data-leak effects fade, while management expects margins to return to pre-incident levels by…

David Orr describes running Militia Capital’s roughly 500-stock long-short portfolio, using expected value, correlation and factor…

Coupang expects Product Commerce margins to return to pre-data incident levels by mid-2027 as customer spending recovers and Taiwan…
Novo Nordisk beat Q3 consensus as Wegovy pill sales reached DKK 5.4bn, raised 2026 guidance again and reported DKK 79.2bn revenue.
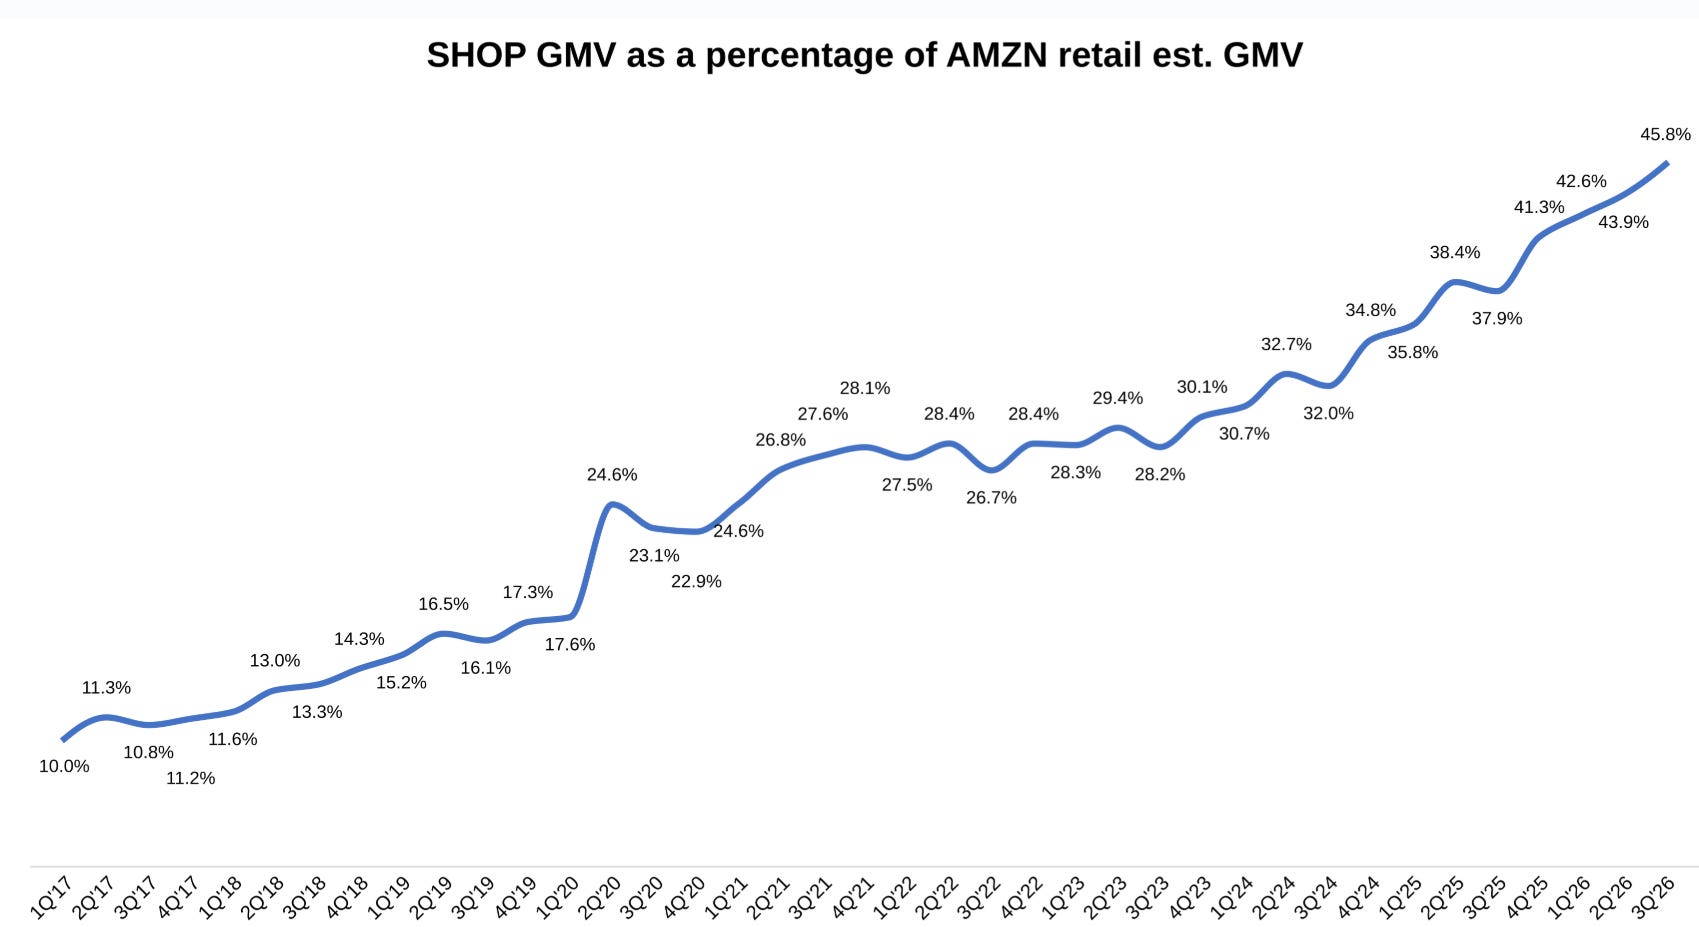
Shopify's 3Q 2026 GMV grew 30% FX-neutral, reaching 46% of Amazon retail GMV after merchants captured nearly half of incremental U.S.
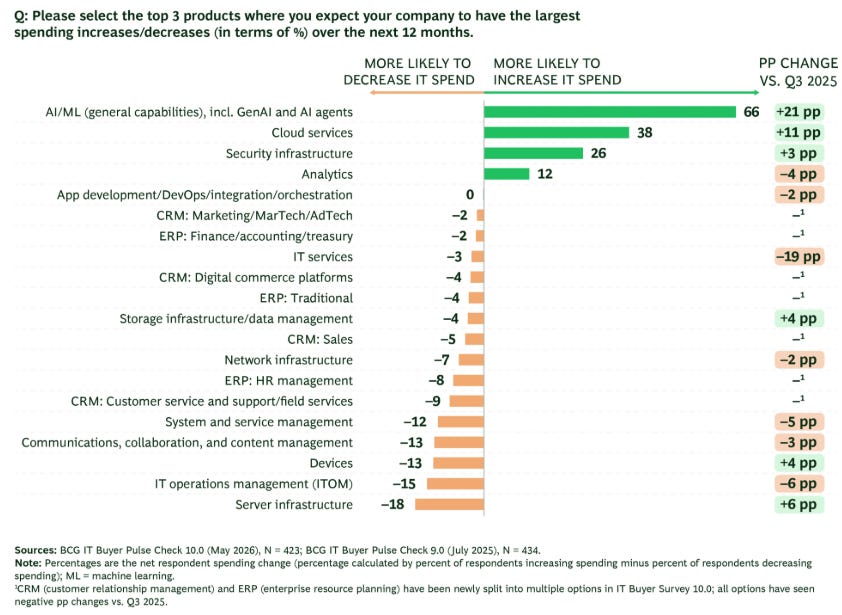
Gartner’s growth has stalled after federal contract losses and cautious commercial spending, raising questions about its competitive…
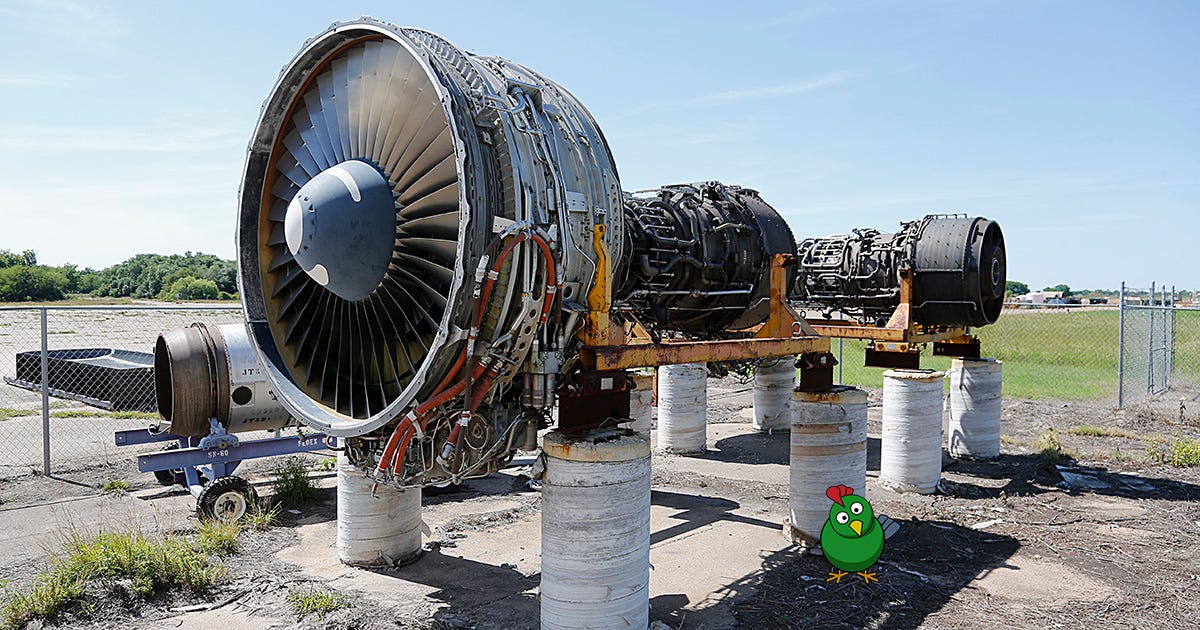
Used aircraft engines can be repurposed as gas turbines, easing data center power constraints while tightening aviation supply.
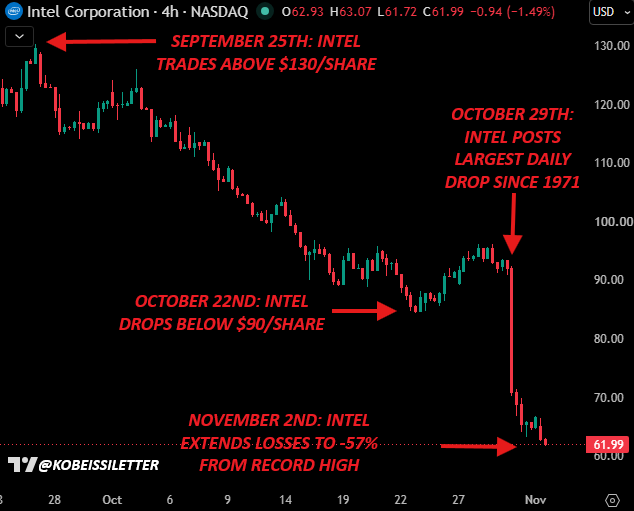
Intel’s 30% stock collapse followed guidance for a more than 20% sequential Q4 client revenue decline, server CPU packaging constraints and…
Chipotle plans 350 to 400 annual openings and low single-digit same-store sales growth, supported by menu innovation, international…
 Jake Blumenthal
 AMRZ · long
Amrize (AMRZ) produces aggregates, cement and roofing materials across the US and Canada.
Builders FirstSource's buybacks halved its share count since 2021, while 4.1x leverage, fixed-rate debt and post-2030 maturities support it…
 Tim Travis
Twilio's Q3 revenue rose 20% to $1.56 billion, but Q4 organic growth guidance fell to 11% to 12% and RPO declined 28%.
Merck reported Q3 revenue of $18.1 billion, up 5%, and raised 2026 guidance as Keytruda sales reached $8.6 billion ahead of its 2028 patent…
Incyte reported Q3 revenue of $1.56 billion, up 14%, as Opzelura sales rose 36%; a $1.23 billion Vega acquisition charge drove an operating…
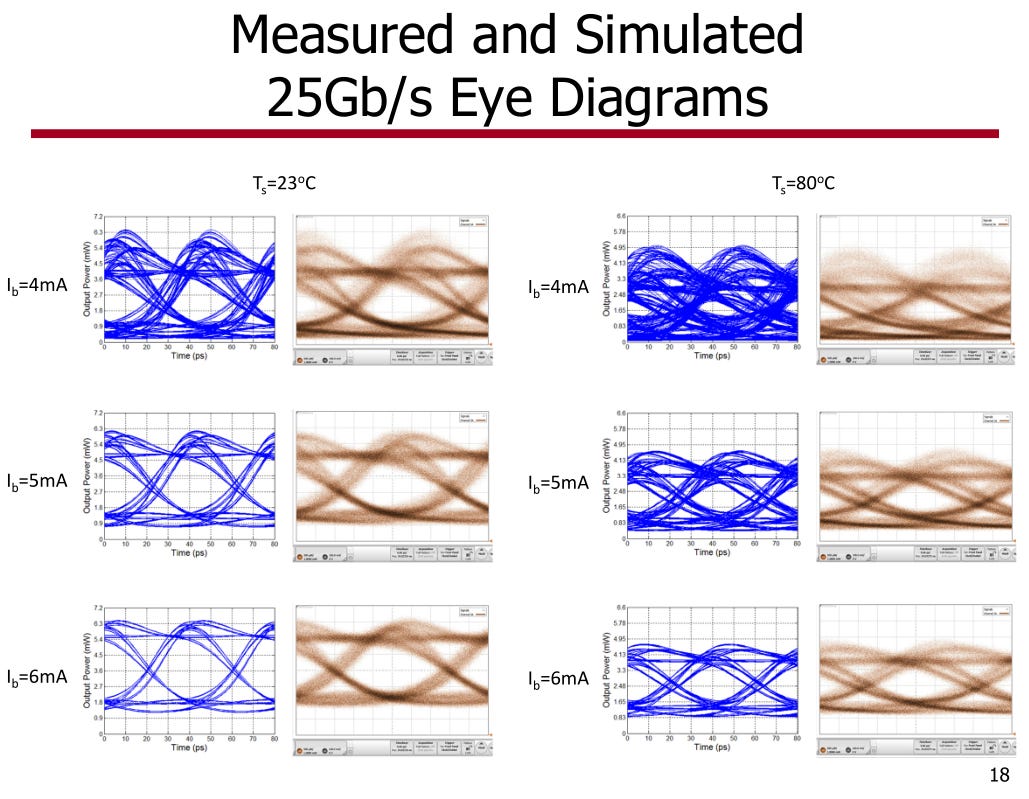
Marvell and Lumentum’s merger targets uVCSEL scale-in optics, combining Marvell’s DSP and analog IP with Lumentum’s laser manufacturing for…
Stevanato fell 30% after forecasting low-single-digit 2027 growth as lower Nexa syringe volumes from a GLP-1 customer offset solid Q3…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.