New Ask Claude or ChatGPT about any stock, using Bullpen. Bullpen in Claude or ChatGPT. 7 days free

Sector

Deep Value

Everything our editor has picked under this sector, best first.

PATK · long

Patrick Industries

Patrick Industries (PATK) is pitched long on its current valuation.

Calvin Blissett on X

Passed on: - $TK: screens at net cash ≈ market cap, but that cash is TNK's. Parent cash plus its TNK stake is ~$1.01B vs a ~$1.23B market cap. Buy TNK directly. - $DFIN: ran to $68, and the SEC's semiannual-reporting proposal hits filing volume. - $RICK: NY AG indictment, CEO and CFO out. - $BAER: ~$15M of equity under ~$650M of debt and preferred. - $CMRE / $DAC: big backlogs, but contracted net earnings don't cover EV yet. - $MATW, $ACTG, $ARKR, $CVEO: FCF or leverage. - $GRND: not cheap.
Calvin Blissett on X

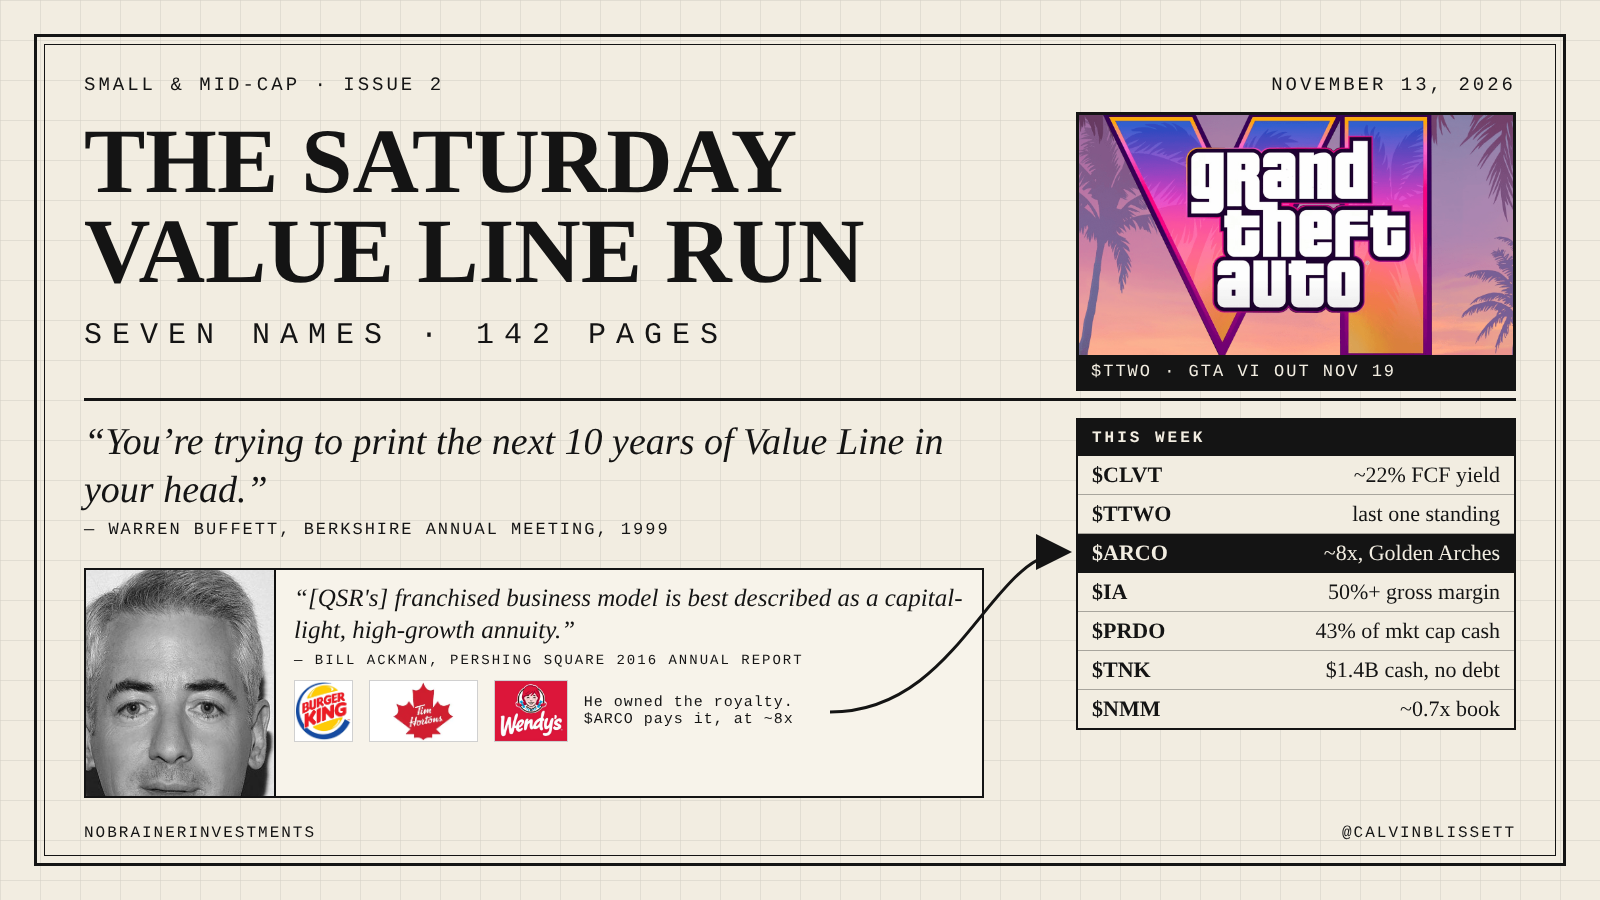
$TNK ~$89.43 Teekay Tankers runs 33 mid-size crude and product tankers, mostly spot. ~$3.10B mkt cap, $1.42B cash, no debt, ~$1.7B EV. First-half EPS was $10.87, already above all of 2025 ($10.10), and Q3 added $5.04. Q4 so far: Suezmax $272K/day and Aframax $208K/day, 30x+ its breakeven. Clarksons has year-end net cash at ~$53/sh. EV is only ~0.4x the value of the ships, so you're getting the fleet at ~40 cents on the dollar plus the cash. The catalyst: the board will consider a special dividend with Q4 results in February instead of May. The $0.25 base hasn't moved since 2023, so the pressure on the payout is all one way. It's also selling old ships at high prices (4 for $211M) and ordering newbuilds for 2030. Why rates could stay up: OECD inventories are at a 20-year low, the U.S. SPR is ~half its pre-2020 level, and the orderbook mostly just replaces old ships. Risks: rates mean-revert and Teekay Corp controls it. BofA raised 2026 EPS by $12 and still rates it Underperform.

Calvin Blissett on X

$ARCO ~$7.21 "We are not technically in the food business. We are in the real estate business." — Harry Sonneborn, McDonald's first CFO Arcos Dorados is the world's largest independent McDonald's franchisee, with exclusive rights in 20 Latin American and Caribbean markets and 2,582 restaurants. ~$1.5B mkt cap, ~4% dividend yield, consensus EPS $0.80 for 2026 and $0.86 for 2027, so ~8-9x. LTM adj. FCF $156M (~10% of the market cap), net debt 1.3x EBITDA. McDonald's itself trades at 20x+ earnings. Its biggest franchisee, running the same system across a continent, trades at less than half that. Munger once described the ideal small-town portfolio as the best office building, the best apartments, the dominant car dealership and the top McDonald's. Headline earnings look worse than they are. Q3 EPS fell to $0.15 from $0.71 because last year included an $85.6M Brazilian tax credit. Excluding it, EBITDA was up 9%. Digital is where it's winning: 66% of sales, loyalty members +60% to ~38M, and 29% of sales now tied to an identified customer. October Investor Day targets: 550-600 openings in 2027-30, high-single to low-double-digit EBITDA growth, and a $25M buyback started. Bear: margins are off the peak (9.5% vs 12.8%), Brazil comps were only +3.5%, and the +46% in the south is mostly Argentine inflation. $1.3-1.5B of capex eats a lot of the FCF.

Calvin Blissett on X

$CLVT ~$2.33 Clarivate owns the databases researchers, universities and patent lawyers pay for every year: Web of Science, Journal Impact Factor, patent data, ProQuest. Down ~93% in five years, and it bottomed at ~$1.65 this fall. ~$1.49B mkt cap, ~$3.4B net debt after the ~$600M Life Sciences sale, ~$4.9B EV. FY26 guide: $865-885M adj. EBITDA and $320-340M FCF, ~5.6x EBITDA and a ~22% FCF yield. Consensus EPS is $0.67, so ~3.5x. The math that matters: equity is only ~30% of EV. Every $100M of debt paid down moves ~7% of the market cap to shareholders without the business growing at all. Three years of FCF at this pace retires ~$1B. It's tendering for 2028 notes below par now. Recurring revenue is most of the mix, with 45% EBITDA margins and organic ACV +1.8%. The new co-development deal with IP law firm Sterne Kessler is mgmt's answer to the AI question: put AI on top of its own patent data instead of letting someone else do it. AlphaSense expert calls cut both ways. Bull (11/11): the data quality is the moat, and AI run on Clarivate's content beats AI run on open data. Bear: AI is bolted onto a patchwork of acquired systems, and open data could close the gap in 2-5 years. Risks: AI, transactional revenue -58%, $284M of impairments YTD, ~3.9x levered.

A Capital on X

On a serious note, $CODI is one of the more glaring mispricings I’ve ever seen. People can argue whether NAV is $25 or $40/share, but I’m convinced that if you liquidated the entire company tomorrow, the assets would be worth at least 2x where the stock trades today. So why does this divergence exist? And more importantly, what closes the gap? Asset sales, replacing management, simplifying the structure, eliminating the governance discount? You don’t even need the stock to trade at 100% of NAV. What gets it to 80%? And at $12/share, how much downside are you really underwriting relative to the potential upside? That’s the asymmetry that interests me. I just don’t think there’s enough eyeballs on this given the size…

Buying OMSE: What's Not To Like?

OMSE trades just above net cash despite growth, earnings and no debt, with Aramco concentration, reporting controls and liquidity the chief…

David Orr on X

Yes, I really do think Hikari Tsushin $9435 is really worth at least double. I also really thought $NVDA could become the most valuable company in the world in 2023. And I also really thought Credit Suisse was insolvent before 2023. What, I shouldn't be allowed to voice these opinions? Why? Because some compliance guy wants to invent reasons to keep me on edge and charge me money? Or because some government regulator needs to justify his job? To them I'd say: you're picking the wrong target, this one actually punches back.

Calvin Blissett on X

The Value Investor's SpaceX ($SPCX) : A Korean Preferred at 0.3x Book. Indrect exposure to SpaceX=~68% of price, Management Says It Wants the Gap Closed. 4% dividend, 4x conservative earnings. Brand advantage in a commodity indsutry. Fundamental Business does not earn from Space X at all 𝘈𝘭𝘴𝘰 𝘒𝘰𝘳𝘦𝘢𝘯 𝘱𝘳𝘦𝘧𝘦𝘳𝘳𝘦𝘥’𝘴 𝘐 𝘱𝘢𝘴𝘴𝘦𝘥 𝘰𝘯 𝘢𝘯𝘥 𝘸𝘩𝘺, 𝘧𝘰𝘳 𝘧𝘳𝘦𝘦! 𝘈𝘴 𝘸𝘦𝘭𝘭 𝘢𝘴 𝘸𝘩𝘢𝘵 𝘐'𝘮 𝘸𝘢𝘵𝘤𝘩𝘪𝘯𝘨 𝘳𝘦𝘨𝘢𝘳𝘥𝘪𝘯𝘨 𝘵𝘩𝘰𝘴𝘦 2.

DOMO Capital Management, LLC on X

Yeah, if you're focused on some sort of biofuel or energy play - $GPRE is almost certainly the best play from this point on. $ANDE just paid 4.25x ethanol assets that are very similar to what GPRE has. GPRE likely $30 if not $40+ by end of 2027 especially with higher likelihood of year-round E15 getting passed and with CA E15 beginning 1/1/2027. Plus GPRE spoke on call that they're likely buying back shares from this point on. By end of Q4 GPRE will be in a net cash position, including unmonetized 45Z credits, and is trading at like 3x 2027 EBITDA.

STRL: 80 new electricians a week

Sterling’s $4.1 billion backlog faces Texas permitting risk after a governor proposed a moratorium, while Connexion, Capital Asset Planning…

Calvin Blissett on X

$EMBC: Embecta (EMBC), spun out of Becton Dickinson in 2022, makes the pen needles and syringes people with diabetes use to inject insulin. Its U.S. pen needle business is shrinking from lost share and price cuts, and more patients are moving from daily insulin shots to weekly GLP-1s. To offset that, it is selling its needles inside the boxes of generic GLP-1 drugs, already launched in India, Canada and Brazil and targeted at $100M+ in revenue by 2033. It is also launching cheaper needles and syringes for new markets and buying into other drug-delivery products beyond insulin. Quick Pitch $350m Market Cap/$1.62B Enterprise Value. Less than 3x P/E. Warren Buffett Owners Earnings of $122m ex SBC. Cut dividend switched to $100m Buyback authorization that's being used. CEO/CFO/Director/CLO all bought August 12th

Raging Capital Ventures on X

Even with the nice move today, $SKIN still only trades for ~4.5x EV/EBITDA. To potentially regain inclusion in the Russell 2000 (it was recently deleted), I estimate that $SKIN would have to trade for around 5.5x EV/EBITDA, or roughly $23 per share. That doesn’t seem like a high bar for a stable, capital-light business that should start generating meaningful FCF while also benefiting from two new pending product upgrade cycles.
SILC · long

Silicom LTD

Silicom (SILC) is pitched as inexpensive on its existing hardware business, with upside framed as a cheap call option.

Maj Soueidan on X

Excerpts from our morning email on $BRM.V and Hammond Manufacturing ( $HMMAF) BRM was clearly the best company I met at the @PlanetMicroCap Toronto conference last week. Whenever anyone asked me the question of who I liked the best at the conference, one stock came out of my mouth. It was BRM. Today’s record quarter supports this opinion and explains why we recently added it to our model portfolio platform. Biorem continues to display operating leverage, with revenue up 48% while EPS more than doubled… The Hammond Manufacturing story is just another example of how one of the best Multi Bagger factors to monitor is companies going through capacity expansions. This is especially true for those that are considered to be value traps trading at deep value levels because investors have lost faith in management’s commitment to shareholder-friendly capital allocation initiatives. We saw that happen with $MUEL before it rose 10x, and now we’re seeing it happen with Hammond Manufacturing…
PRIM · long

Primoris Services CORP

Primoris Services, a $5 billion EPC contractor, has fallen about 60% from its peak.

BR · long

Broadridge Financial Solutns

Broadridge Financial Solutions is framed as a high and rising free-cash-flow generator at a depressed valuation, with insider buying…

ONT · long

Onterris INC

Onterris, formerly Montrose Environmental Group, trades at 8.6x next-12-month EBITDA as an environmental consulting and response services…