
This Week in Special Situations: Mattel, Winnebago, PayPal
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
NASDAQ
PYPL
17 stories
$47B Market cap · 2026-10-28
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
PayPal’s 10.3x forward earnings multiple and more than $6 billion in free cash flow frame a turnaround driven by cost cuts, Venmo and BNPL…
 JR Research 12 clicks
PayPal’s debit spending rose over 60% and Venmo TPV grew 14%, with combined Debit and Pay with Venmo users generating more than 9x revenue…
 Quantryon Capital
I feel like traditional "value investing" went into hibernation. Before it was finding a 10x -12x P/E company like $UPWK or $PYPL, Dominoes, Pepsi. Or even a cheap Japanese company below book value. Then just enjoying slow growth but buyback/dividend appreciation from their cashflow. Now you can find 1.8x runrate P/E company like $ESMT that grew revenue 605.24% Y/Y. And the main thing you need to argue about is duration. Or a 16.2x trailing P/E Sumitomo, despite having way too many hyperscaler LTAs in AI from fiber to lasers. AI created much bigger medium-term anomaly, where "value investing" went towards high growth, "deep value" companies.
How PayPal’s CEO Is Planning to Go It Alone and Fix the Payments Giant $PYPL https://t.co/o18iIv2hgc
Buying PayPal $PYPL when Wall Street idiots sell this off and waiting for another takeover rumor to dump it back to them is like taking candy from a baby. https://t.co/q4OLppPbgm https://t.co/vVLuLhy0w1
$PYPL may have received a new takeover approach per Betaville https://t.co/6Xvh1uA9hG
PayPal's failed Stripe and Advent bid leaves a Venmo spin-off or aggressive buybacks as value-unlocking options amid slowing growth and a…
 The Asian Investor 5 clicks
Well looks like I’m going to get another chance to buy PayPal $PYPL as the market losses its entire ass because the buy out fell through. Back of envelope math here is $42.6 billion EV on $6 billion of free cash flow is a 14% free cash flow yield. Not bad! Growth hogs will piss their pants and cry about how there’s little growth.
*ADVENT, STRIPE CONSORTIUM IS SAID TO DROP PURSUIT OF PAYPAL RIP $PYPL
 PYPL · long
PayPal’s valuation implies free cash flow will shrink 9.3% annually over the next decade, framing a long thesis against its recent revenue…
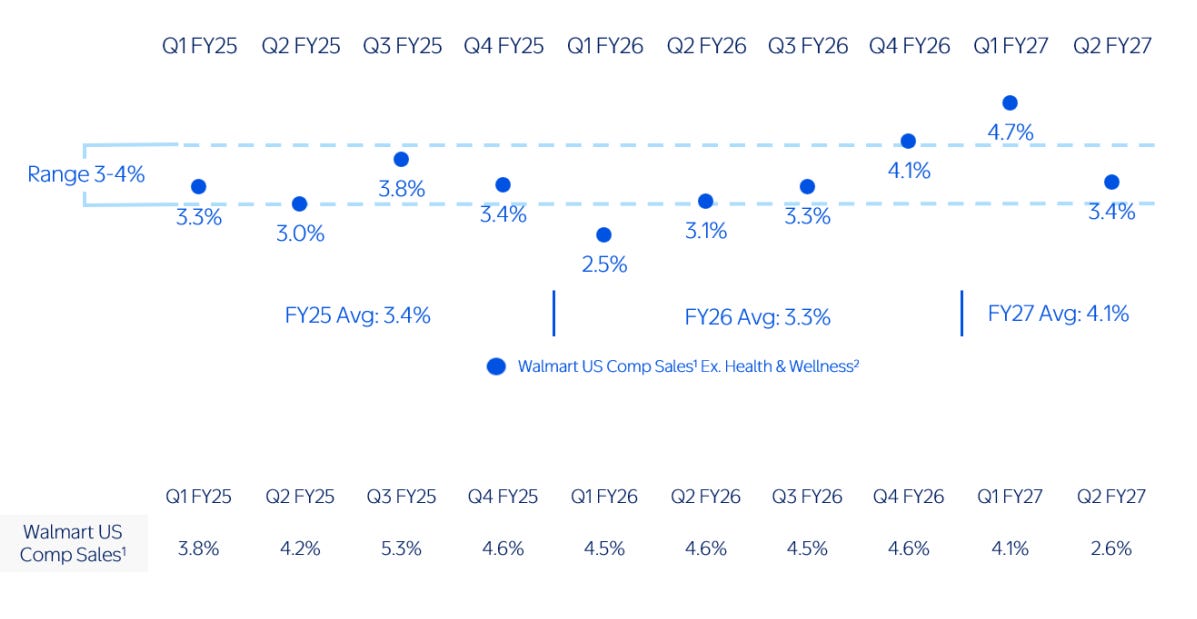
Walmart says Medicare Maximum Fair Price rules will cut FY27 US comps by 125 basis points, while pharmacy margins and prescription volumes…
Stripe and Advent’s reported $53 billion bid for PayPal follows a decade in which Stripe’s payment volume outgrew PayPal’s Braintree.
PayPal faces a $60.50-per-share buyout offer from Stripe and Advent, with a rejection or counteroffer above $80 viewed as more likely.
Someone really going to need to explain how Stripe buying $PYPL is also bullish for $XYZ? Venmo now gets unlimited funding, a direct consumer facing application for the biggest player in payments, and the optionality of their checkout/pos business if they want to scale and invest aggressively their for that (like pushing their stable coin initiative that would be well received by retailers). Would think the correct framework for this deal is it is net negative the entire payment space as a new entrant has new pathways to compete and disrupt ($TOST, $STNE $FOUR etc included)
Stripe’s startup-focused product sprawl contrasts with Adyen’s enterprise restraint; despite 20% more payment volume and faster growth,…
I’m attending the RBC and Jefferies FinTech conferences this week. Meeting with $SSNC, $PYPL, $ENV, $JKHY & others.
Letters that discuss PYPL.
Companies the stories above are also about, besides PYPL.

