

Lee Roach on X
From $23 bucks per share to $2.61 and collapsing after market from crap earnings. When does $GEOS become a buy?
Sector
Everything our editor has picked under this sector, best first.
From $23 bucks per share to $2.61 and collapsing after market from crap earnings. When does $GEOS become a buy?

@kiwicarrotcake double winner. $FLR made a great return on its cash investment, and will win business from $SMR and other SMRs.

Rick Rule argues copper needs $250 billion of capital and says 30-year uranium contracts are reshaping mine financing.
India’s 236 GWh battery target boosts local electrolyte-salt makers, while Mirion’s radiation monitors and Overwatch’s passive drone…
Chord Energy trades at 3x mid-cycle EV/EBITDA with a 15% free-cash-flow yield at $75 WTI, while repurchasing shares and expanding its…
 Ron Ferrie 4 clicks
 ODC · long
Oil-Dri Corporation of America produces cat litter and operates agriculture, recreation and renewable diesel businesses.

Situational Awareness 2.0 is coming. I think Leopold's early ideas were directionally right from $SNDK to $BE. Even his recent ones like Taiyo Yuden, I do see MLCCs becoming a bottleneck in 2027. Unfortunately, due to excessive leverage and crowded longs... Positioning left him vulnerable to liquidation before he got to see longer horizon ideas play out. I think it's fun to see fund managers actually have unique ideas in similar sectors. So hope he can make a comeback. I learned a lot of lessons myself to in terms of being more narrow with long selections, so very excited for 2027.
 BH · short
Biglari Holdings short thesis targets a conglomerate spanning restaurants, oil and gas, insurance and media.
APA’s Q3 free cash flow more than doubled to $699 million, funding $537 million of shareholder returns and debt reduction as it pursues a…
 IWA Research
Considering selling very long-dated ATM/OTM calls in the refiners. $VLO $MPC The worm has turned. May bounce again but I think it highly likely the next 2-3 years will not be as lucrative for the sector as the past year.
Monte Investments rotated Nvidia into Alphabet before earnings and reviews Knife River’s margin squeeze, AMD’s World Labs acquisition, and…
Just now reading the $NXT call from yesterday's analyst day. Management was bullish AF. Might add to my long. "We talked about doing $3.7 billion this fiscal year and $5.2 billion in fiscal 2030... We've raised guidance I covered at our last earnings call, we expect to deliver $4.3 billion this year. And now we're taking up our fiscal 2030 guidance to over $7.5 billion."
Perma-Fix's Q3 gross margin fell to 3.1% from 14.6% as Hanford delays and fixed costs drove cash burn and potential dilution.
 Number Cruncher

About five years from the bubble burst and $XLE still outperforming $XLK
@sidecarcap Both $ECRO and $RNGE using coal as a launching pad to do something bigger. $500m of NOLs and data center potential, respectively

Chevron nears $5 bn deal for Blackstone-backed oil producer in US Gulf $CVX
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.

@CihunSol Quite a few. The insiders of Pampa Energia $PAM have been consistently buying. So have the insiders of Liberty Latin America $LILA, especially their preferred shares. Oddly enough so has a cluster of insiders from GameStop $GME Too many to list.
 DVFI · long
Diversified Gas & Oil’s $500 million 9.75% senior secured notes due 2029 are rated a buy.

Here's my November 8 update on $NTWO (you can read most of it for free):
Peabody Energy trades at 2.7 to 2.9 times consensus EBITDA after Centurion delays cut Q4 guidance, with $434 million cash, $297 million…
 Bang For The Buck 5 clicks
OMSE trades just above net cash despite growth, earnings and no debt, with Aramco concentration, reporting controls and liquidity the chief…
 Daryl Davis
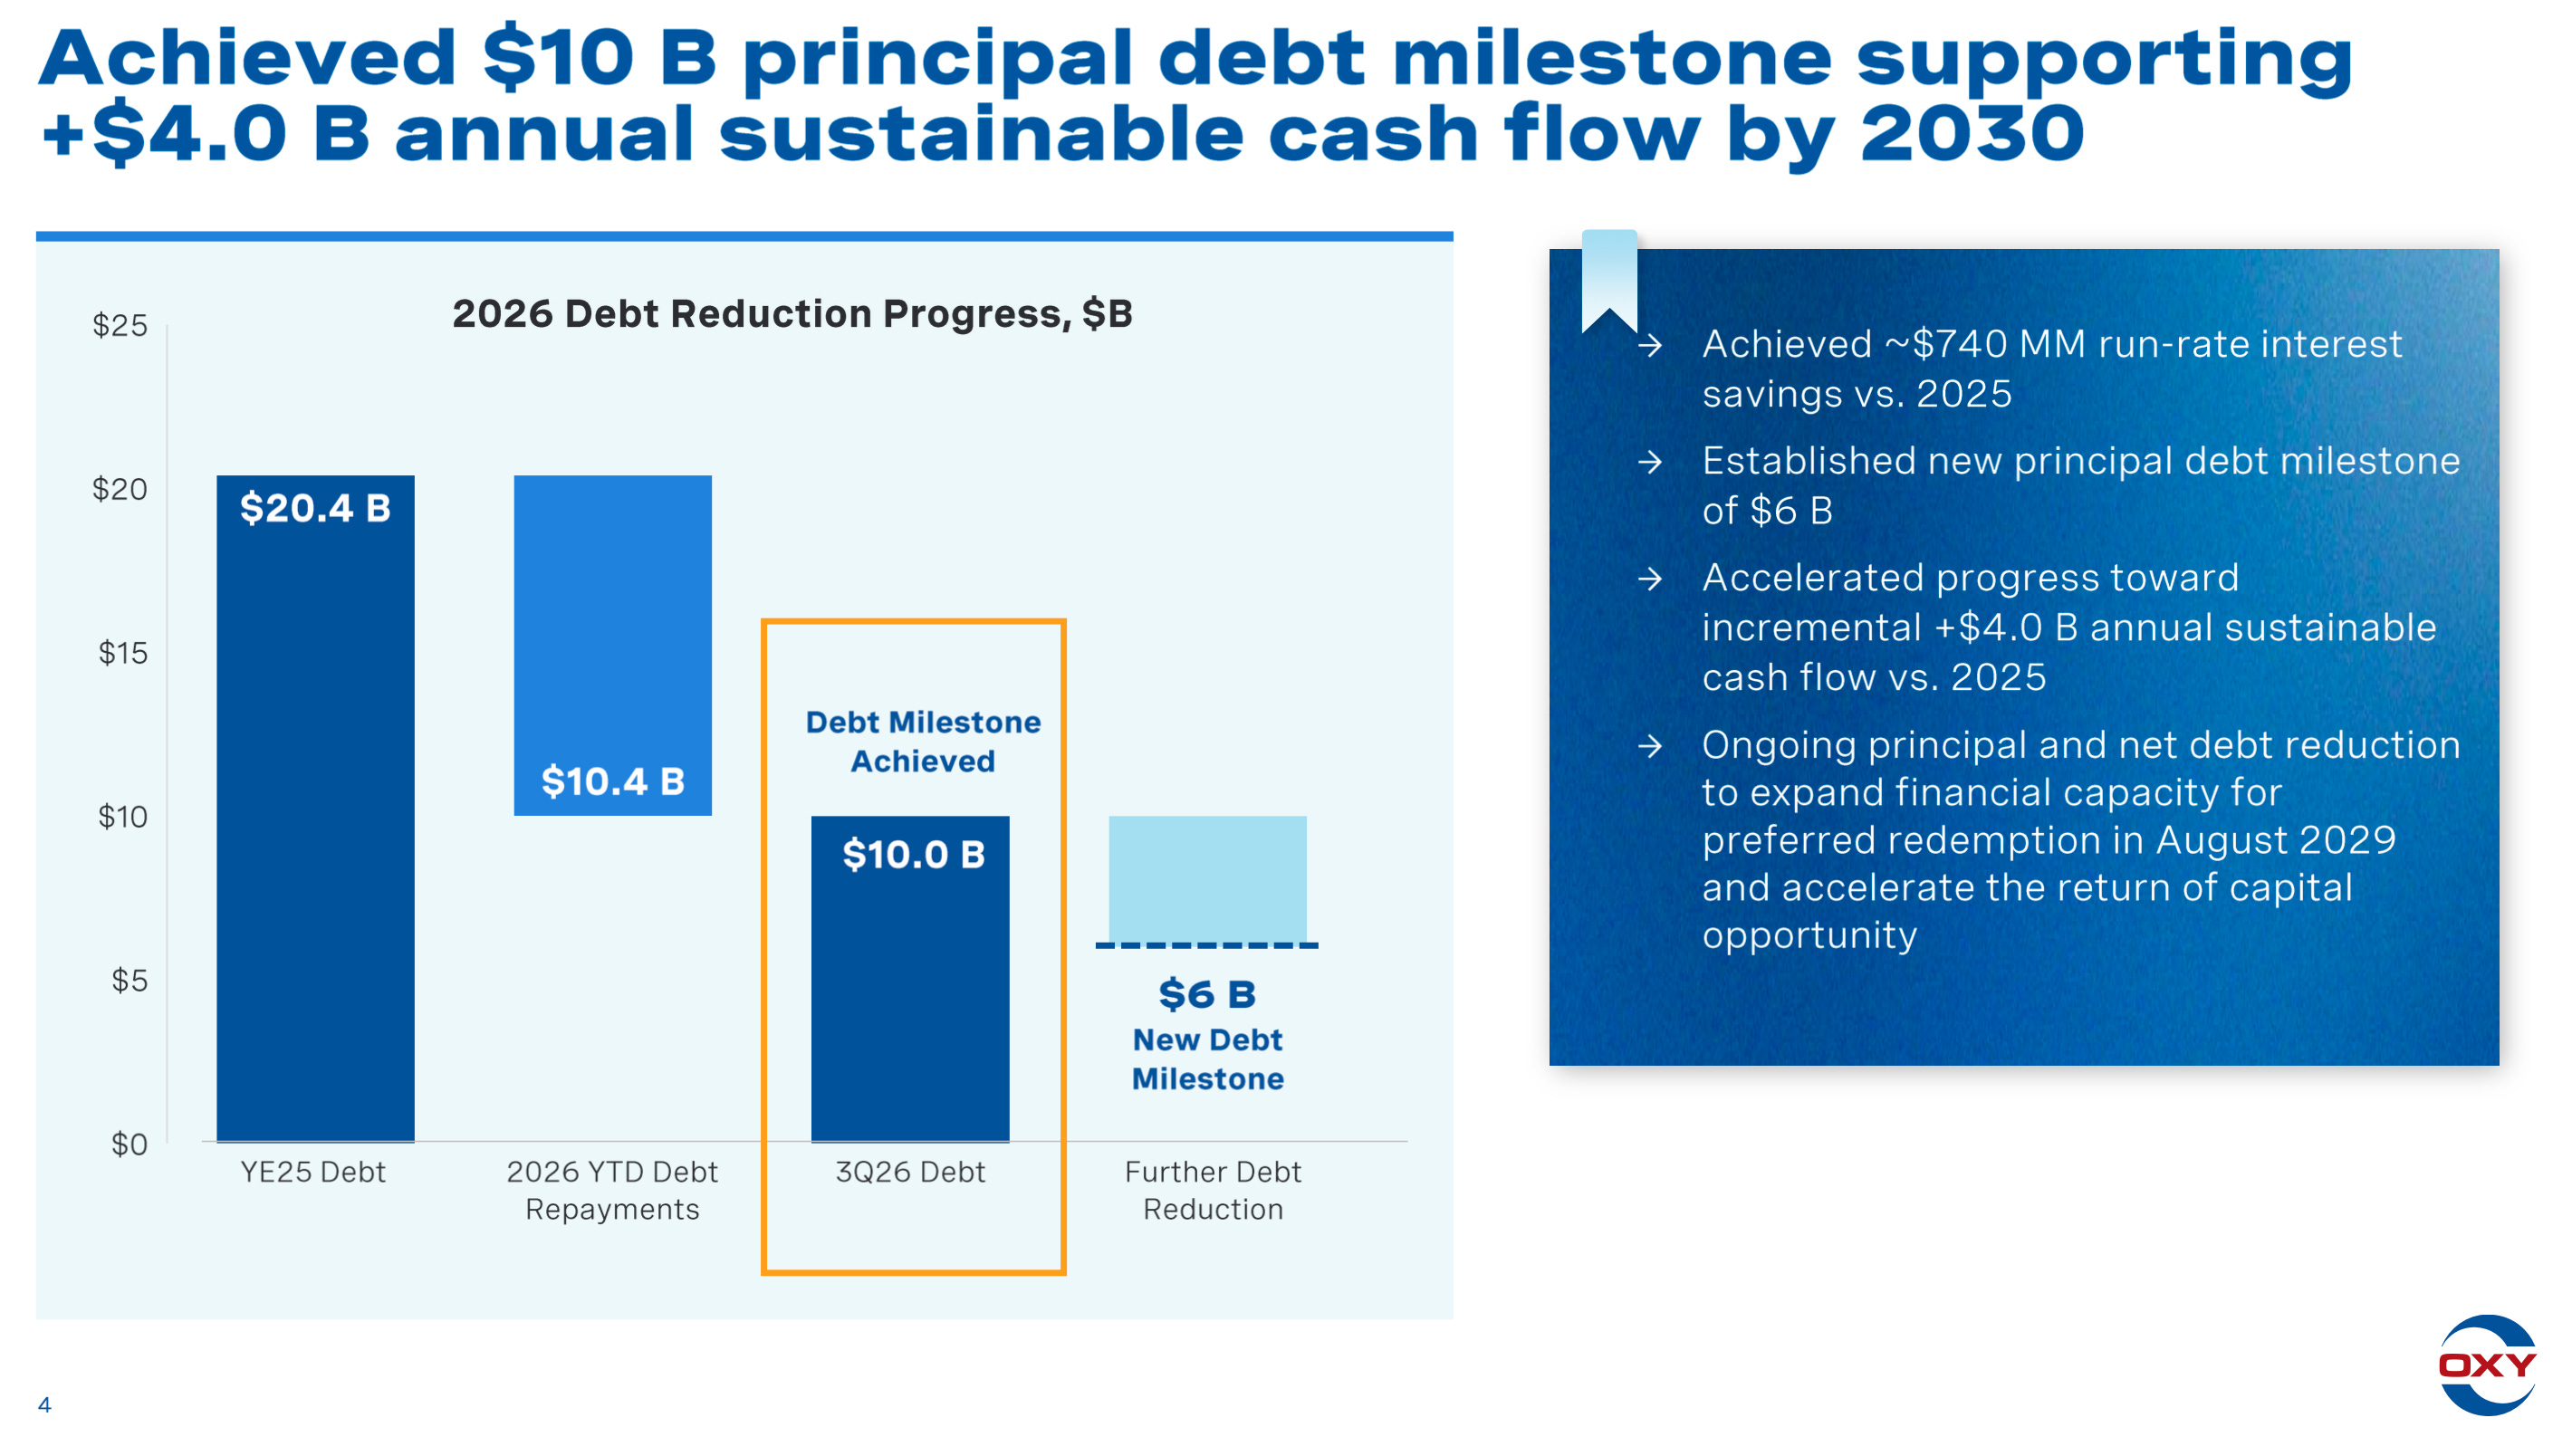
Occidental Petroleum reached its $10 billion debt target early and targets $6.4 billion to $6.5 billion of 2027 free cash flow at $65 WTI,…
When companies report in trillions, its time to revalue that currency. 🇨🇴 $EC
Kimbell Royalty Partners targets an 11% normalized yield through third-party drilling royalties, with distributions sensitive to oil and…
 Atlas Diary 4 clicks
Petrobras posted record 3Q26 production and earnings, but higher investment needs are shrinking dividends as a possible Lula IV government…
 Bernard Zambonin 9 clicks
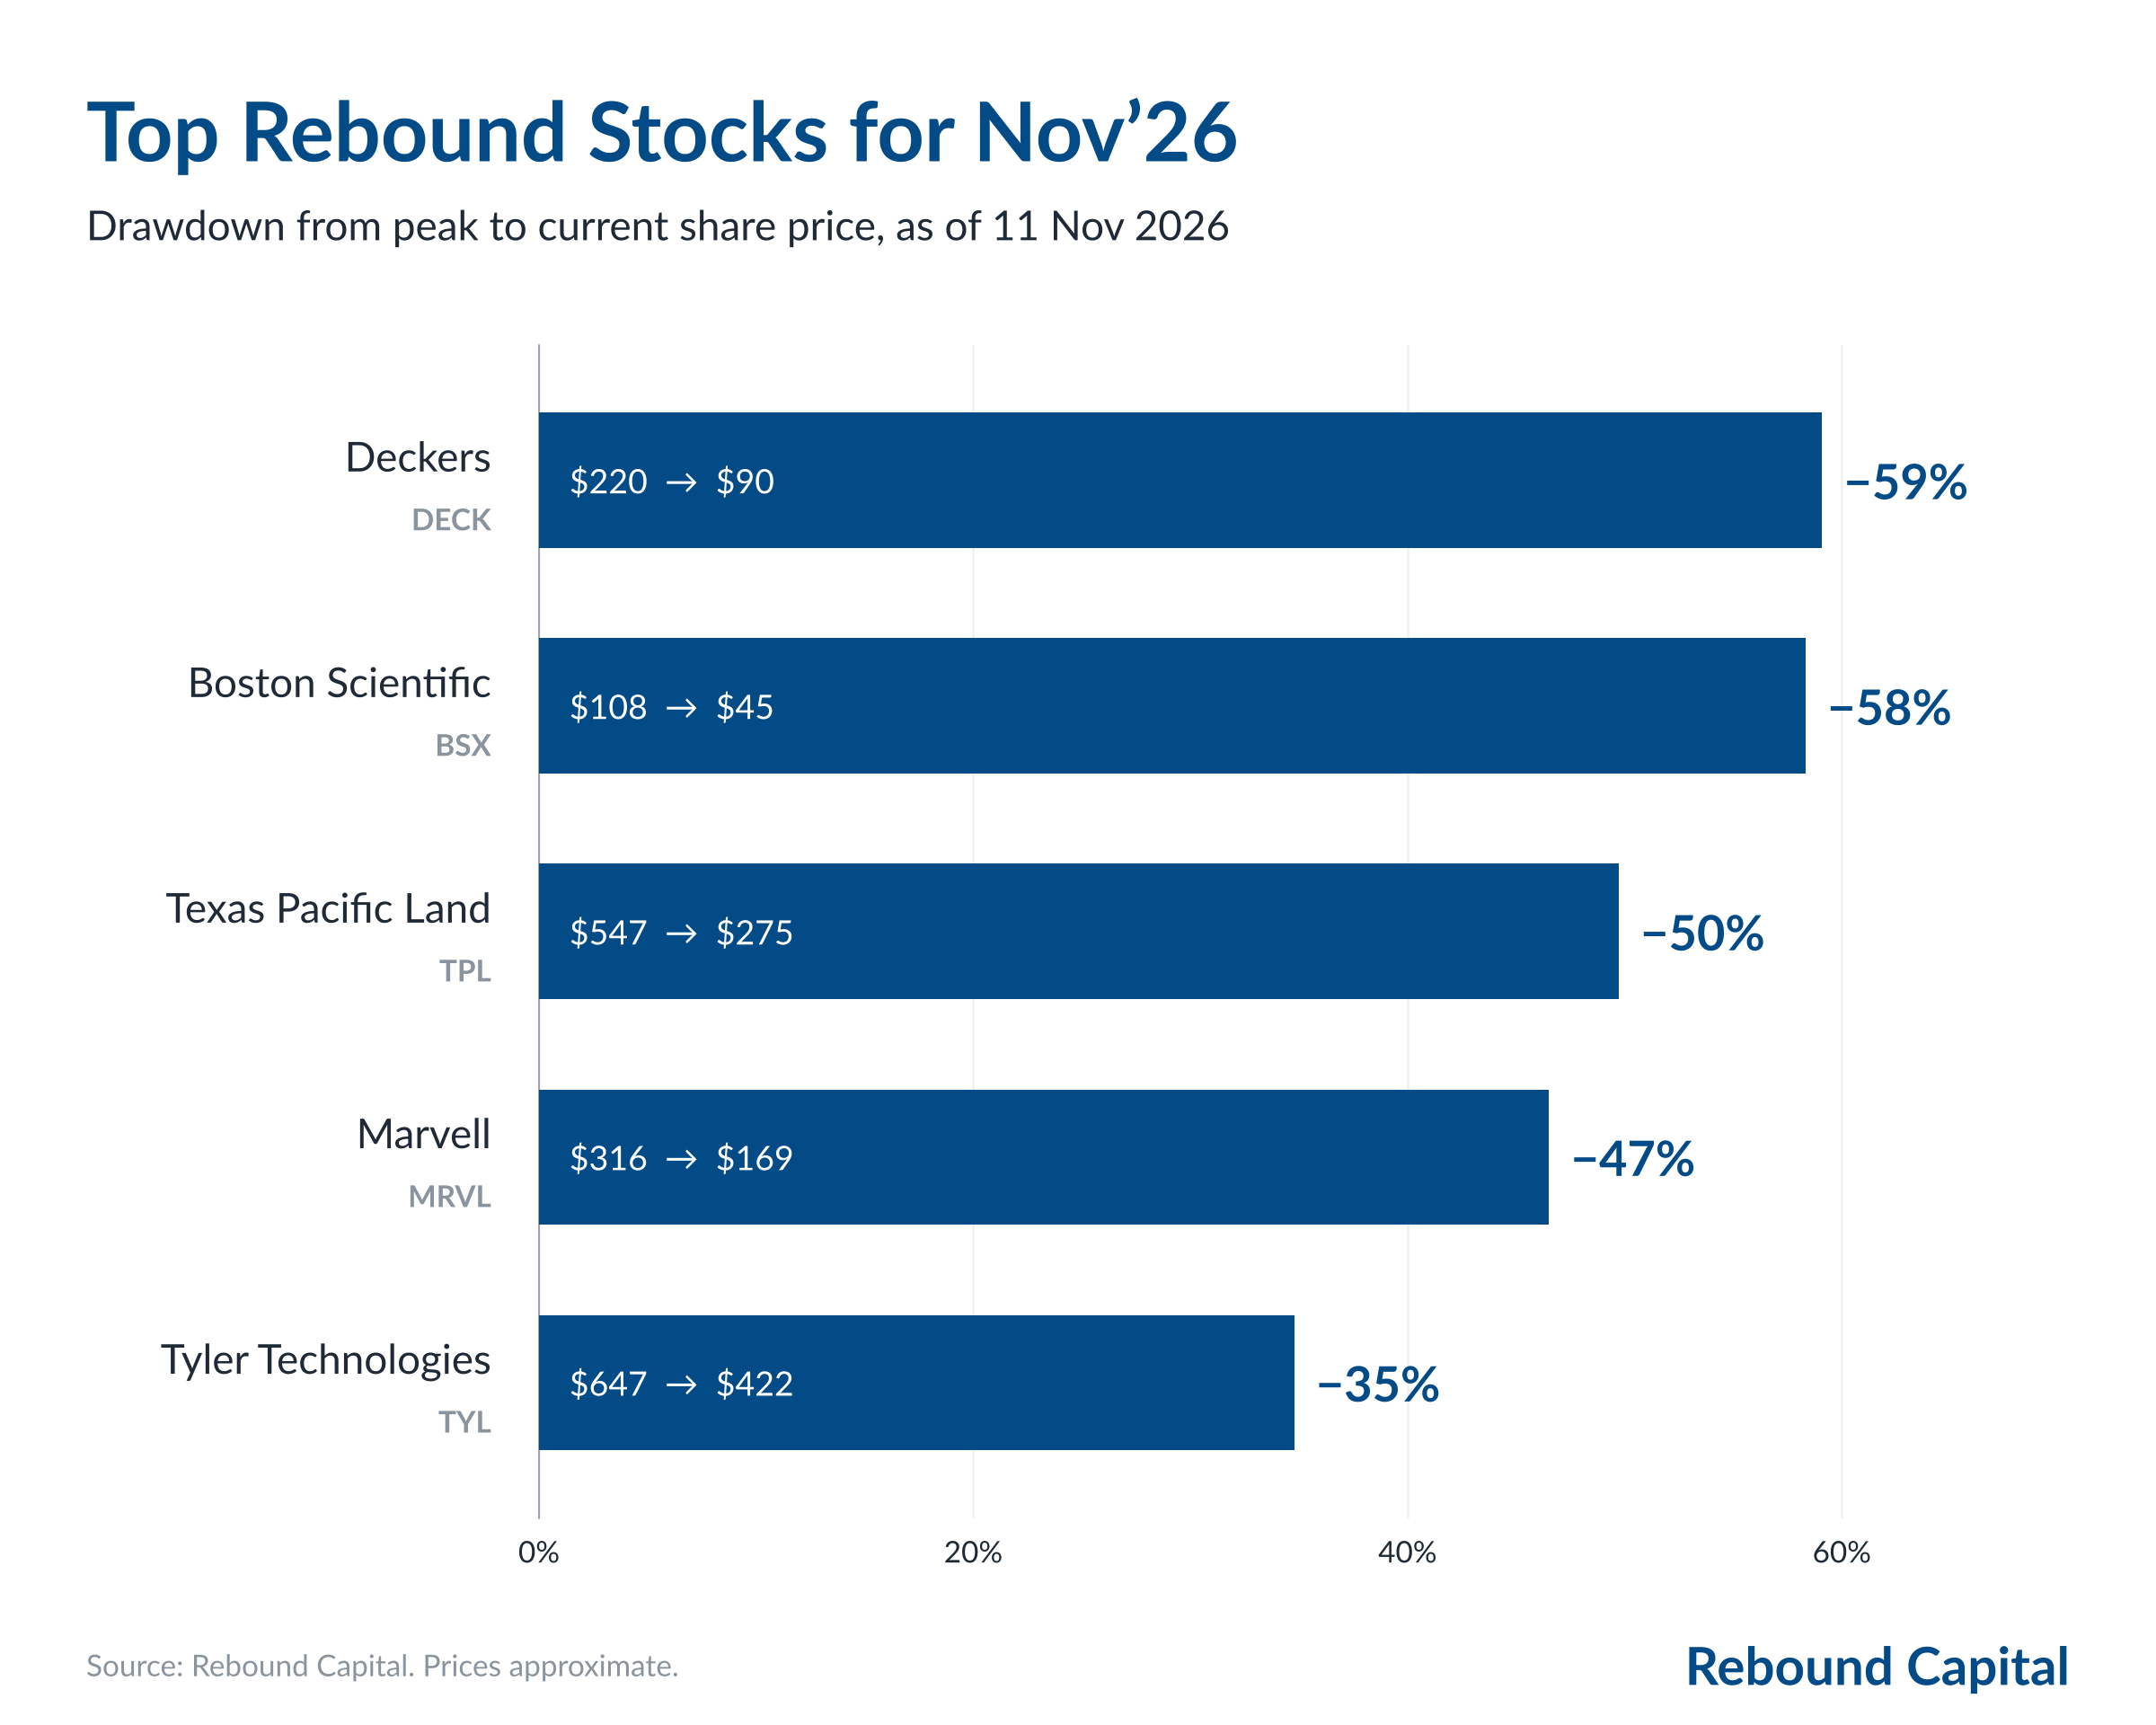
Texas Pacific Land's 50% selloff reflects faded data-center expectations, while its Permian royalty business generated $498 million of 2025…
Par Pacific's Q3 revenue rose 52% to $3.05 billion, while refining margins, integrated logistics and $226 million net cash support earnings…
 Blake Winiecki

$SHLS & $ARRY Merger / Short Report Review
WaterBridge grew Q3 revenue 16.9% year over year as Speedway Phase I lifted produced-water volumes, while pursuing large-scale data center…
Fervo Energy raised $2 billion in its May IPO, then fell nearly 70% below issue price after a Morpheus short report, despite targeting 1 GW…
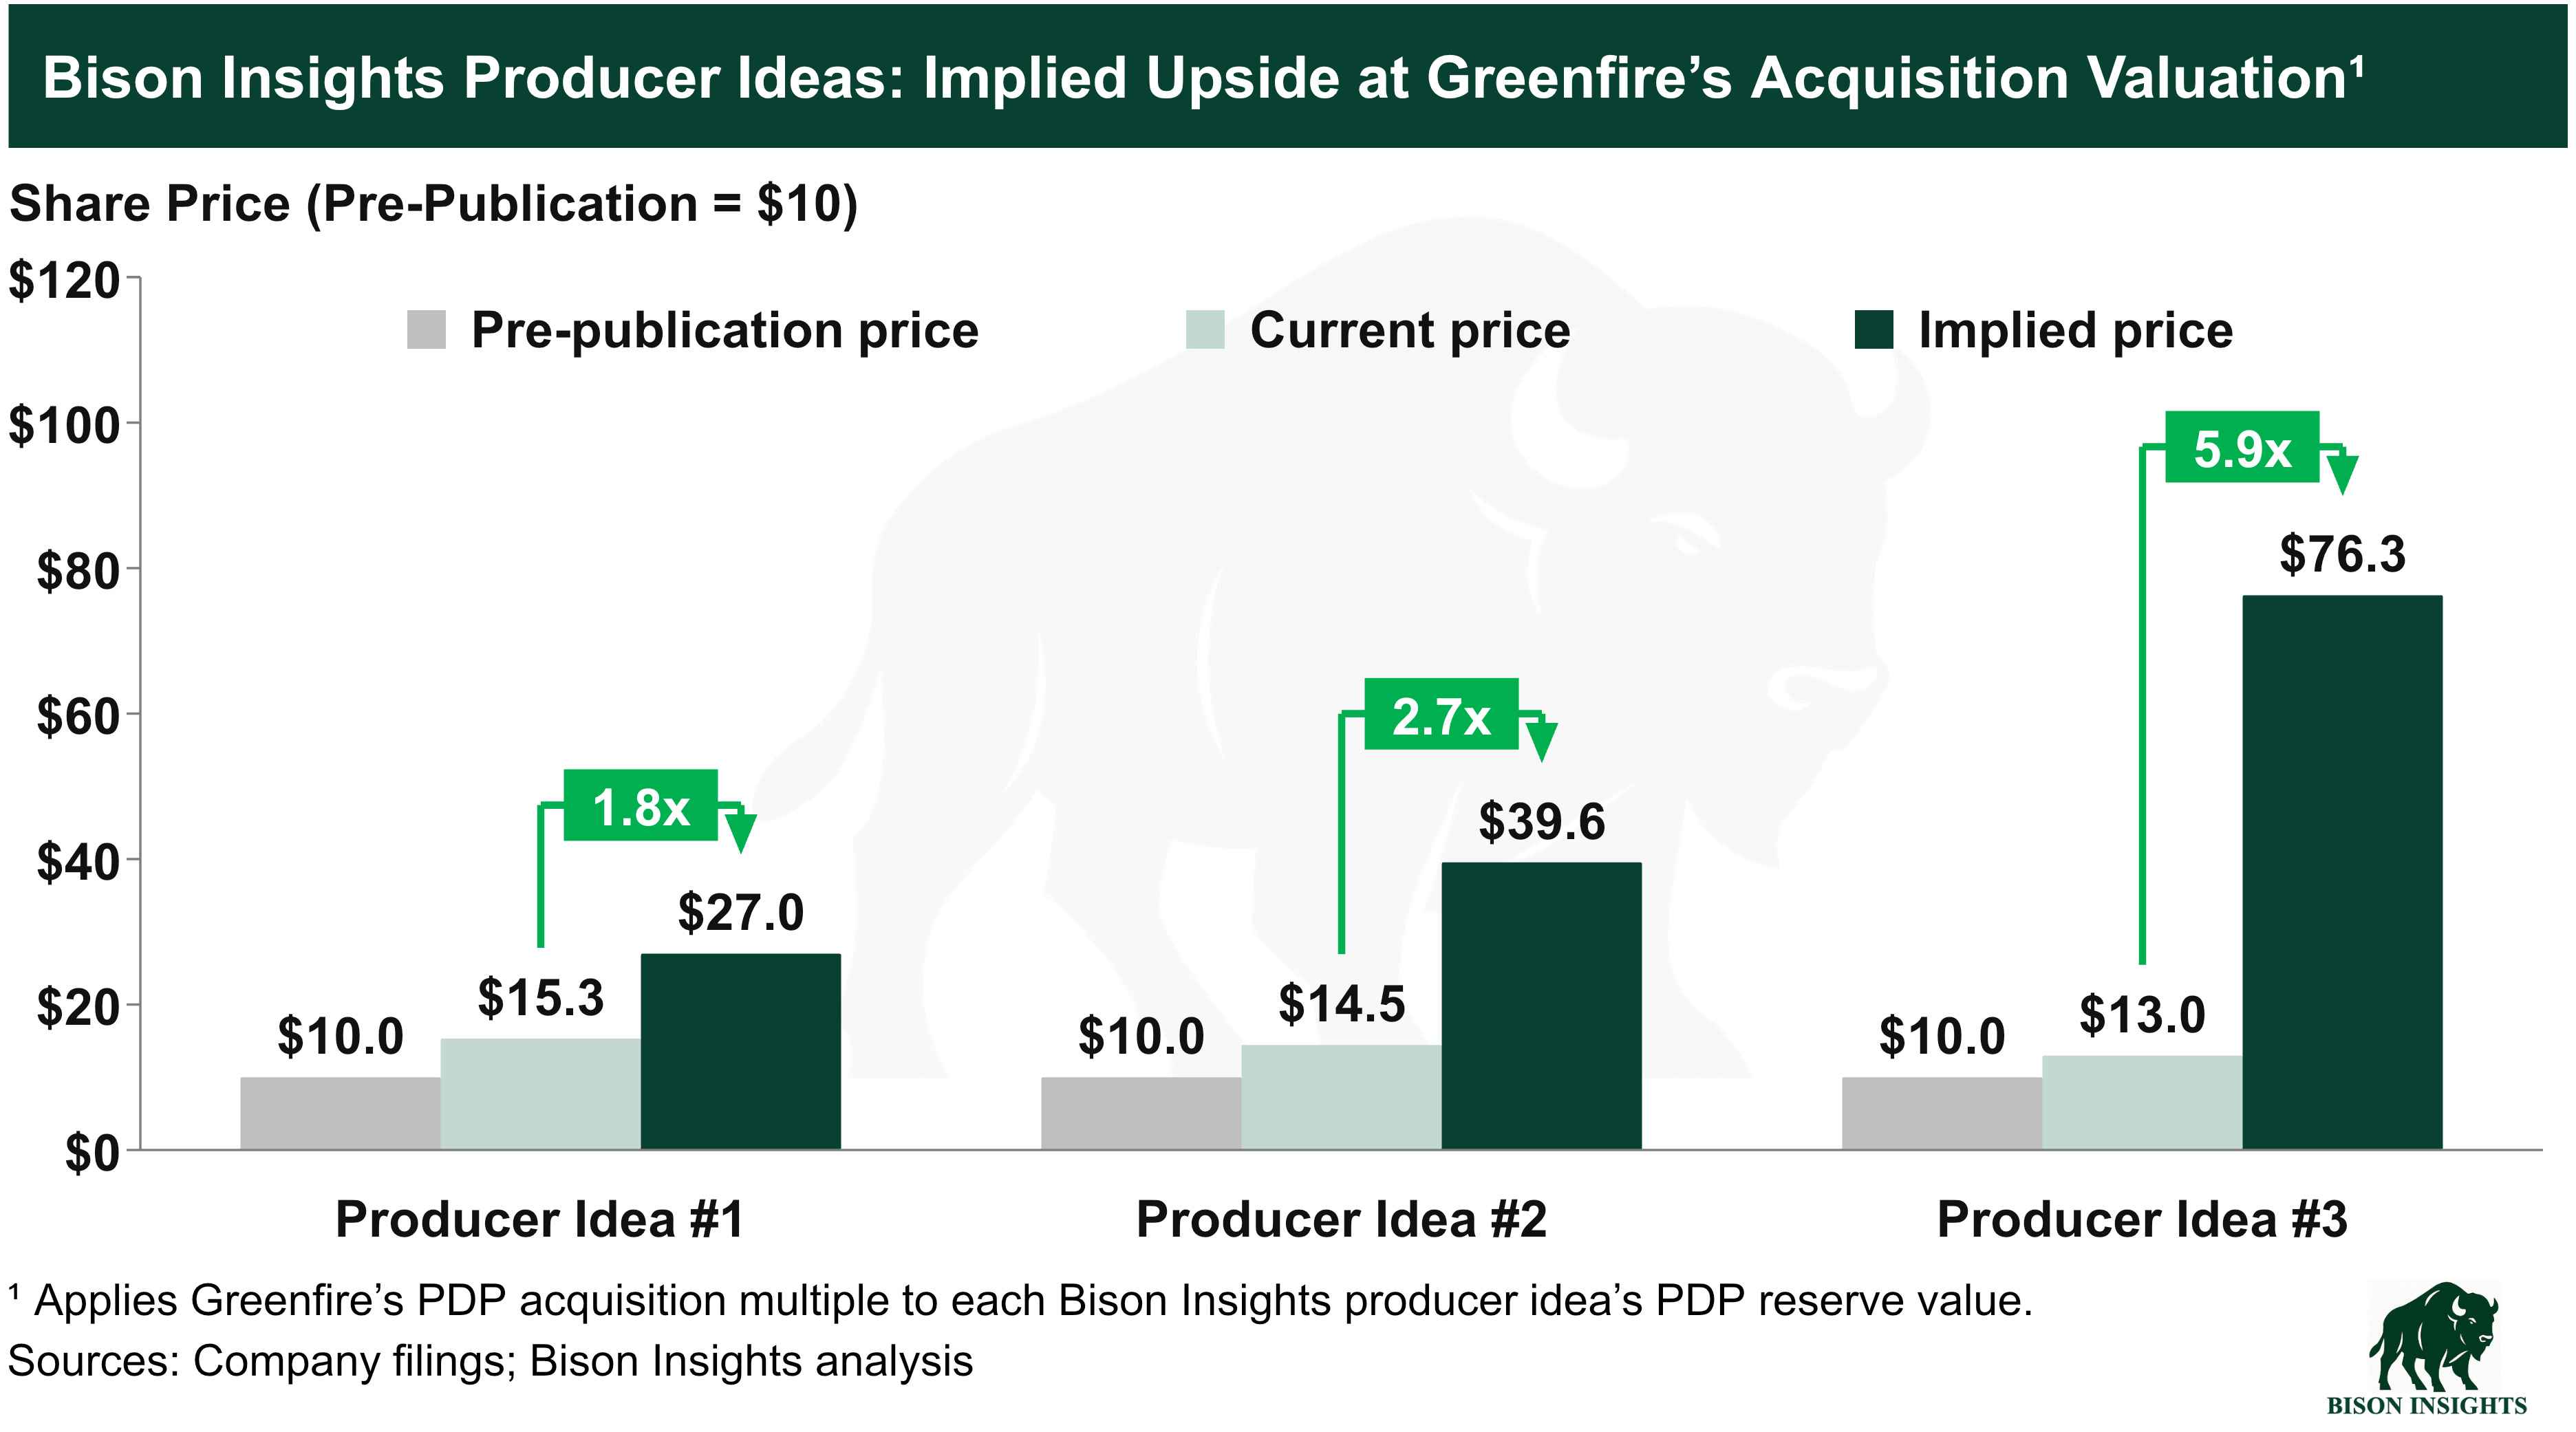
Strathcona Resources will acquire Greenfire Resources for C$2.8 billion including debt, valuing the Canadian heavy-oil producer at up to a…

Occidental Petroleum generated $4.3 billion of Q3 EBITDA and cut principal debt to $10 billion, but each $1 WTI decline reduces annual…
"signed a preliminary deal Monday to explore investments" Exxon Takes First Step Toward Investing in Venezuela $XOM
We're not far from a banker pitching $GEV or $CAT on buying $PTON for behind-the-meter power.

$SOC imploding couldn't have happened to a dumber group of assholes.

Yeah, if you're focused on some sort of biofuel or energy play - $GPRE is almost certainly the best play from this point on. $ANDE just paid 4.25x ethanol assets that are very similar to what GPRE has. GPRE likely $30 if not $40+ by end of 2027 especially with higher likelihood of year-round E15 getting passed and with CA E15 beginning 1/1/2027. Plus GPRE spoke on call that they're likely buying back shares from this point on. By end of Q4 GPRE will be in a net cash position, including unmonetized 45Z credits, and is trading at like 3x 2027 EBITDA.
"Sen. Chuck Grassley, R-Iowa, said this week that Republicans should agree to Democrats’ demands for a two-year cost extension on the Supplemental Nutrition Assistance Program in order to pass a farm bill that also allows the sale of #E15 fuel nationwide and year round, DTN/Progressive Farmer reported." $GPRE $ALTO

$CKX situation is a good reminder that there's shellco optionality in these nanocaps.

@kingdomcapadv I still cannot believe something happened to $CKX This must be AI slop😅
Nextracker's $6 billion order book supports cross-selling battery storage and inverters, now 22% of revenue, though acquisition-led growth…
 Investor Overview 4 clicks

$IPCO buybacks restarted, Waterous taking out $GFR as expected... SAGD assets consolidating quickly
Blue Dolphin Energy trades near 1.3 times earnings as its Texas refinery benefits from diesel shortages, with projected 2026 EBITDA of $111…
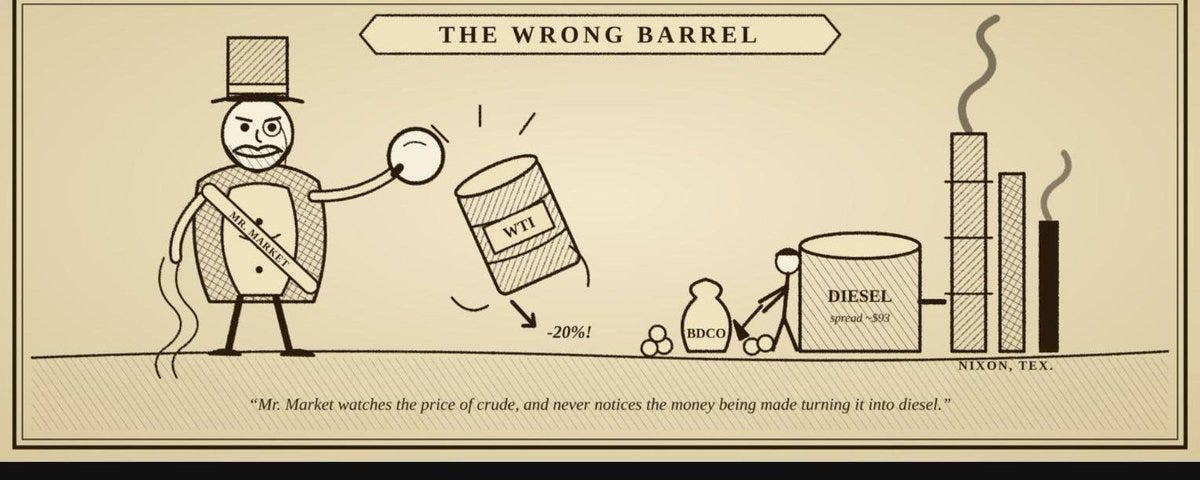
Blue Dolphin’s 15,000-barrel-per-day Texas refinery earned $2.18 per share in first-half 2026 as diesel shortages widened crack spreads,…
Western Midstream targets $3.2 billion EBITDA and $2.3 billion distributable cash flow in 2027 as Pathfinder Pipeline and North Loving II…
 Melissa Tucker

David and I also discussed Japan, oil, AI, prediction markets, Elon Musk and $SPCX, Taiwan and Ukraine, and numerous other topics. We also provide a recap of several investment ideas that we shared at our recent conference. Full interview is here: 2/2
 HNRG · long
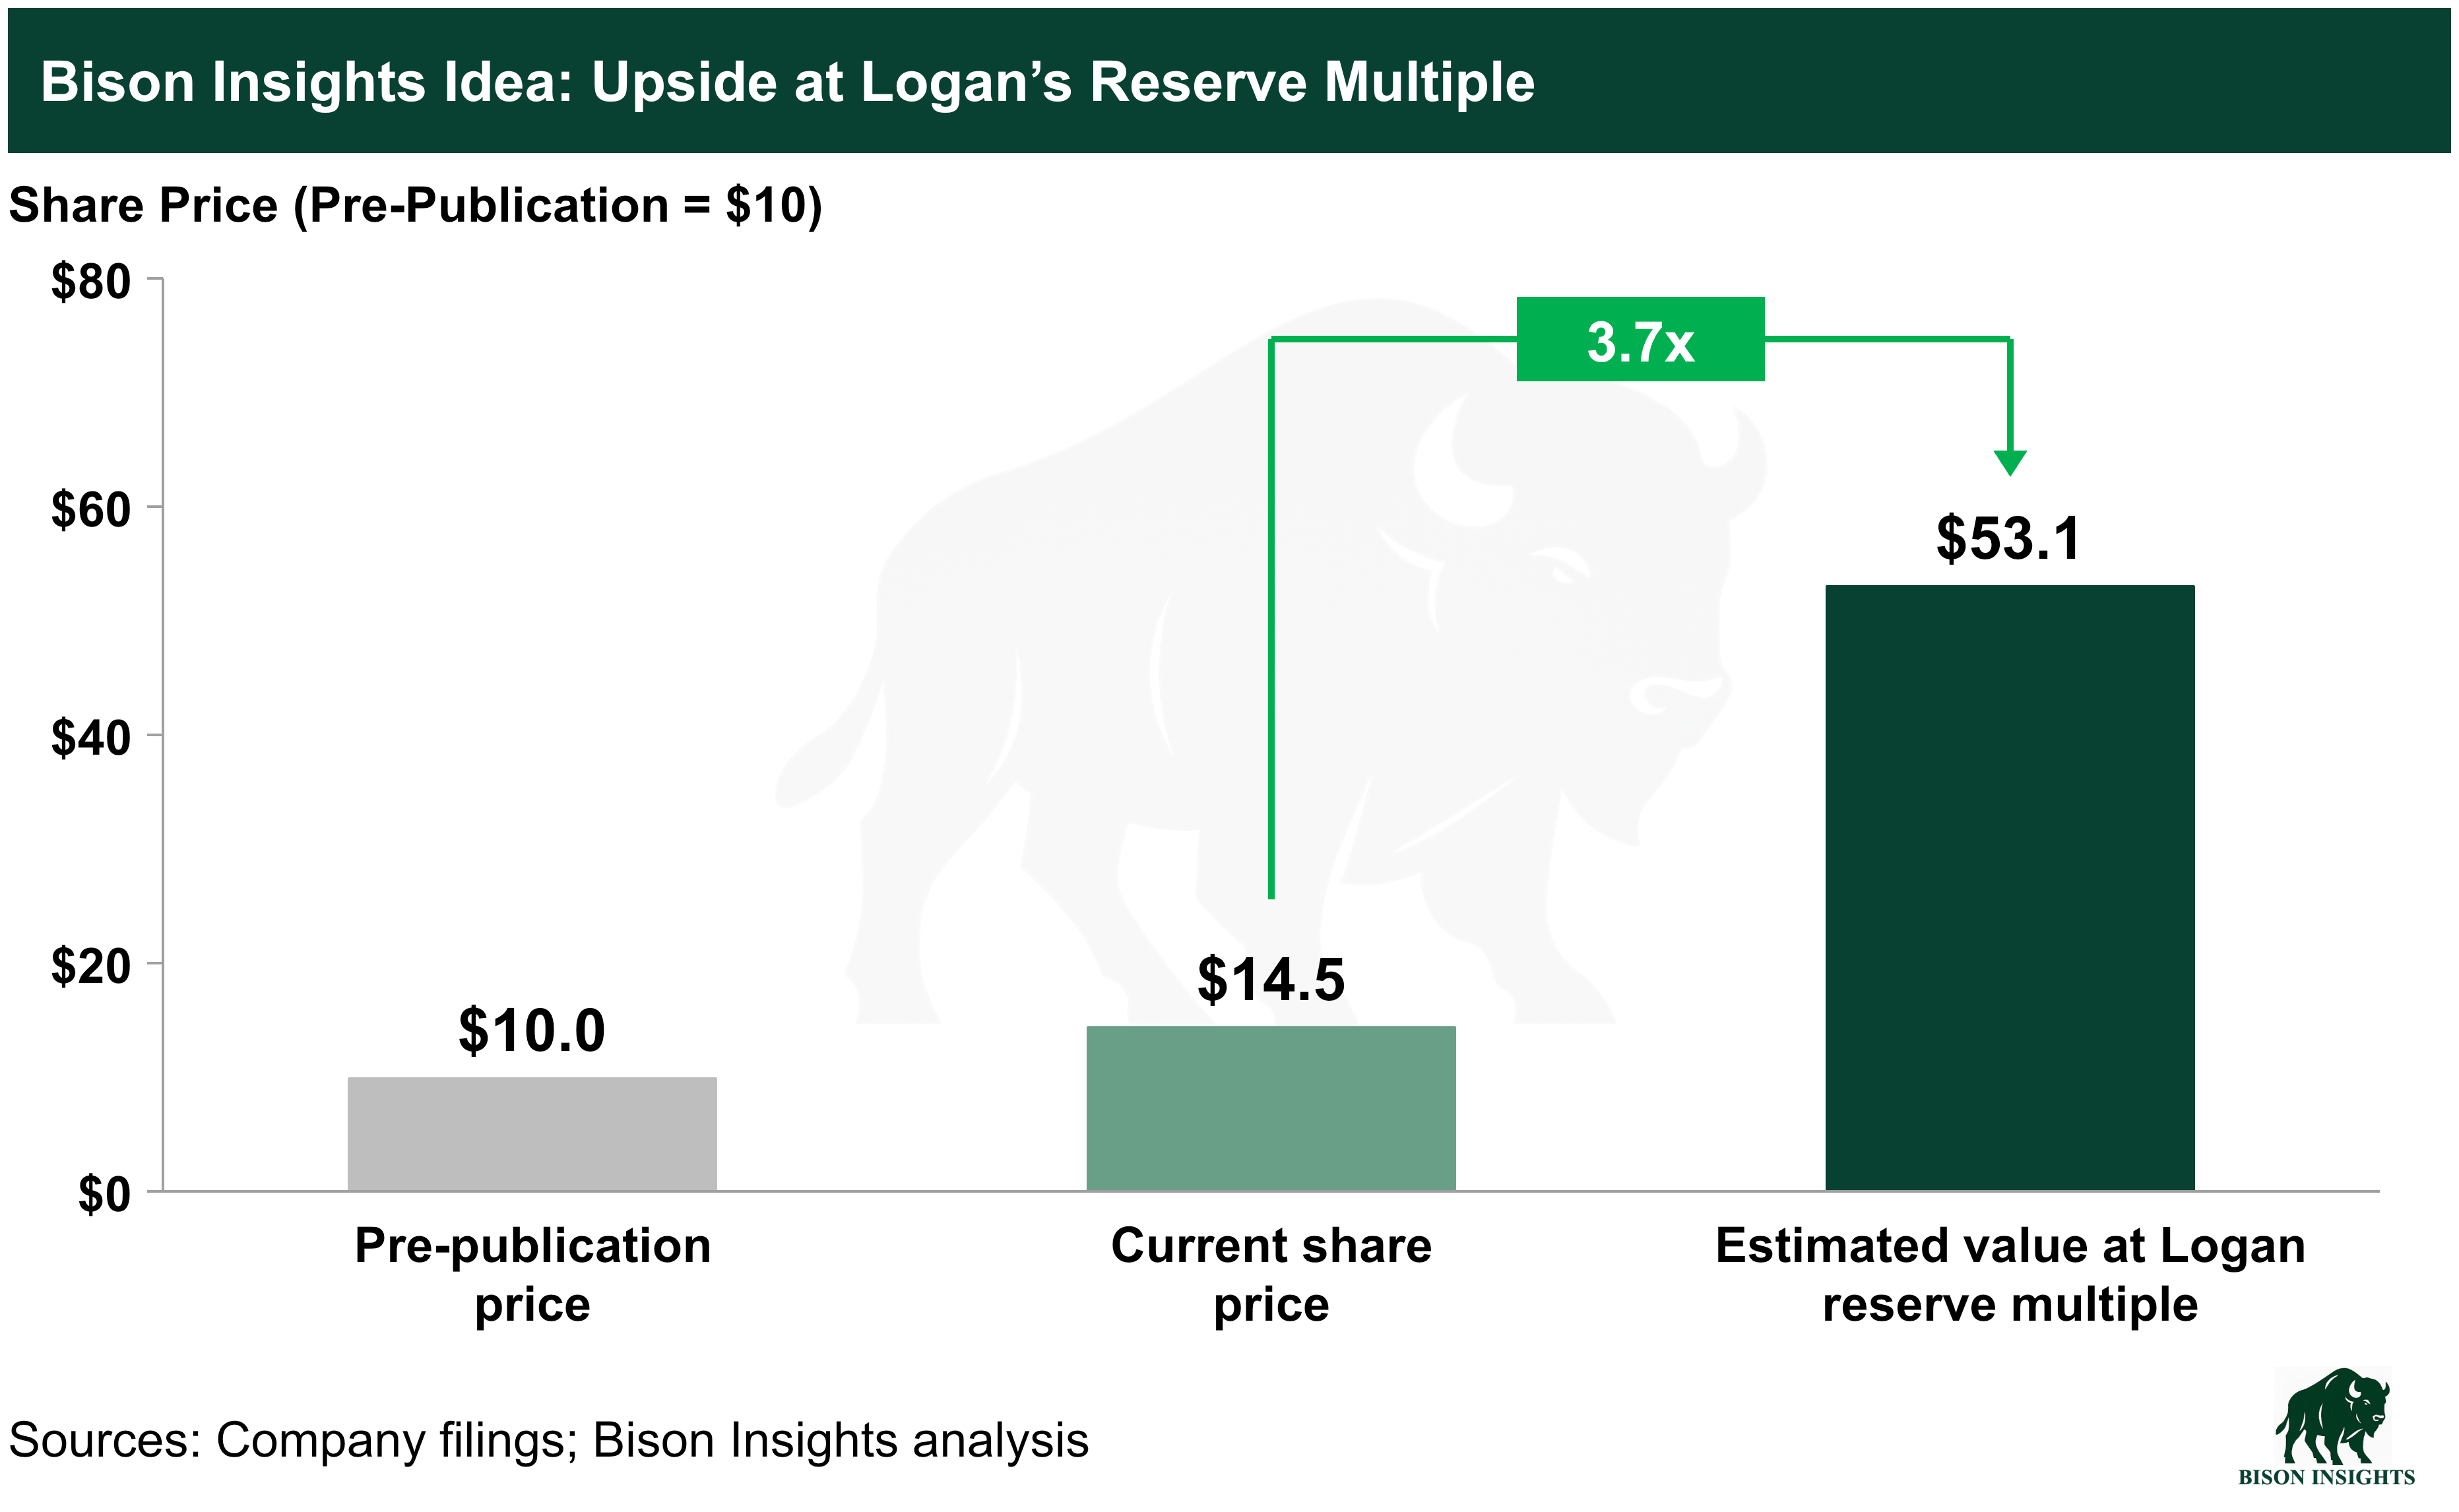
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…
Transocean’s 25.6% selloff reflects oil-market shorting and weak Q3 headlines, while debt reduction after the Valaris acquisition could…
Diversified Energy reported $255.6 million of “true” nine-month free cash flow, while its $1.8 billion Birch acquisition would shift…
@HunterAllen4 And what keeps the Navy locked in is licensing. Only two U.S. plants hold NRC licenses to make fuel from high-enriched uranium, and both are $BWXT's, Erwin and Lynchburg. The 10-K calls Nuclear Fuel Services the sole provider of Navy fuel.
Western Midstream raised 2026 EBITDA guidance by $250 million to at least $2.85 billion as organic projects and the Brazos Delaware…
 Gary Gambino
Over the next three years $GPRE earnings are going to exceed its entire enterprise value.... That's insane and it isn't based on any temporary factor such as the Iran war. These are durable, sustainable earnings. How does the market possibly come to a $14 valuation on this? Insane.
EQT becomes the largest U.S. natural-gas producer after acquiring Range Resources, with takeover speculation centered on Berkshire Hathaway…
@WaterworldCapi1 Do you like any of the power shell names? $WULF seems more interesting
There is a reason $ANDE just paid 4.25x ethanol production for three ethanol plants. Based on that - $GPRE would be valued at least at $35 per share factoring in converts if not $40+. The market is completely missing this (and $ALTO)! An acquisition literally just validated this days ago.
$GPRE has generated ~$280M of EBITDA through the first 9 months of the year. Based on today's report, $GPRE enterprise value as of 9/30 was ~$1.3B which does not include the 45Z credits. If we include them... EV = $1.085B. Are you kidding me? How is this stock not $30+???

Data centers need power delivered on schedule, not just efficient generation. $EROC builds on-site power systems around natural-gas reciprocating engines, a different technology from the turbines in short supply. These engines can supply AI data centers before grid connections or gas turbines become available. In our view, their role is broadening from temporary backup toward sustained operation as turbine shortages persist. 1. ERock has a 470MW equipment order from Anthropic. 2. It is delivering a 366MW generation project with El Paso Electric to support $META’s data-center campus, with initial commercial operation targeted for mid-2027. 3. Production commitments extend into 2028, giving ERock demand visibility while making assembly capacity and delivery execution more important. ERock sources engine assemblies from specialists, then integrates them with electrical equipment and control software. In our view, that ability to commission a complete power system quickly is the company’s main advantage. For a customer with computing equipment waiting for electricity, earlier delivery can outweigh the higher fuel efficiency of a combined-cycle plant. Delays or cost overruns would weaken that case. In our view, the next test is whether ERock can convert these commitments into operating systems on schedule and profitably.

@Kyle_Landau_88 stricter energy policy good for $BE
@ChrisMi99288379 data center build out could slow but stricter energy policy for data center build out probably helps $BE

