
Raging Capital Ventures on X
@alphaporgs I own a lot of $CMCSA.
NASDAQ
CMCSA
13 stories
$81B Market cap · 2026-10-26
@alphaporgs I own a lot of $CMCSA.
@petter_nil22208 I’m long, but prefer $CMCSA here given spin-off catalyst. Will have more thoughts after earnings.
$NFLX should use its lofty market cap to buy/merge with $CMCSA’s NBC Universal while it still can. Build the new “Disney” by buying a leading studio; a major broadcast network with football, Olympics and Premier League; and the second largest theme park operator.
Tempted to buy some $CMCSA Jan 2029 calls... Spin coming mid-2027 so these would expire ~18 months later... plenty of time for spinco/remainco to play out a bit https://t.co/tBb3nxBm0U https://t.co/d9fAPlwd5K
A lot of cheap catalyst names out there... $OWL @ $9.00 $CMCSA < $22 $VISN < $6 $AKER.NO < 1,400 NOK $MGBL @ $17 $DRVN < $12 $FM.TO < $40 CAD
But if returns on capital are declining for everyone, the choice is whether to eat or to be eaten? $T is willing to subsidize fiber as a loss leader to protect their wireless margins. $CHTR / $CMCSA are likewise willing to give away wireless to protect their broadband margins… which comes back to the question: which is stickier, your phone or broadband line? I think $CMCSA works because of the spin unlock and sheer strength of their balance sheet. $CHTR is a very long dated call option with more risk, but much more upside if broadband losses attenuate and/or they allocate capital intelligently (although $CHTR’s balance sheet is more levered, there is tremendous optionality in its duration, cost and structure).
@BigIdeasCapital I agree with the logic and own both $CHTR and $CMCSA, but what if cell phones are stickier than broadband lines? $T’s fiber “loss leader” offering might be more attractive than cable’s cheap wireless service?
Comcast $CMCSA looks dirt cheap. I see a much higher valuation on sum of the parts. Everyone hates “dying” media companies. But there’s always one last puff, and I swear to god, I’ve been smoking roaches since the dawn of time. Also these guys own some of the greatest traditional media assets in the world. Tell me why I’m wrong. And don’t go blah blah blah about a catalyst.
 CMCSA 2026-08-28
Comcast's mobile growth, Verizon roaming agreement, NBCUniversal content and theme parks are positioned to offset broadband competition…
 Max Greve 1 click
I’m now very bullish on $CMCSA as well. In my view, Peacock/NBCU/theme parks are likely worth around the current market cap alone. Importantly, Peacock / NBC are now competitively advantaged in sports media thanks to a superior combination of reach with their NBC broadcast network and their scaled streaming platform. Comcast Cable is struggling, but they have frontloaded a lot of pain; wireless and the bundle is a growth engine; and the balance sheet is actually a strength (not a weakness). Plus, the 6% dividend pays you to wait for the spin in 2027.
Bought a bunch of $CMCSA on this fade back to around $25. While it will take around a year to breakup the business (and they don’t plan to buyback stock during this time), separating media/theme parks from cable should be very accretive to the valuation.
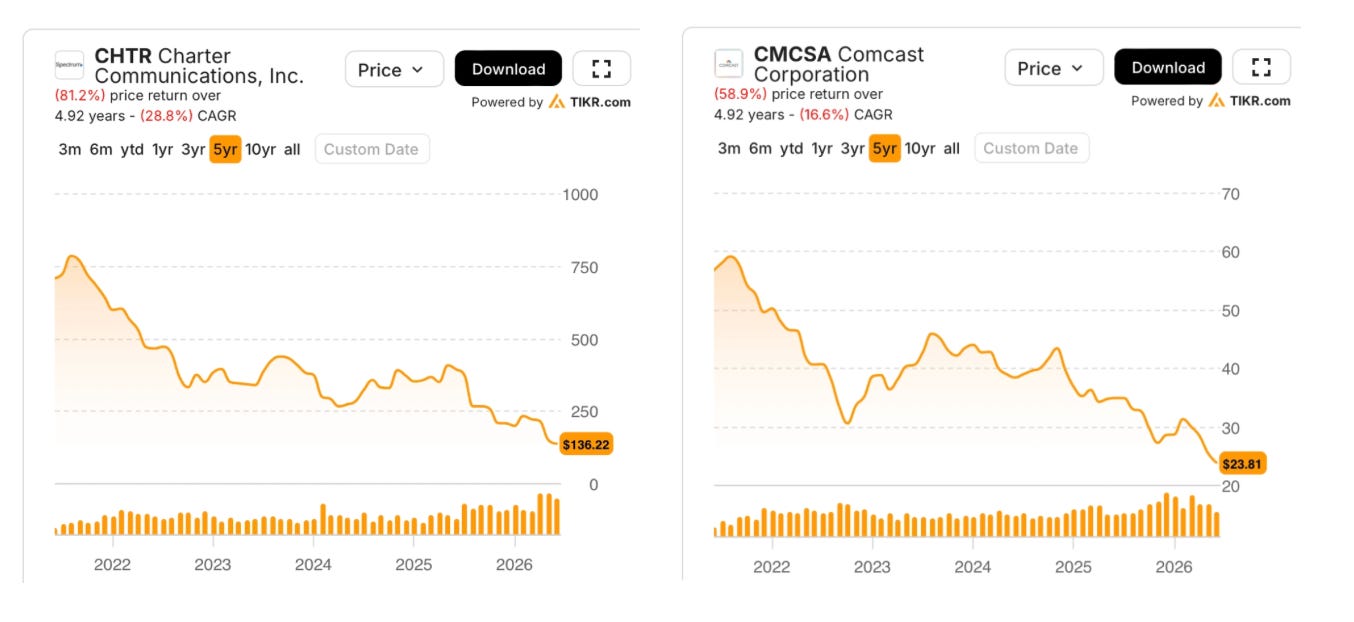
Charter’s $11 billion to $8 billion capex plan may not be durable as copper-network upgrades face fiber competition, while CHTR shares have…
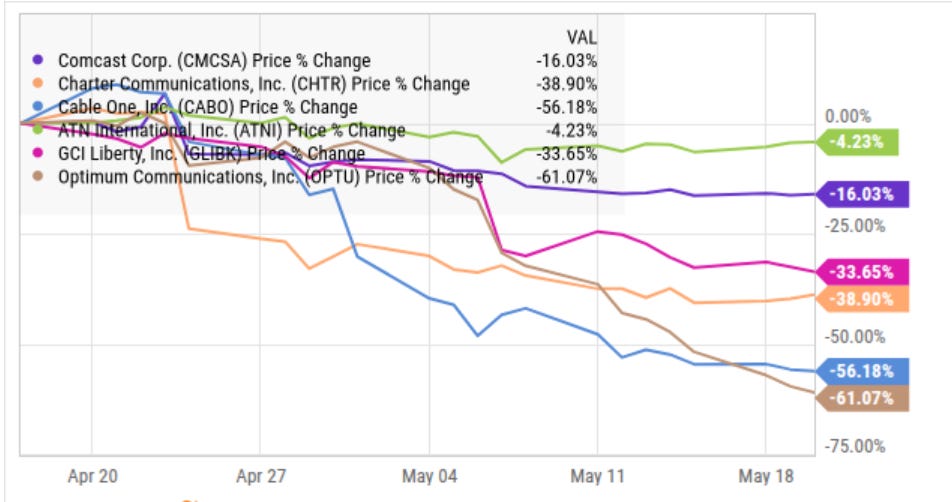
Cable stocks face renewed broadband share-loss concerns from LEO satellites, while AI links cover Microsoft, Google, Amazon, Anthropic and…
Letters that discuss CMCSA.
Companies the stories above are also about, besides CMCSA.
