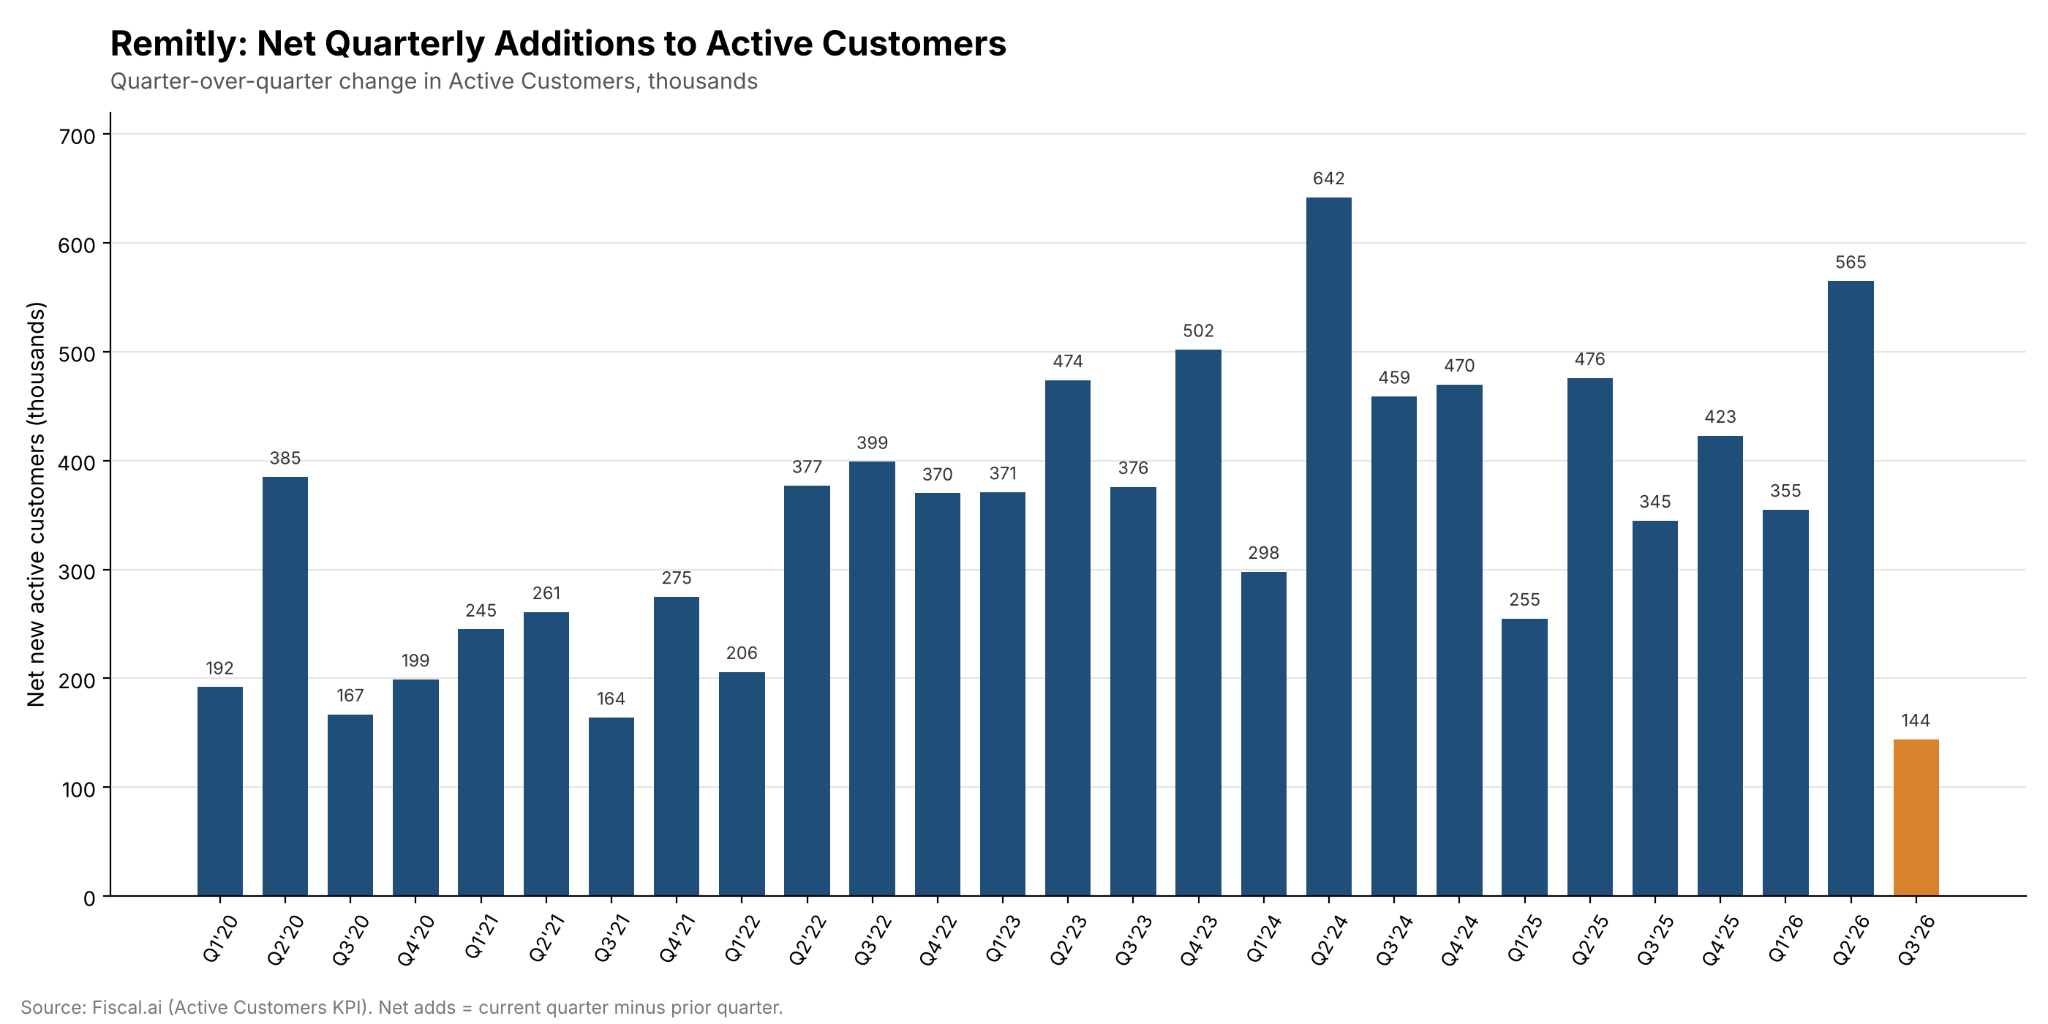
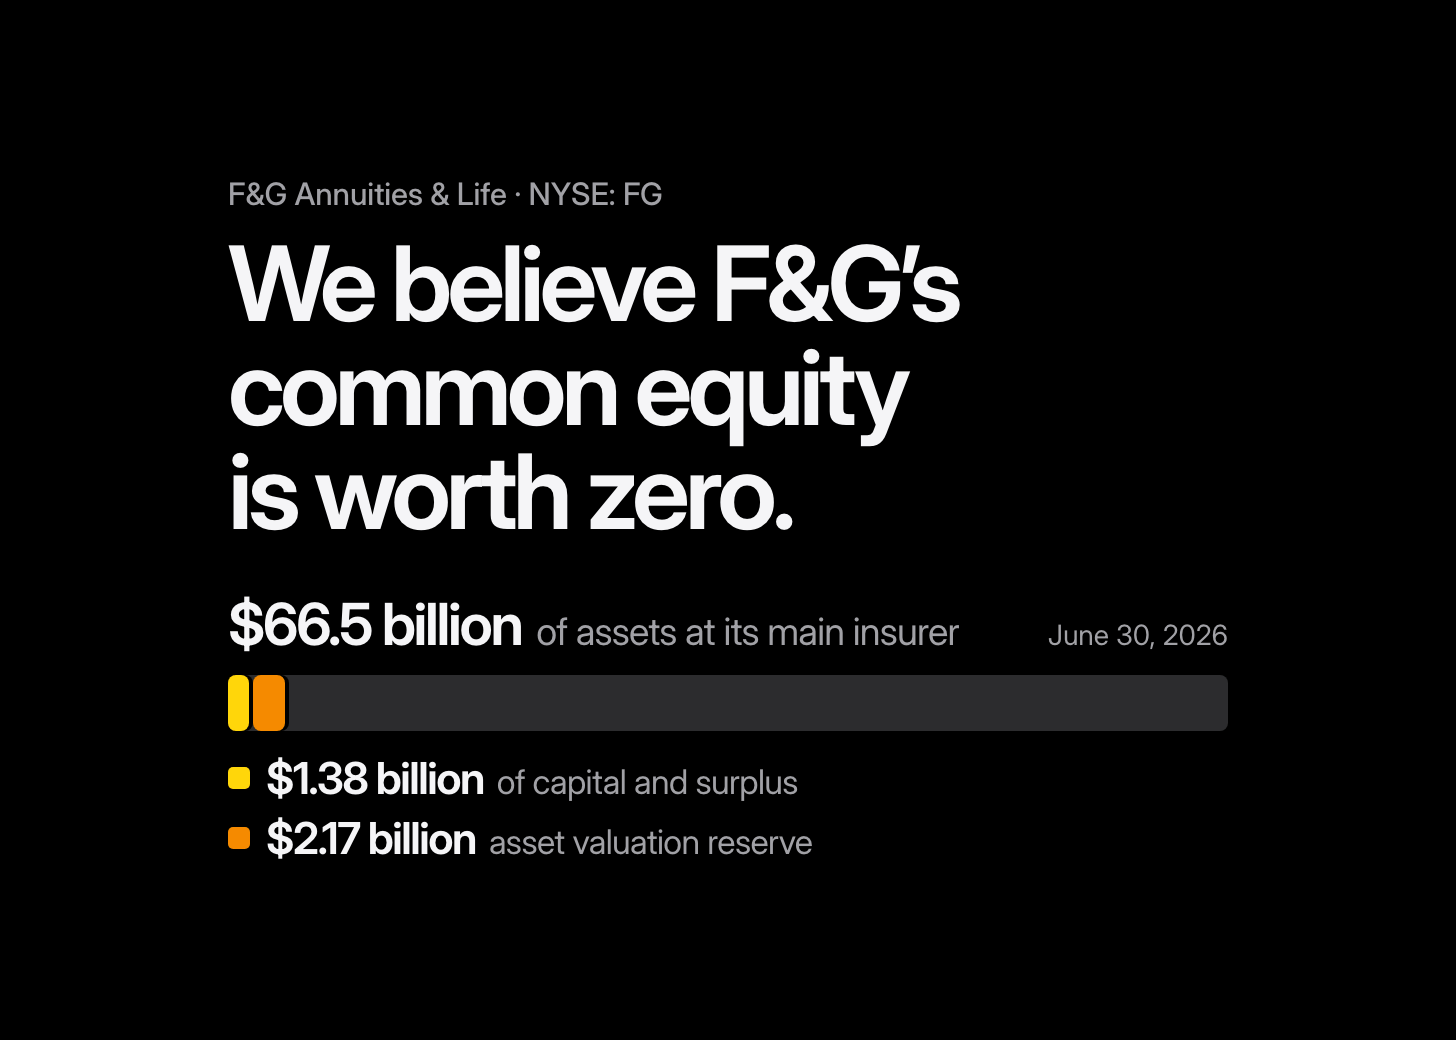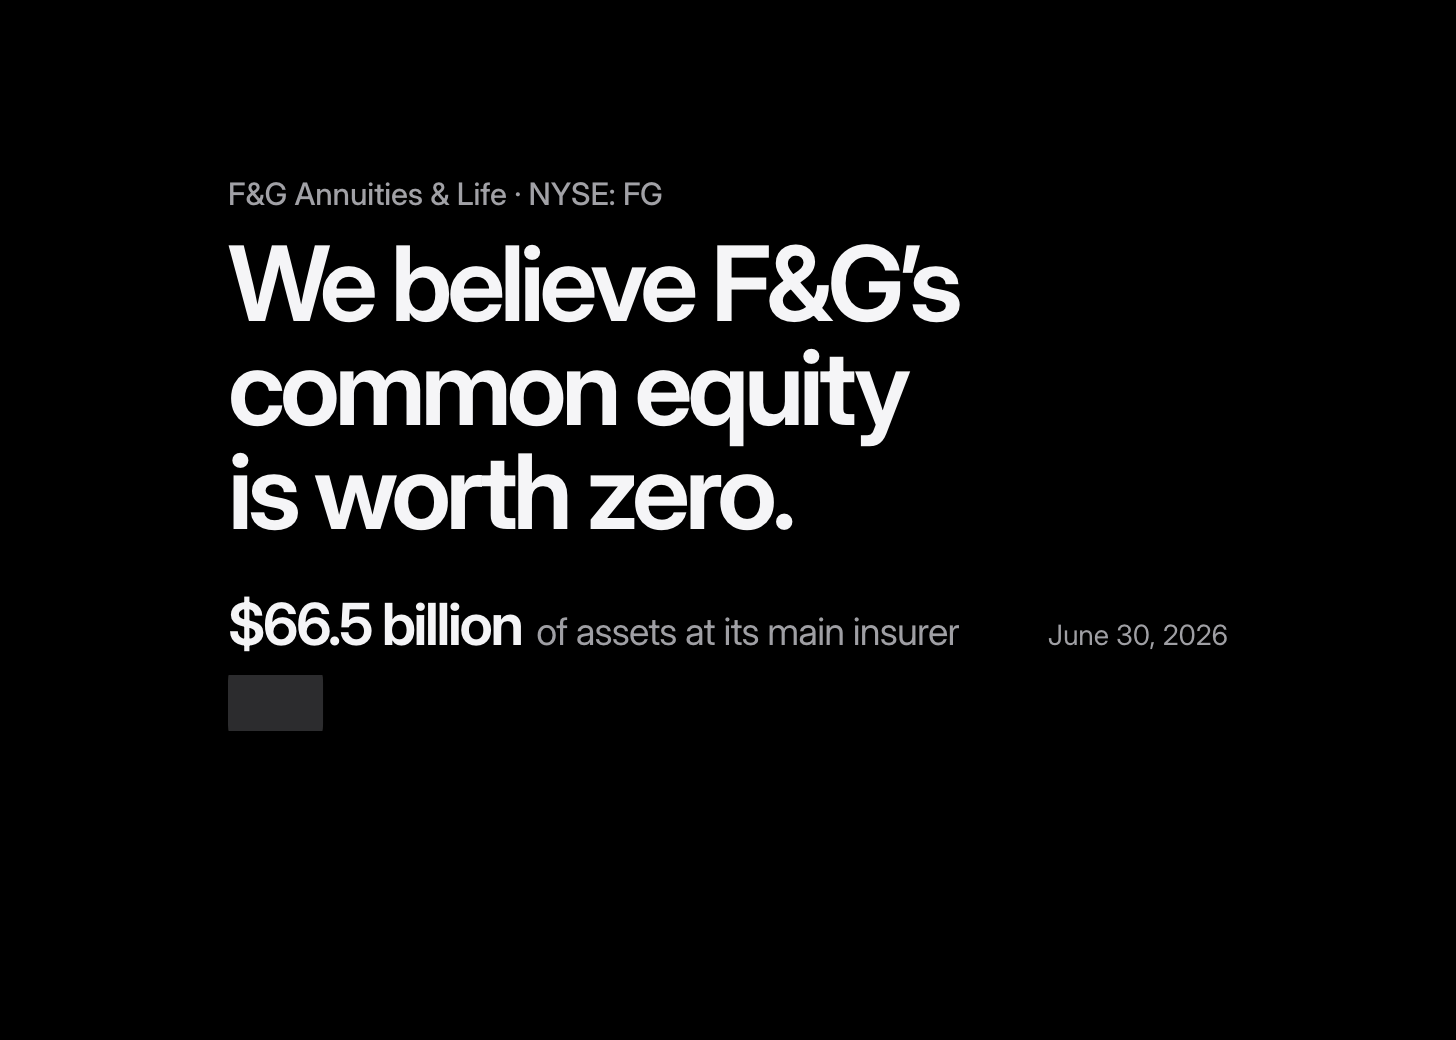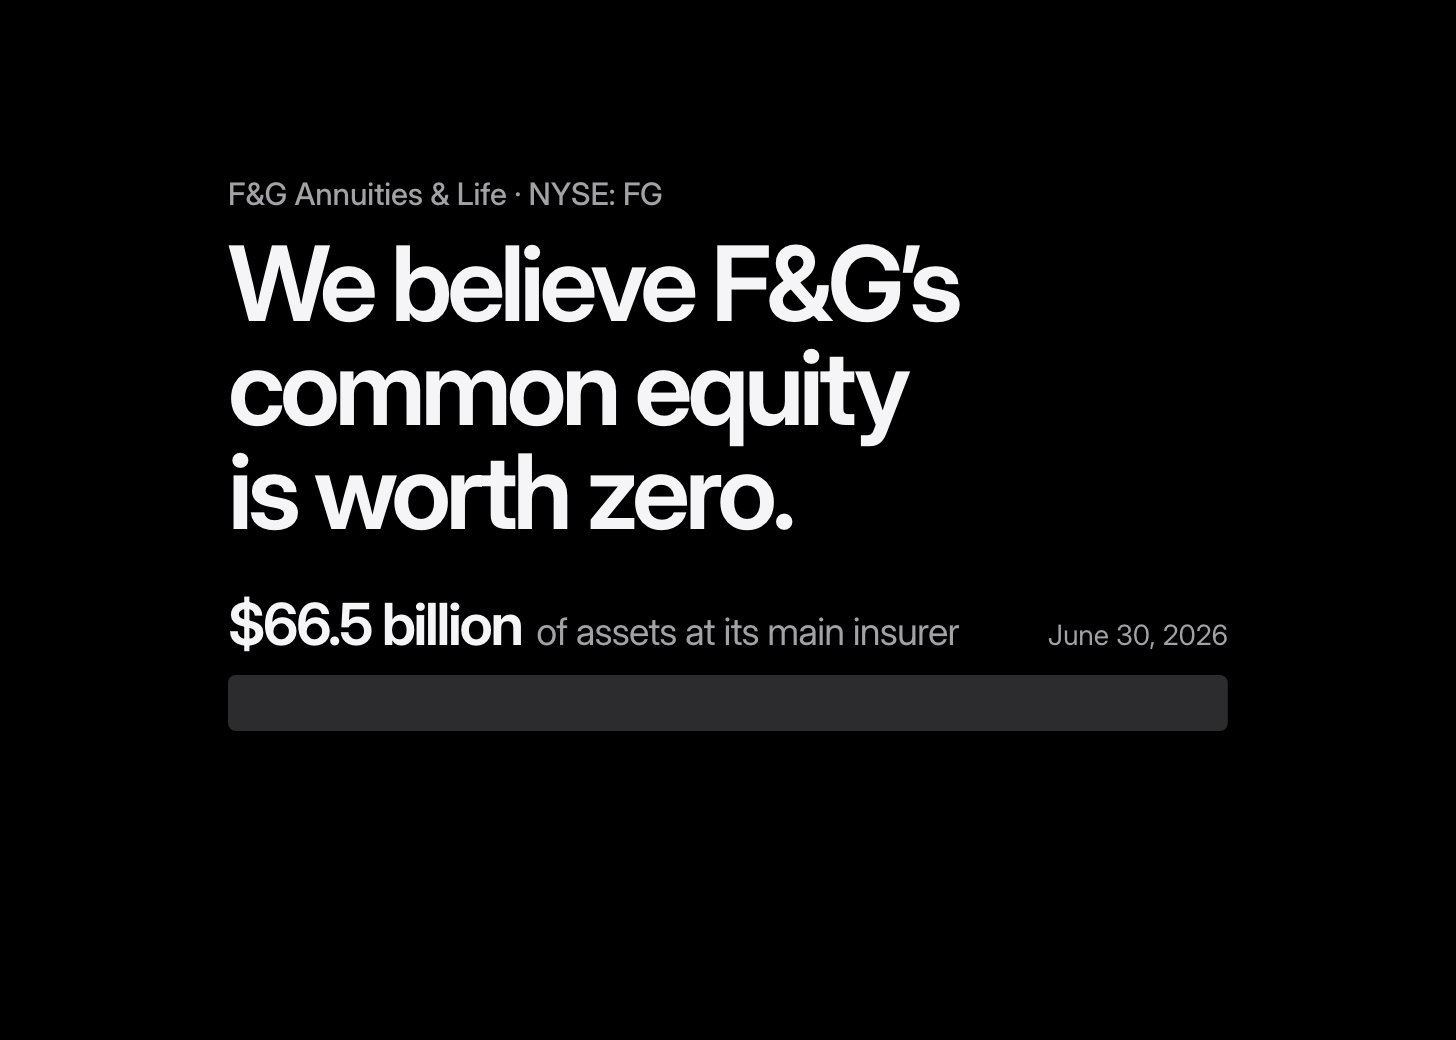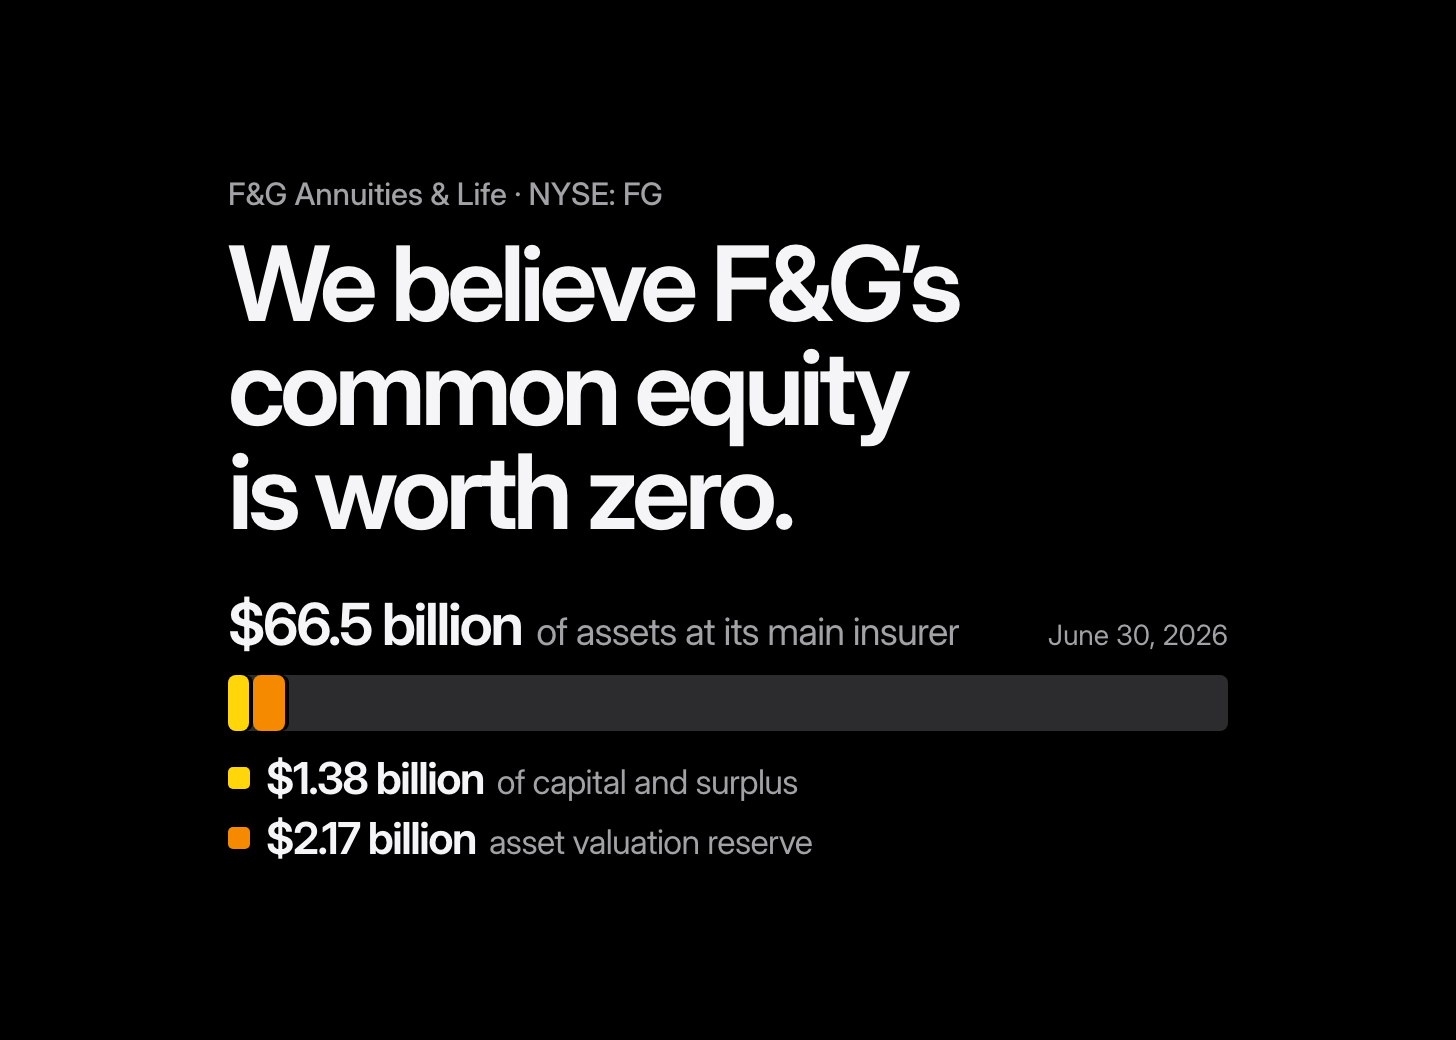Remitly’s Q3 keeps its remittance growth thesis intact as spending cards, memberships and credit products target $1 billion in annual…
S Emerging Moats Research 8h ago 3 clicks
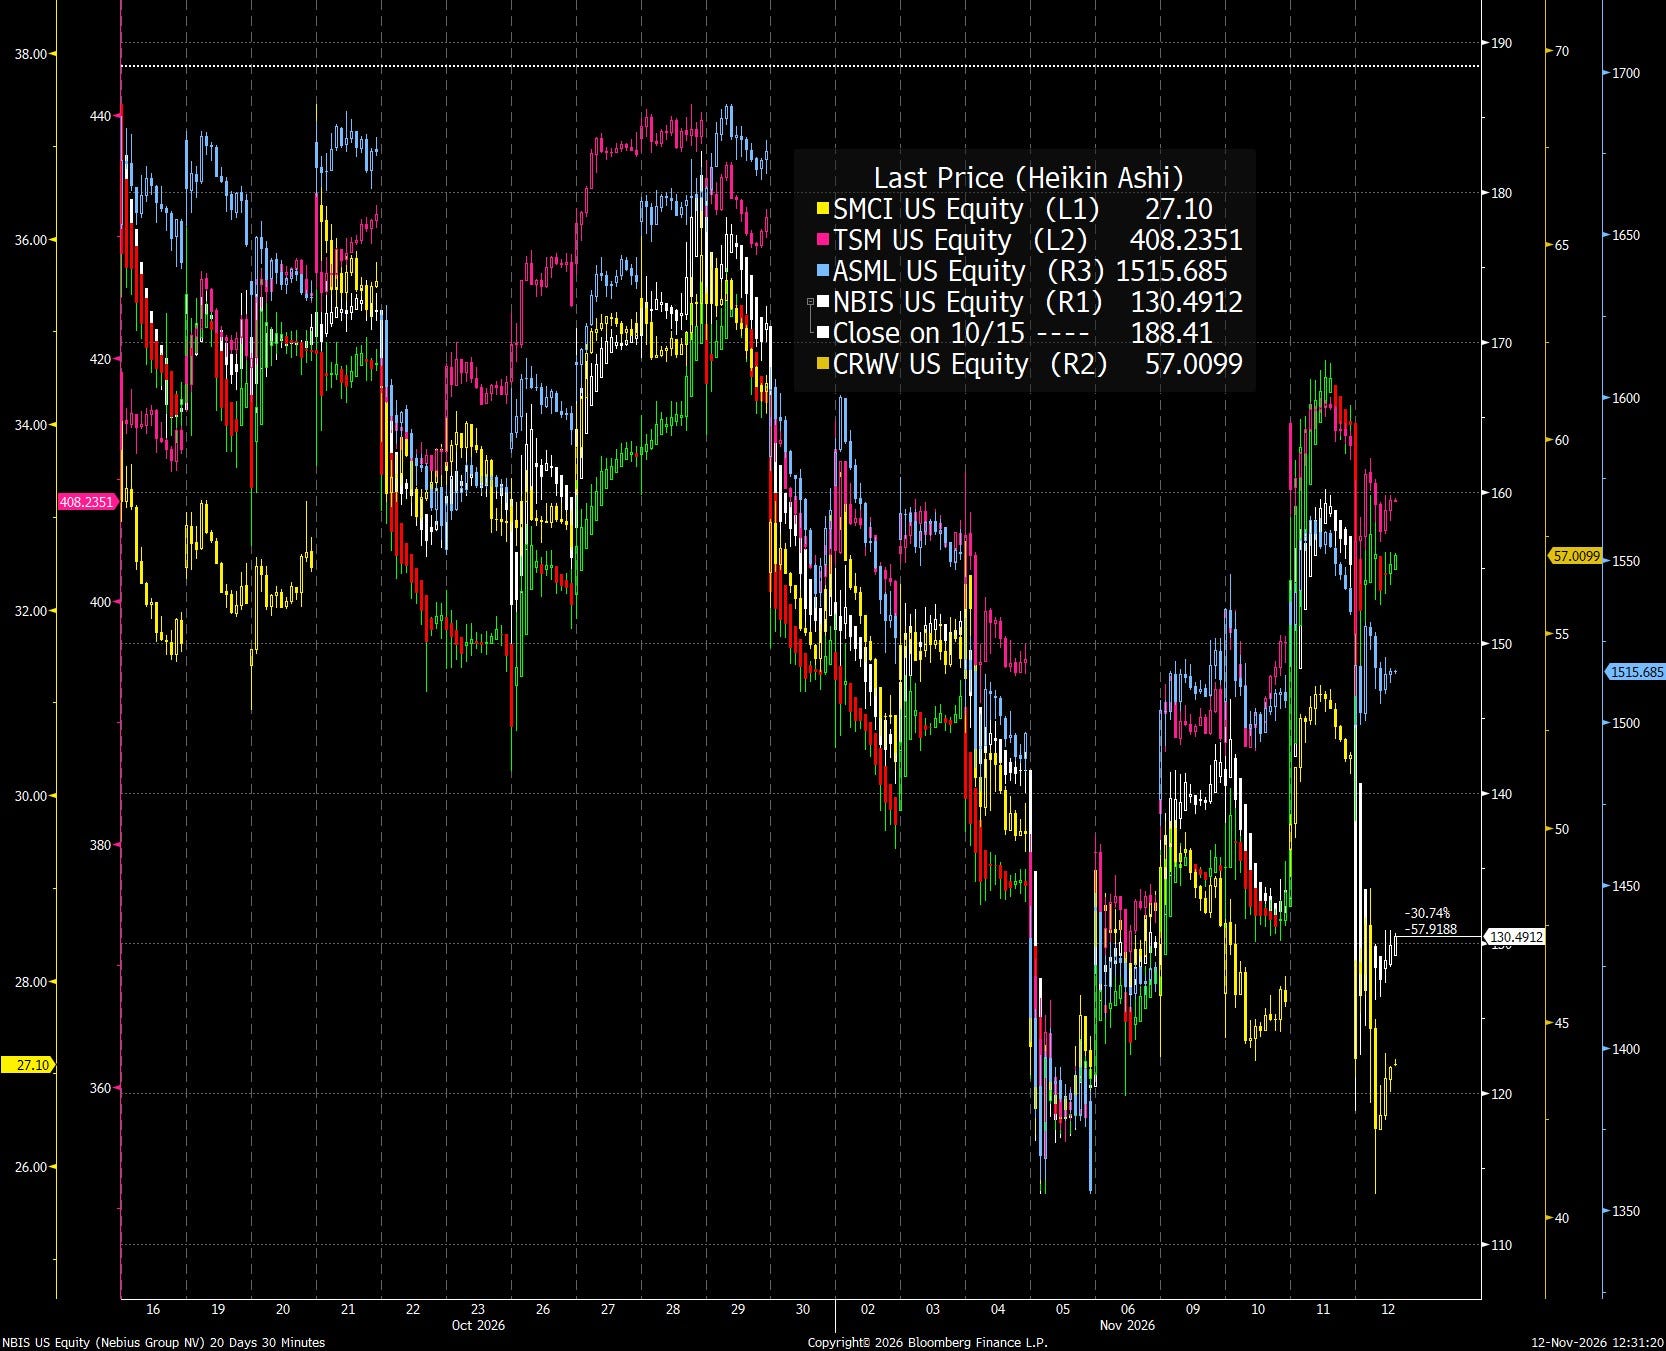
Nvidia’s alleged guarantees for cash-strapped chip customers and heavy wafer and memory commitments raise concerns about AI demand and…
S Cassandra Unchained 9h ago 4 clicks
QXO's Q3 sales rose 79% to $4.9 billion after TopBuild and Kodiak acquisitions, while acquisition debt lifted interest expense to $163…
S SixSigmaCapital: Navigating the Financial Markets 13h ago 2 clicks
Nvidia CEO Colette Kress signals a pullback from the financial schemes pursued under Jensen Huang.
BL The Technology Letter 16h ago 1 click
NVIDIA faces DOJ antitrust probes alongside inquiries into Megaspeed and Super Micro, after charges over $2.5 billion of GPUs allegedly…
S Cassandra Unchained 20h ago 4 clicks
Nvidia’s Jensen Huang resignation leaves a flat organization built around his direct control as China GPU restrictions tighten.
S SemiAnalysis 22h ago 6 clicks
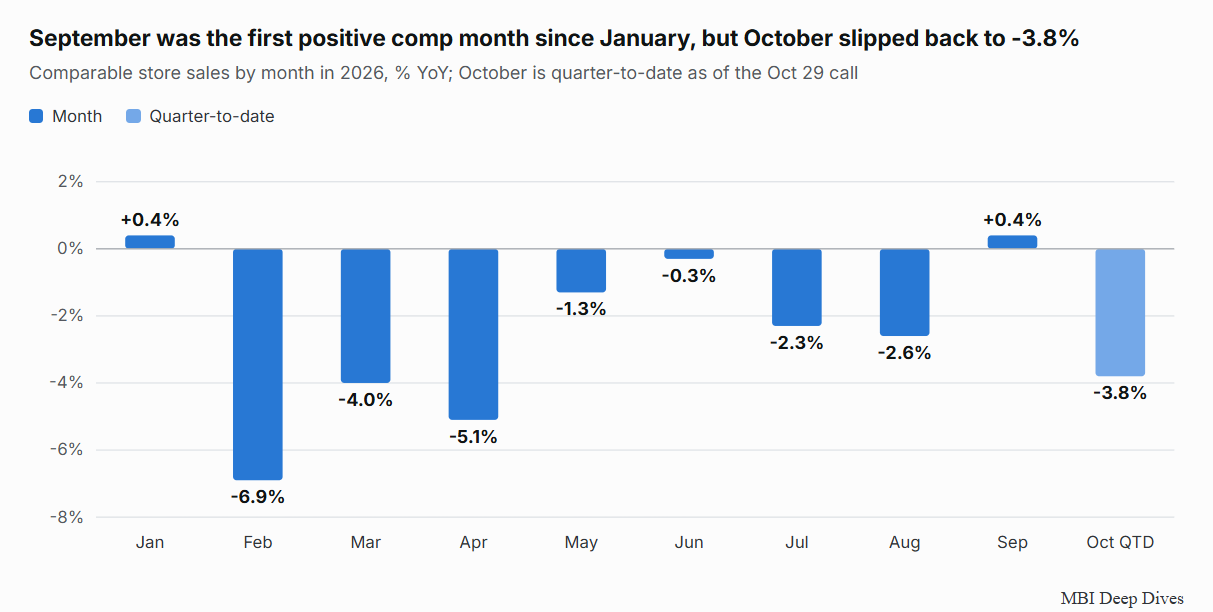
Floor & Decor cut its 2026 outlook again, with EBITDA guidance falling to $535-550 million and 2027 openings slowing to 10-15 as housing…
S MBI Deep Dives 23h ago 3 clicks
F&G’s main insurer held $66.5 billion of assets against $1.38 billion of statutory capital, while private credit, reinsurance dependence…
S Mispriced Assets 24h ago 4 clicks
AutoNation’s new CEO Mike Manley brings Jeep and Fiat Chrysler experience after the dealer chain cycled through three leaders in 30 months.
S Cannibal Stocks 24h ago 3 clicks
Salesforce’s Agentforce adoption, Anthropic and Databricks stakes, and margin expansion support upside, while debt-funded buybacks have…
SA Alexander Grover 24h ago 1 click RXO · short RXO, a top-five U.S. freight broker, carries roughly 5x LTM EBITDA leverage and undisclosed off-balance-sheet liabilities after its 2022…
BL Value Investors Club Jul 27
Meta reported Q3 revenue of $64.6 billion, up 26%, while $34.9 billion of capex drove negative free cash flow and a $9.89 billion legal…
BL Cestrian Capital Research Oct 22 2 clicks
Solstice, Albertsons, Brockhaus and GM anchor a 34-case survey of activism, buybacks, M&A and strategic reviews, led by Starboard’s…
S Latticework by MOI Global Oct 22 43 clicks
Rollins, North America’s largest pest-control provider, gets 75–80% of revenue from recurring contracts but has fallen about 45% year to…
S Jimmy's Journal Oct 22 68 clicks
Group 1 Automotive and Lithia Motors divide two longtime value investors: David Abrams switched to Lithia in 2018, while Greg Alexander…
S Cannibal Stocks Oct 22 6 clicks
Diageo expects Gen Z cocktail demand, completed restructuring and margin recovery to lift net income from $1.7 billion in 2026 to $4.6…
SA PropNotes Oct 22 7 clicks Atour Lifestyle combines an asset-light Chinese hotel franchise network with Atour Planet sleep-product sales, using guest rooms as product…
S Substack von Philipp Oct 22 8 clicks
Weyerhaeuser’s $23.07 sum-of-the-parts valuation rests on discounted timberlands, while its 4.3% dividend needs stronger free cash flow and…
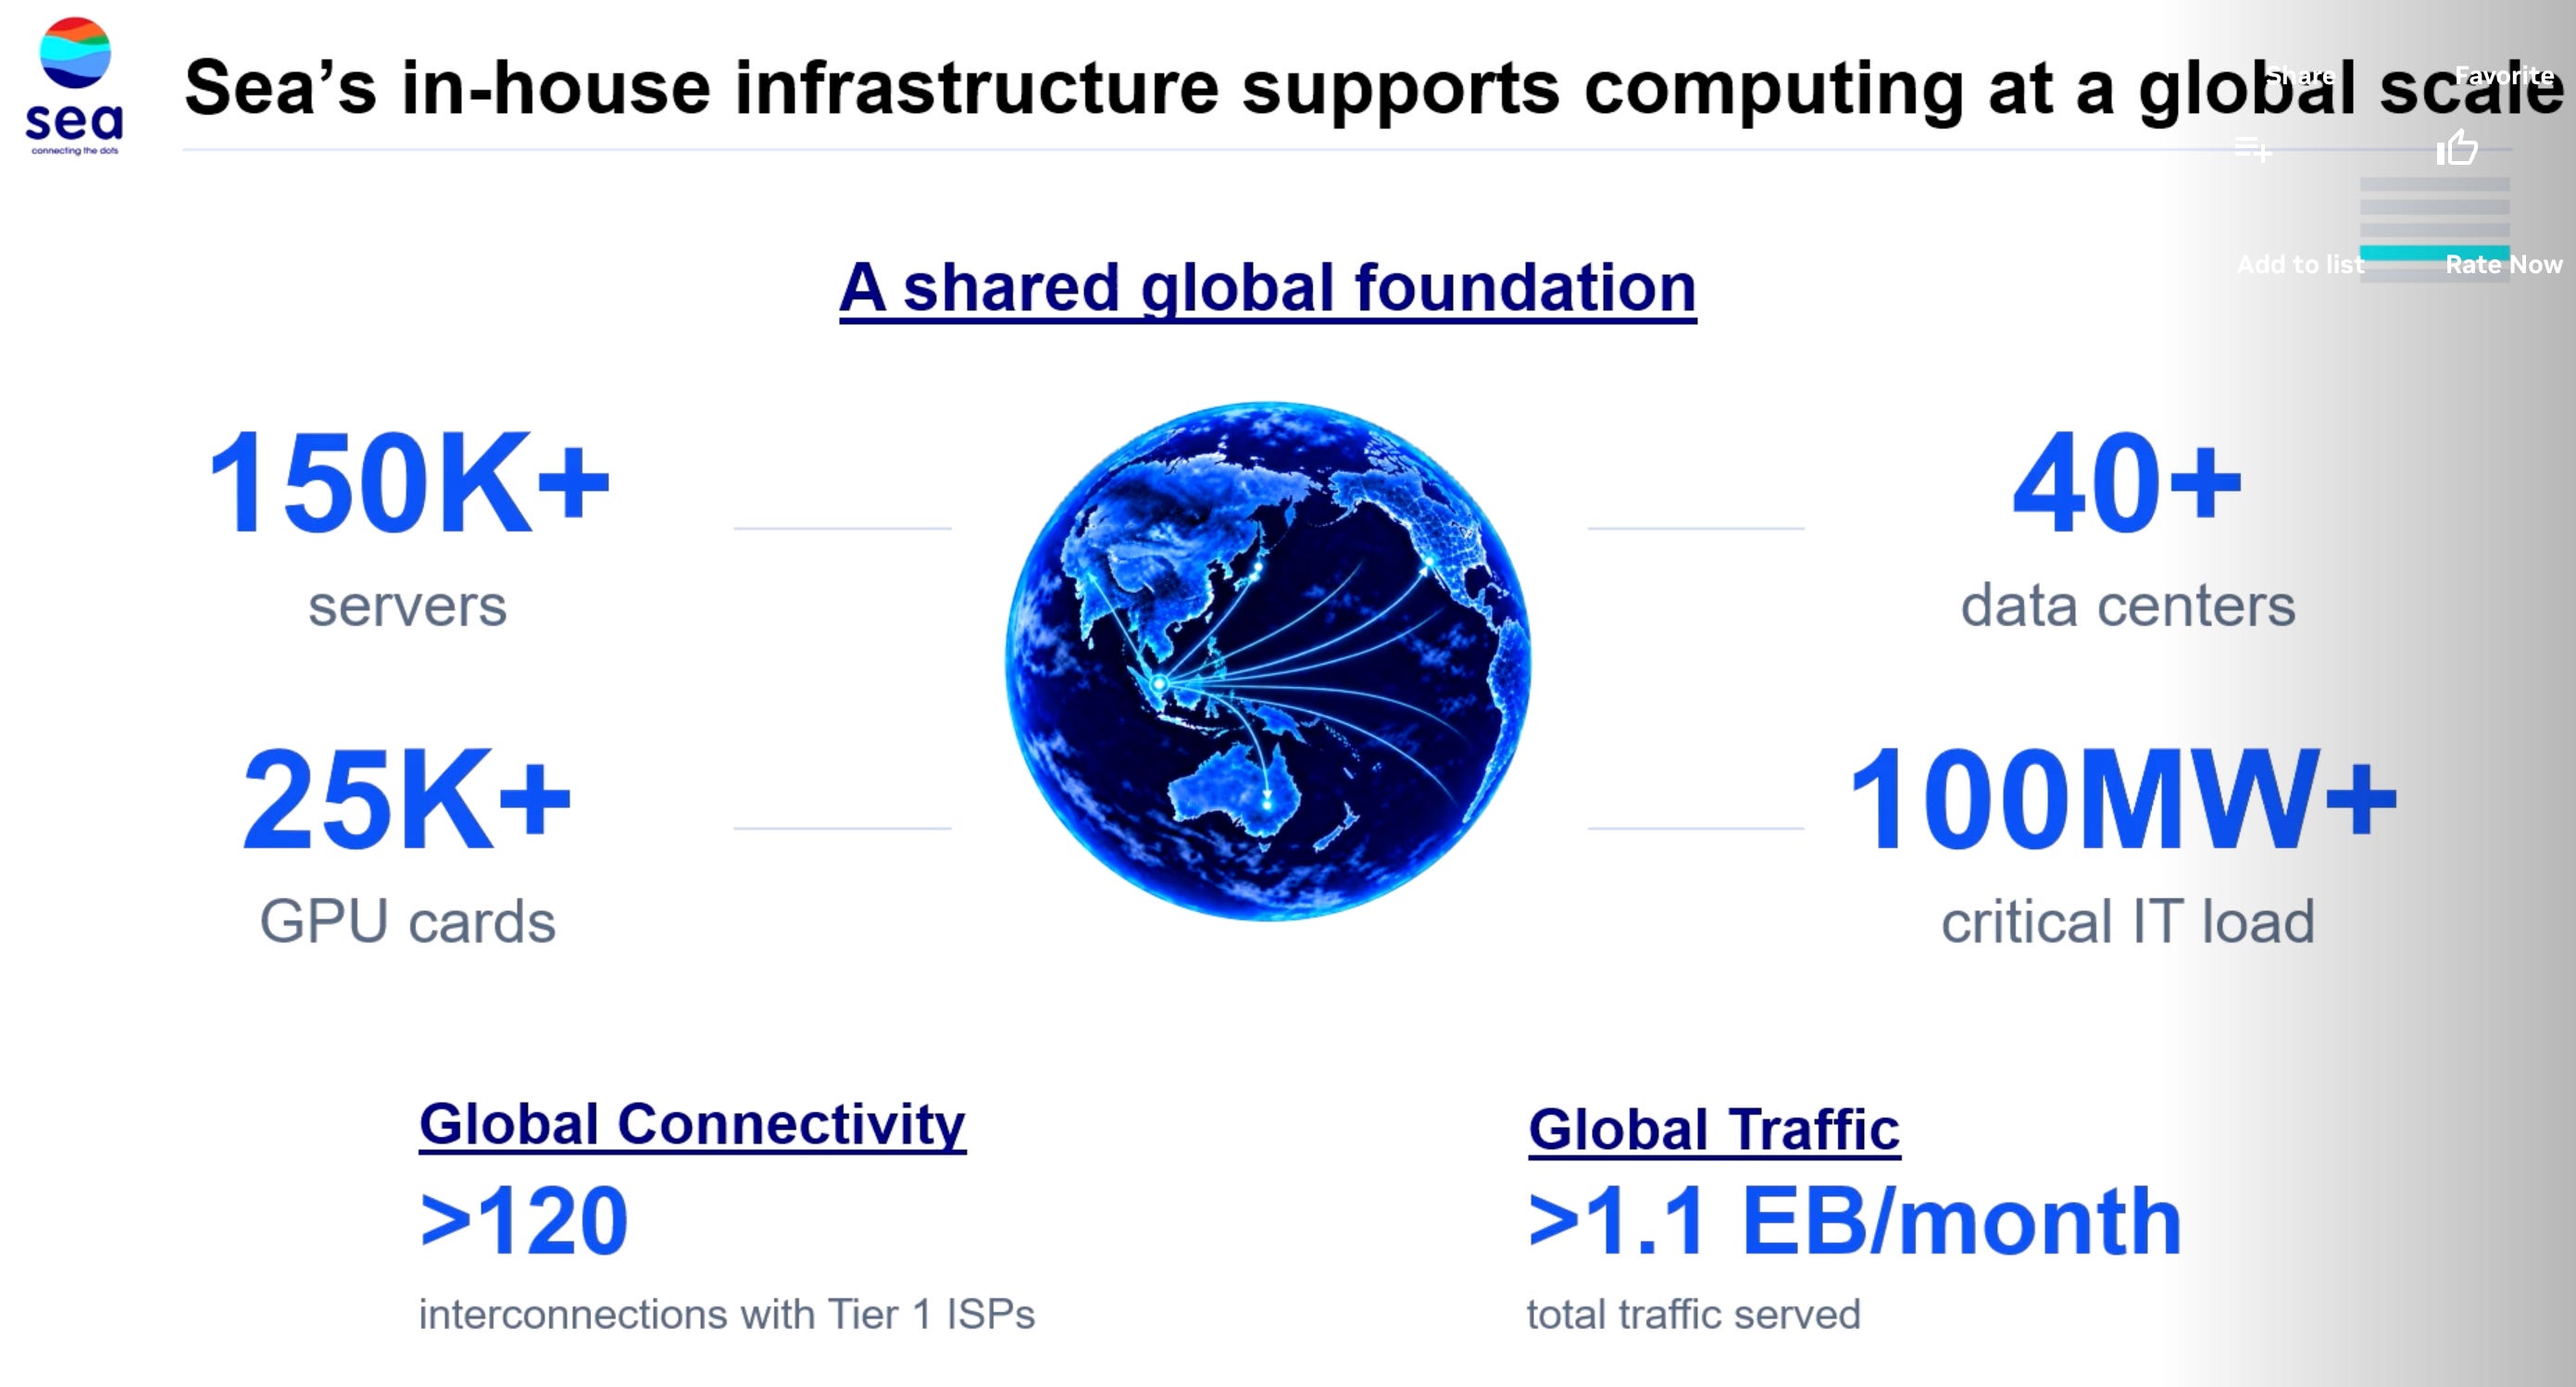
SA Atlas Diary Oct 22 9 clicks Sea Limited plans Sea Cloud and a Monee IPO, using 40-plus data centers and 25,000 GPUs while risking heavier capex and prolonged thin…
S Sleep Well Investments Oct 22 6 clicks
Meta’s 3Q26 Family of Apps revenue rose 26% as Muse reached 10 million users, testing AI-agent shopping that Walmart permits while Amazon…
BL Speedwell Research Oct 21 10 clicks