
The Agentic AI Roadmap for SaaS
SaaS companies including Salesforce, ServiceNow, CrowdStrike, Synopsys and Veeva are ranked by agentic AI progress, from pilots to…
NYSE
CRM
16 stories
$191B Market cap · 2026-10-30
SaaS companies including Salesforce, ServiceNow, CrowdStrike, Synopsys and Veeva are ranked by agentic AI progress, from pilots to…
Software sentiment matrix from JPM’s Schilsky I guess Dreamforce with guest appearances from Jensen, Dario and Sama wasn’t enough to fix $CRM sentiment https://t.co/pzGxbvVR9j
A few take aways from the $CRM Dreamforce keynote today.... It is difficult to watch at times with all of Marc's promotional showmanship but still worth it to understand how a bunch of legacy software companies are attempting to reposition themselves in terms of the AI era. The sell side will defend this tomorrow, thats the business they are in, but you should look at it for yourself unbiased. Ask yourself this first: .....you can claim SaaSpocalpyse over, the V shape rebound came, ARRs didn't plummet overnight.... That was never going to happen, the newspapers are still here, but their subscriber bases are decimated, or they moved online and the pricing models were drastically decreased. Reach potential increased, but so did competition (exponentially) and barriers to entry were and are radically lower then pre internet. If this was not existential and just a panic and the rebound is entirely justified why did the largest SaaS application company just remove their ui, conceded their metadatabase to their biggest competitor and is undergoing a pricing model change in real time, so change is upon us, time to look what happens next CRM going full force into being basically a database company now, hoping the underling data you built with salesforce over the years and the legacy connection will be enough to keep you around and paying them to essentially host your data for you with a Claude or other ai intelligence on top doing the work. Slack is the most relevant product they have and the biggest sticking point in those conversations, but how long will that last? Zoom should have died off by now, with Teams and others giving away video conferencing which shows you entrenched behaviors and a narrow network effect can defeat economic interests. Time will tell on slack. Ultimately I think a layer like snowflake that can tap data structured and unstructured across applications is the data layer and governance apparatus to build wrappers and dashboards from using multiple Ai models. Versus keeping the data siloed into the old applications from the prior generation and having to access them, or pay them all individually as databases and then building a mass MCP through all them to get to the unified data solution (much easier then ever before to migrate and move data the friction has dramatically been lowered). Seems a lot easier to have one data layer across an enterprise versus taking a salesforce, connecting it to Claude then having to connect that to Gong, granola, gmail, etc for your sales force and cs reps. Then creating channels with workday or paycom and connecting special channels for intuit and adp separately. And so on with each roles/departments specialized applications they use in a given day and giving database, governance, ai training, security etc and having to manage and permission all of these ai/database modules versus a central one stop shop with Databricks or snowflake (id say amazon or google, but no one is going to go all in on one cloud storage for outages and pricing reasons if large enough but I think they have a better argument/permission to win this space if they wanted to then Salesforce or worse a Paycom)....see the snowflake Q2 call to better understand their vision as competing to Marcs strategy laid out today. End of the day, I don't think when you look out three years these SaaS applications have the same relevancy in terms of users but more importantly on pricing (dropping the UI works for AI and looks cool in a demo, but it also erodes your brand and shared user behavior across organizations which was a piece of the stickiness of the solution over these SaaS years). CRM is likely better suited then most of the other applications ironically due to their largley paned at the time acquisition of Slack. I don't think it provides immunity but a solution to cling to in bundled conversations where their numbers may slow slightly less fast then some of their contemporaries. Point solutions continue to be first in line, communications too. These businesses are not impaired to zero today, but their pricing and expansion (new logo and NRR) that is going to be continued to be eroded. Newspapers are still here, magazines too but their subscription based was drastically hollowed out. My view is the SaaSapocalypse was directionally correct and narrative largely holds, the markets in short term may have over run with that theme (some single digit true ebitda multiples) but thats on old business models and we have largely filled the entire gaps to where its attractive to take the outlook of where these businesss are likely to head in the coming years again. They will show amped AI revenues (as they rename and push anything named AI for the sake of all other revenue and rename, bundle to get to say "AI revenues up 80%"....but total ARR, NRR still continue to be flat to declining), they are pushing duration and discounts to achieve this as they themselves scramble with ai models and solutions and rush to make with large over promises, and leave clients with messy solutions that frequently break, have real security issues, and underwhelm the capabilities the sales team pitched (I listen to this daily from my wife whose a cs manager at a software company, and the majority of my friends who work in software in various capacities).
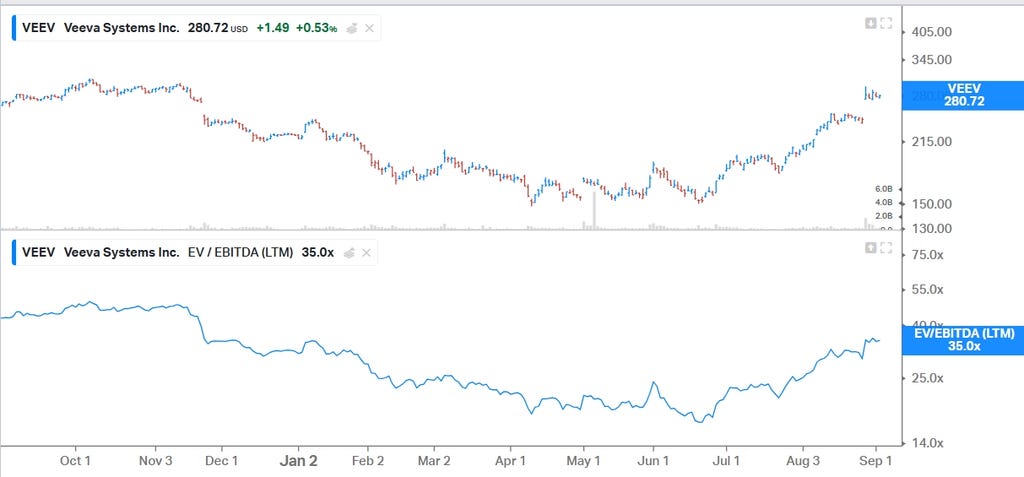
Veeva targets CRM share gains from Salesforce migration delays while Falcon agentic labor expands its reach into life-sciences safety,…
$SNOW conference call is the bear case for application software companies. Their data infrastructure combined with coco and cowork on top increasingly makes SNOW a key player in data migrations, and data consolidation for their customers and a key hub to switch between models means SNOW has a seat at the table to be one of the most important and internal pieces of an AI stack....and as they become the permissions data holder with governance and api/mpc to internal and external partners, they can actually become the system of record across applications. This would allow you to use tools like cocoa inside to contextualize in human language what you want built, or even what data/answers you want and how you want that visualized.... Compare this to a Salesforce that is essentially becoming a database company silo to their specific domain by opening up their data to Claude to be the work engine. Eventually companies will increasingly want to stop interfacing with multiple applications to query and want to UI and query across a singular interface (originally thought to be an LLM like Claude, but with specific training and different inference costs / intelligence across models its more like the player presiding over the biggest pool of company data (snowflake, databricks) could become that central payer - less model lock, more flexibly, and central access point for models, data, queries and ui across functions. May not relegate a salesforce obsolete but significantly destroys their value when people access from Snow or even from an LLM like Claude were they lose the ui interface, and behavioral association and slight shared/learned network effects and become a database. Increases switching costs overtime and certainly destroys pricing (agent force consumption model is a step in the modern pricing setup, but start based models are dead, its not an if for most applications without highly defensible and proprietary data) $PEGA, $APPN, $PATH, $CRM, $PAYC are first pass through som of the more exposed names
Salesforce’s Agentforce, Data 360 and Informatica adoption are positioned to monetize AI and accelerate its application business, despite…
 The Curious Analyst
@sigmazerocap I own a small position in $CRM (thankfully lower cost base), and no $META, so $CRM it is. Clicks results. Wow, guess CRM is going up another 25% next quarter. Love when everyone is positioned wrongly.

Salesforce trades at 14x trailing unlevered pretax free cash flow after Q2, with 10.8% revenue growth and unproven agentic AI adoption.
It takes courage to go against the current looking for opportunities that the market will not reward in the short-term. Times of turmoil is when we pay special attention to insiders and they led us to energy stock in mid-2020, regional banks in H1 2023, biotech companies in early 2025 and more recently SaaS stocks. While I don't have a position in $NOW, we did start positions in $CRM, $NAVN (partially exited) and more. Here is some of what I wrote about that decision to double down on SaaS in our July 2026 newsletter:
 CRM 2026-08-28
Salesforce's Anthropic alliance and Claudeforce launch drove a 22% post-Q2 2027 rally, while nonexclusive access and AI infrastructure…
 Elina Selianska 4 clicks
Not only are $IGV and $SOXX both green today, but $IGV just flipped positive YTD, led higher by $CRM up 20%, and cybersecurity names ripping after $CRWD and $OKTA Software and Semis are friends again https://t.co/pYgkP9Rtsw
$CRM geez the bar must of been very low...raised guidance by .02% for the year organic. And Operating income ex the non strategic investment gain actually declined yoy. Slack is going well, and has been recently but what about the rest of the company? Still with slack momentum still at 14% rpo
It is good to see the market recognizing that some of these SaaS companies like $ADBE, $NAVN, $ADSK and $CRM were oversold. My updated list of 62 software companies with insider buying can be found here in a tool that was built using Claude: https://t.co/ov9dxXgBid Here is some of what I wrote about the data in our July mid-month update a couple of week ago: "Industries in crisis provide fantastic opportunities if you are willing to wait patiently for some of the dust to settle and don’t mind temporary drawdowns as it is nearly impossible to pick bottoms. Earlier this year I started compiling a list of software and software-adjacent companies that were seeing insider buying after a massive drop in the price of their stock. I covered why this was important and included a list of 11 companies with insider buying in my article Where Are The Software Insiders? in February. Software-adjacent Companies What do I mean by “software-adjacent” companies? These are companies that have also seen their stock prices decline because of the perceived threat of AI to their business models. The list includes data providers like S&P Global $SPGI, MSCI $MSCI, and Morningstar $MORN. It includes e-commerce marketplaces like ThredUp $TDUP as well as the Latin America focused juggernaut MercadoLibre $MELI. It includes FinTech companies like SoFi $SOFI, PicS $PICS, PagSeguro Digital $PAGS, and StoneCo $STNE. I also decided to include cybersecurity companies like Palo Alto Networks $PANW and Gen Digital $GEN. Sixty Two Companies With Insider Buying The full list included 72 companies but I decided to get rid of five with a market cap below $500 million and another five whose gross margin was below 40%. The insider data is clean as a whistle because I reviewed every filing, read the footnotes and even adjusted the price of one purchase (Marqeta) to account for a reverse split. The buyback data specified in the Double Dipper column should also be good as I did several spot checks against 10Q and 10K filings. The rest of the data including valuation ratios and company metrics come from our data provider (FMP) and could have some issues. Several of these companies are foreign issuers (EPS reported in Brazilian reals but price reported in U.S. dollars), some went public within the last year and some ratios will be impacted by one-time items or growth from a tiny base. We have covered 18 of these companies in InsideArbitrage articles or newsletters"
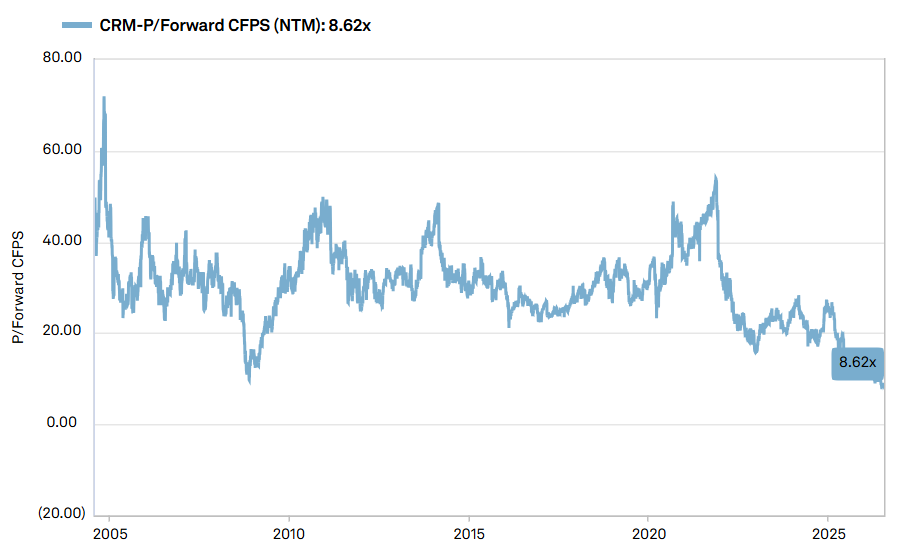
Salesforce's 8.62x forward cash flow valuation discounts AI seat cannibalization, while Agentforce, Data 360 and MuleSoft aim to retain…
Almost a 40% spread opened up since the beginning of June (3 weeks ago!) between $MSFT and $SOXX Nearly 60% on $CRM and $SOXX... Buckle up
The AI disruptions no one seems to be talking about, ytd stock performances $TTD -54% $IT -53% $HUBS -35% $ACN -32% $TEAM -31% $CRM -28% $ADBE -23% $NOW -18% $WDAY -14%
Letters that discuss CRM.
Companies the stories above are also about, besides CRM.


