NASDAQ

Asml Holding NV

ASML

15 stories

$575B Market cap · 2026-11-04

Get ASML news in Claude, ChatGPT or your own code. See plans

@convequity

Convequity on X

Compute & Accelerators screen (43 names). Our Rule of X = forward growth x a sector coefficient + free cash flow margin - SBC %. The coefficient starts from Bessemer’s 2.3 for software and is scaled by how much profit a sector earns per $ of growth versus its cost of capital. More profit and cheaper capital means growth counts for more. Compute mostly runs 2.3 to 2.7. Colours: green = high score, cheap, or price down (more upside from here). High score + attractive valuation + flat or falling price: $NVDA (DCF 91% discount), $AVGO (94%), $ASML (EV/FCF 24.8x). High score but priced for it: $AEHR (EV/GP 95x), $AMD (EV/FCF 125x). Data from Koyfin, prices at 30 Oct close. A screen, not advice. Do your own research.

Deep Dive: $ASML

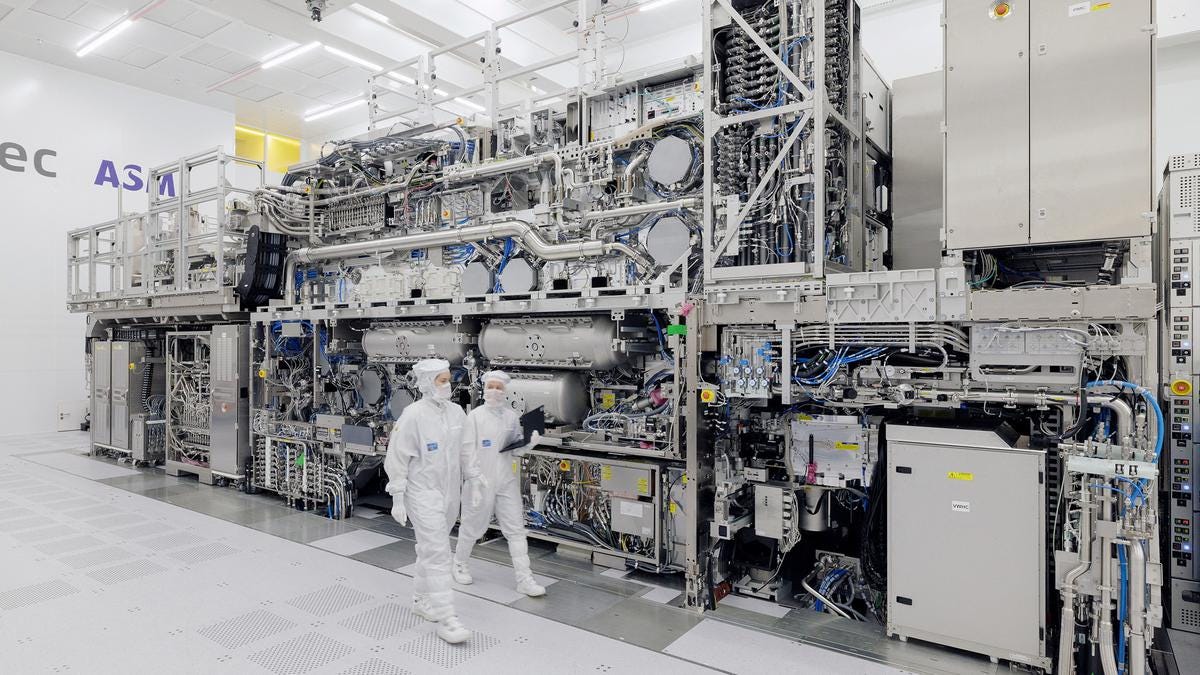
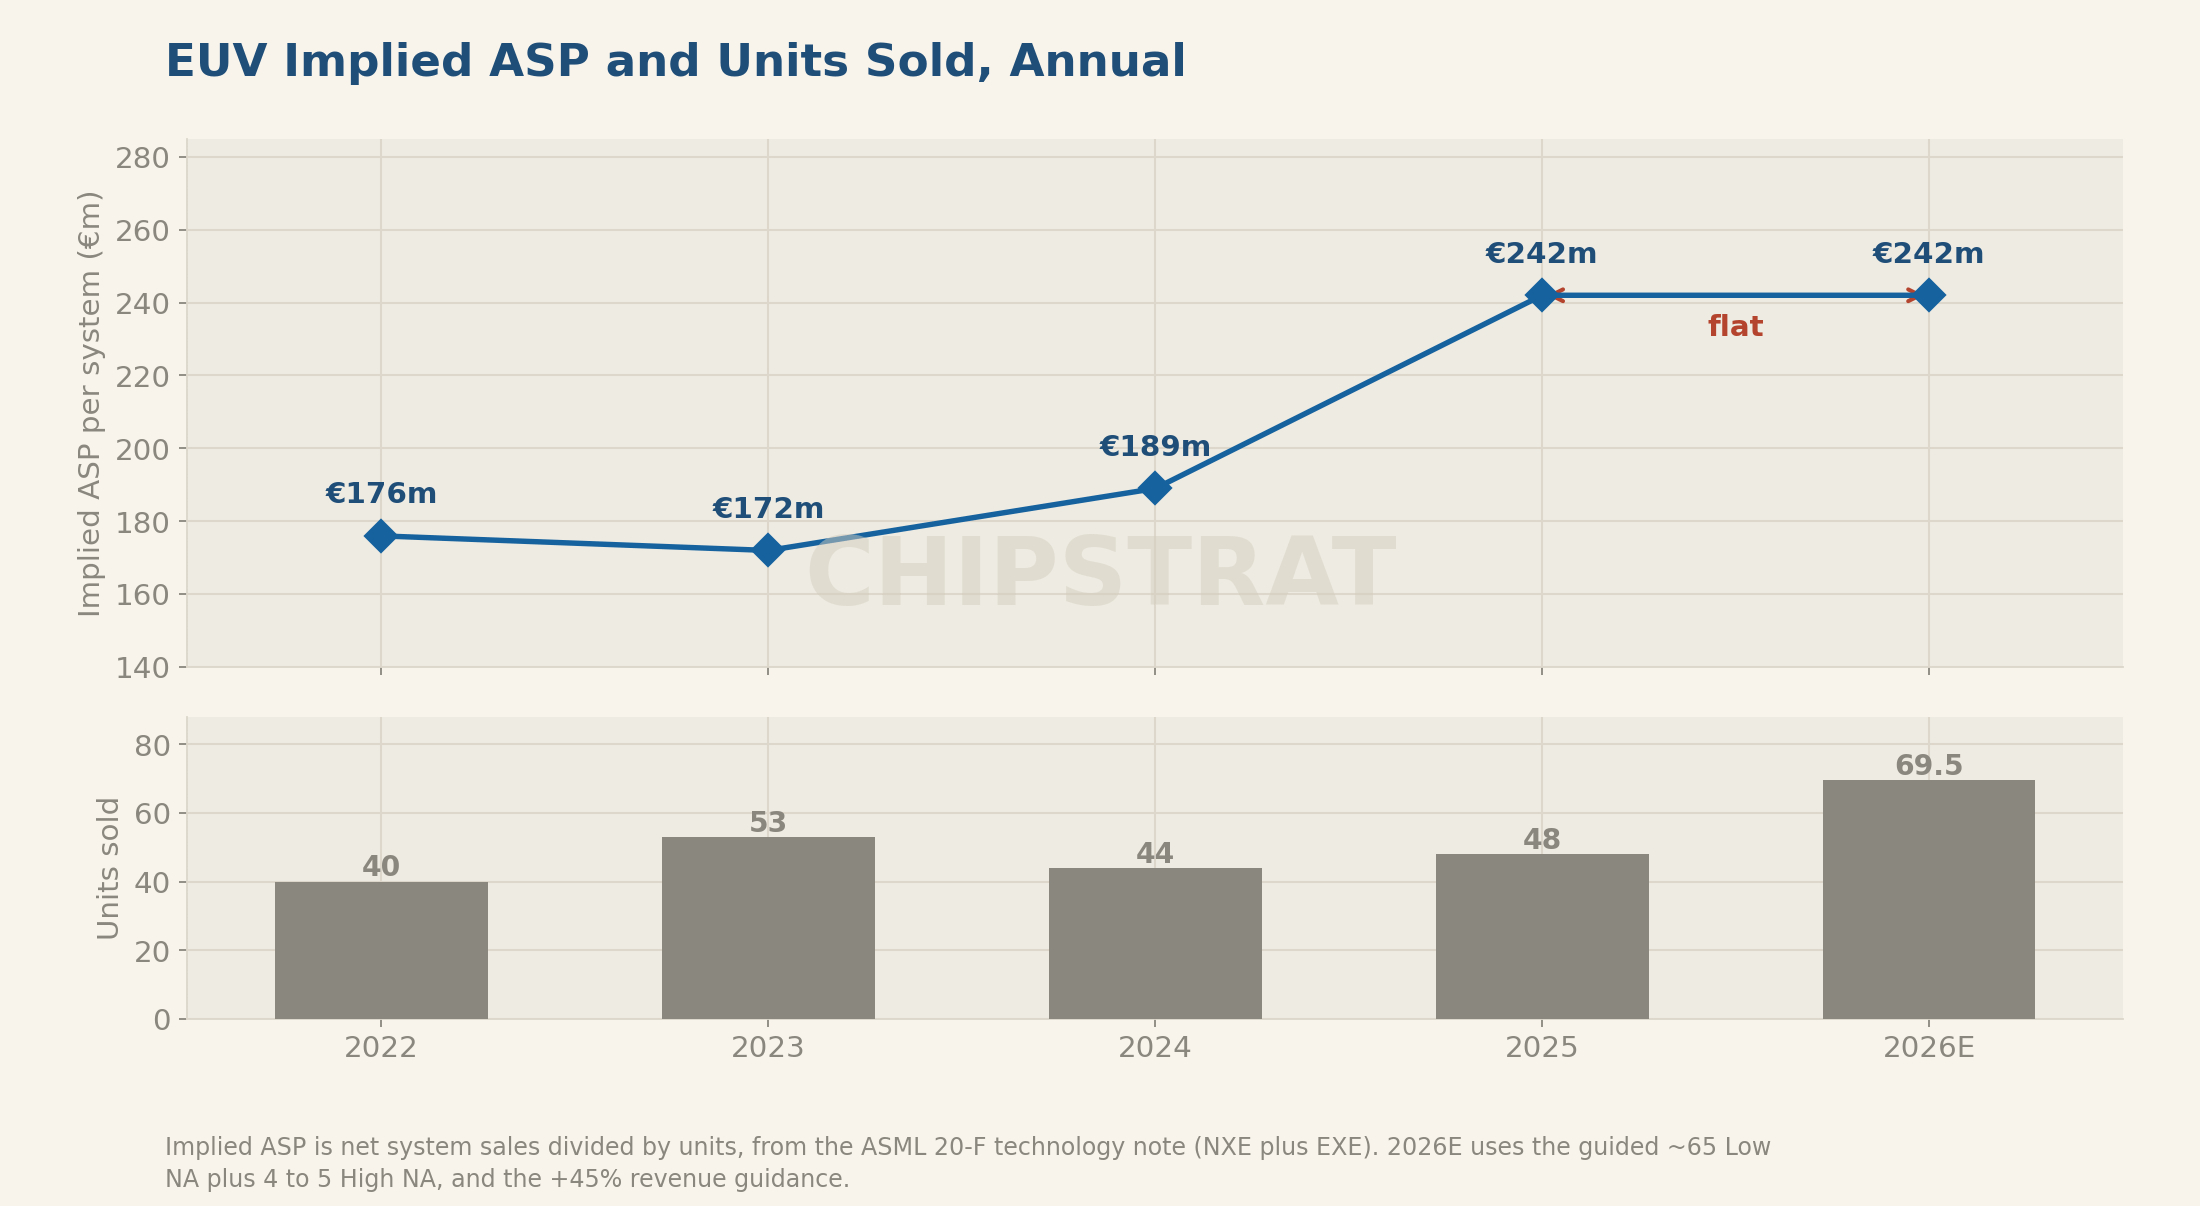
ASML’s €230 million EUV machines underpin advanced AI chip production, with demand booked through 2028 after nearly $9 billion and two…

My 2028 numbers

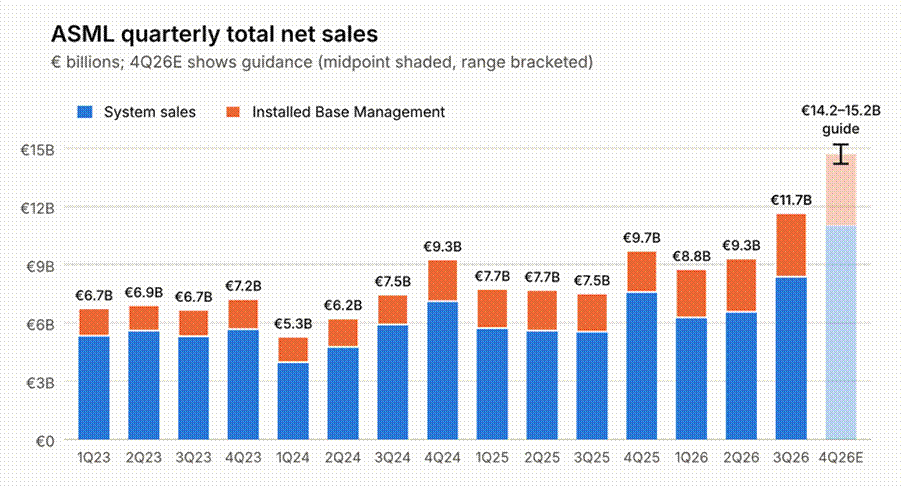
ASML’s €11.7 billion quarter benefited from €3.3 billion in installed-base sales and operating leverage, while the MATCH Act threatens…

ASML Q3 FY12/26 Earnings Review

ASML reported Q3 sales of €11.7 billion, up 55% year over year, and guided Q4 sales to €14.2 billion to €15.2 billion amid capacity…

@aleabitoreddit

Serenity on X

So update from $LITE + Win Semi ( $SIVE ) foundry: Lumentum in a meeting with Stifel at ECOC 2026 stated: - $NVDA Spectrum-6 CPO UHP demands increased materially. - NPO as larger than CPO, with multi-wavelength external lasers lifting ASPs (Sivers offers multi wave length DFB arrays, read through on higher valued products) - Demand for UHP lasers continues to exceed supply Just a status update in terms of how the optical bottleneck is going (laser prices going up, demand exceeds supply). Digitimes also reported today Win Semi ( $SIVE foundry ) was expanding capacity for CW lasers. - "CW products... are expected to gradually emerge in the second half of 2026", with meaningful revenue contribution likely coming in 2027 and 2028. - Win has strengthened inventory management for InP substrates while moving toward 6-in InP wafers for ongoing process testing. Currently relies on Tier-1 International suppliers. - Many of this was spent on DUV tools from $ASML but (Win Semi's orders spanned machinery, equipment, and fab engineering work) So that answers a lot of questions about Sivers' partner "how is this company securing InP substrates", "4in vs 6in", "production timing" TLDR: - NPO > CPO (per Lite), multi-wavelength lasers going brrr for prices - demand > supply (continuation) - Not sure why people have been bear posting Win Semi when turns out they have everything needed to mass produce CW lasers.
@RagingVentures 1 click

Raging Capital Ventures on X

I agree there are differences in HBM vs. NAND. I said we are “around” the peak of the cycle, with $SNDK much more at risk. Memory is an intensely cyclical business with a long history of booms and busts. Cyclical peaks are typically associated with double and triple+ ordering, as we are seeing today. Paybacks on new capacity are 1 year or less; capacity will come. $ASML is the primary limiter of capacity growth for DRAM/HBM, which is bullish for limiting supply growth in those markets. NAND is far less defensible. Memory is the biggest pain point in the ecosystem today and many entrepreneurs and engineers are intensively focused on solving this problem with innovation and other adjustments. De-speccing is already commonplace and memory pooling is coming. Finally, I am not saying it is time to short these stocks (although I am short some $SNDK). What I am saying is it is very poor capital allocation for $MU, $SNDK, etc. to be buying back stock at these multiples of invested capital.

Investor Letters

Letters that discuss ASML.

Every letter that discusses ASML

Tickers on this page

Companies the stories above are also about, besides ASML.