Bloom Energy’s fuel cells offer data centers grid independence as Q3 operating income rose 518% on 138% revenue growth.
SA Ignacio Planas Gonzalez 11h ago 2 clicks QXO's Q3 sales rose 79% to $4.9 billion after TopBuild and Kodiak acquisitions, while acquisition debt lifted interest expense to $163…
S SixSigmaCapital: Navigating the Financial Markets 13h ago 2 clicks
Nvidia CEO Colette Kress signals a pullback from the financial schemes pursued under Jensen Huang.
BL The Technology Letter 16h ago
NVIDIA faces DOJ antitrust probes alongside inquiries into Megaspeed and Super Micro, after charges over $2.5 billion of GPUs allegedly…
S Cassandra Unchained 19h ago 4 clicks
Salesforce’s Agentforce adoption, Anthropic and Databricks stakes, and margin expansion support upside, while debt-funded buybacks have…
SA Alexander Grover 24h ago 1 click Quanta Services' backlog rose 63% year over year to $64 billion as shares fell 30%, with AI and power-infrastructure demand driving revenue…
S Monte Independent Investment Research 24h ago 5 clicks
A hypothetical Nvidia succession scenario names Colette Kress interim CEO and favors Arm's Rene Haas or Nvidia's Ian Buck as permanent…
S Key Context by Tae Kim 24h ago 4 clicks
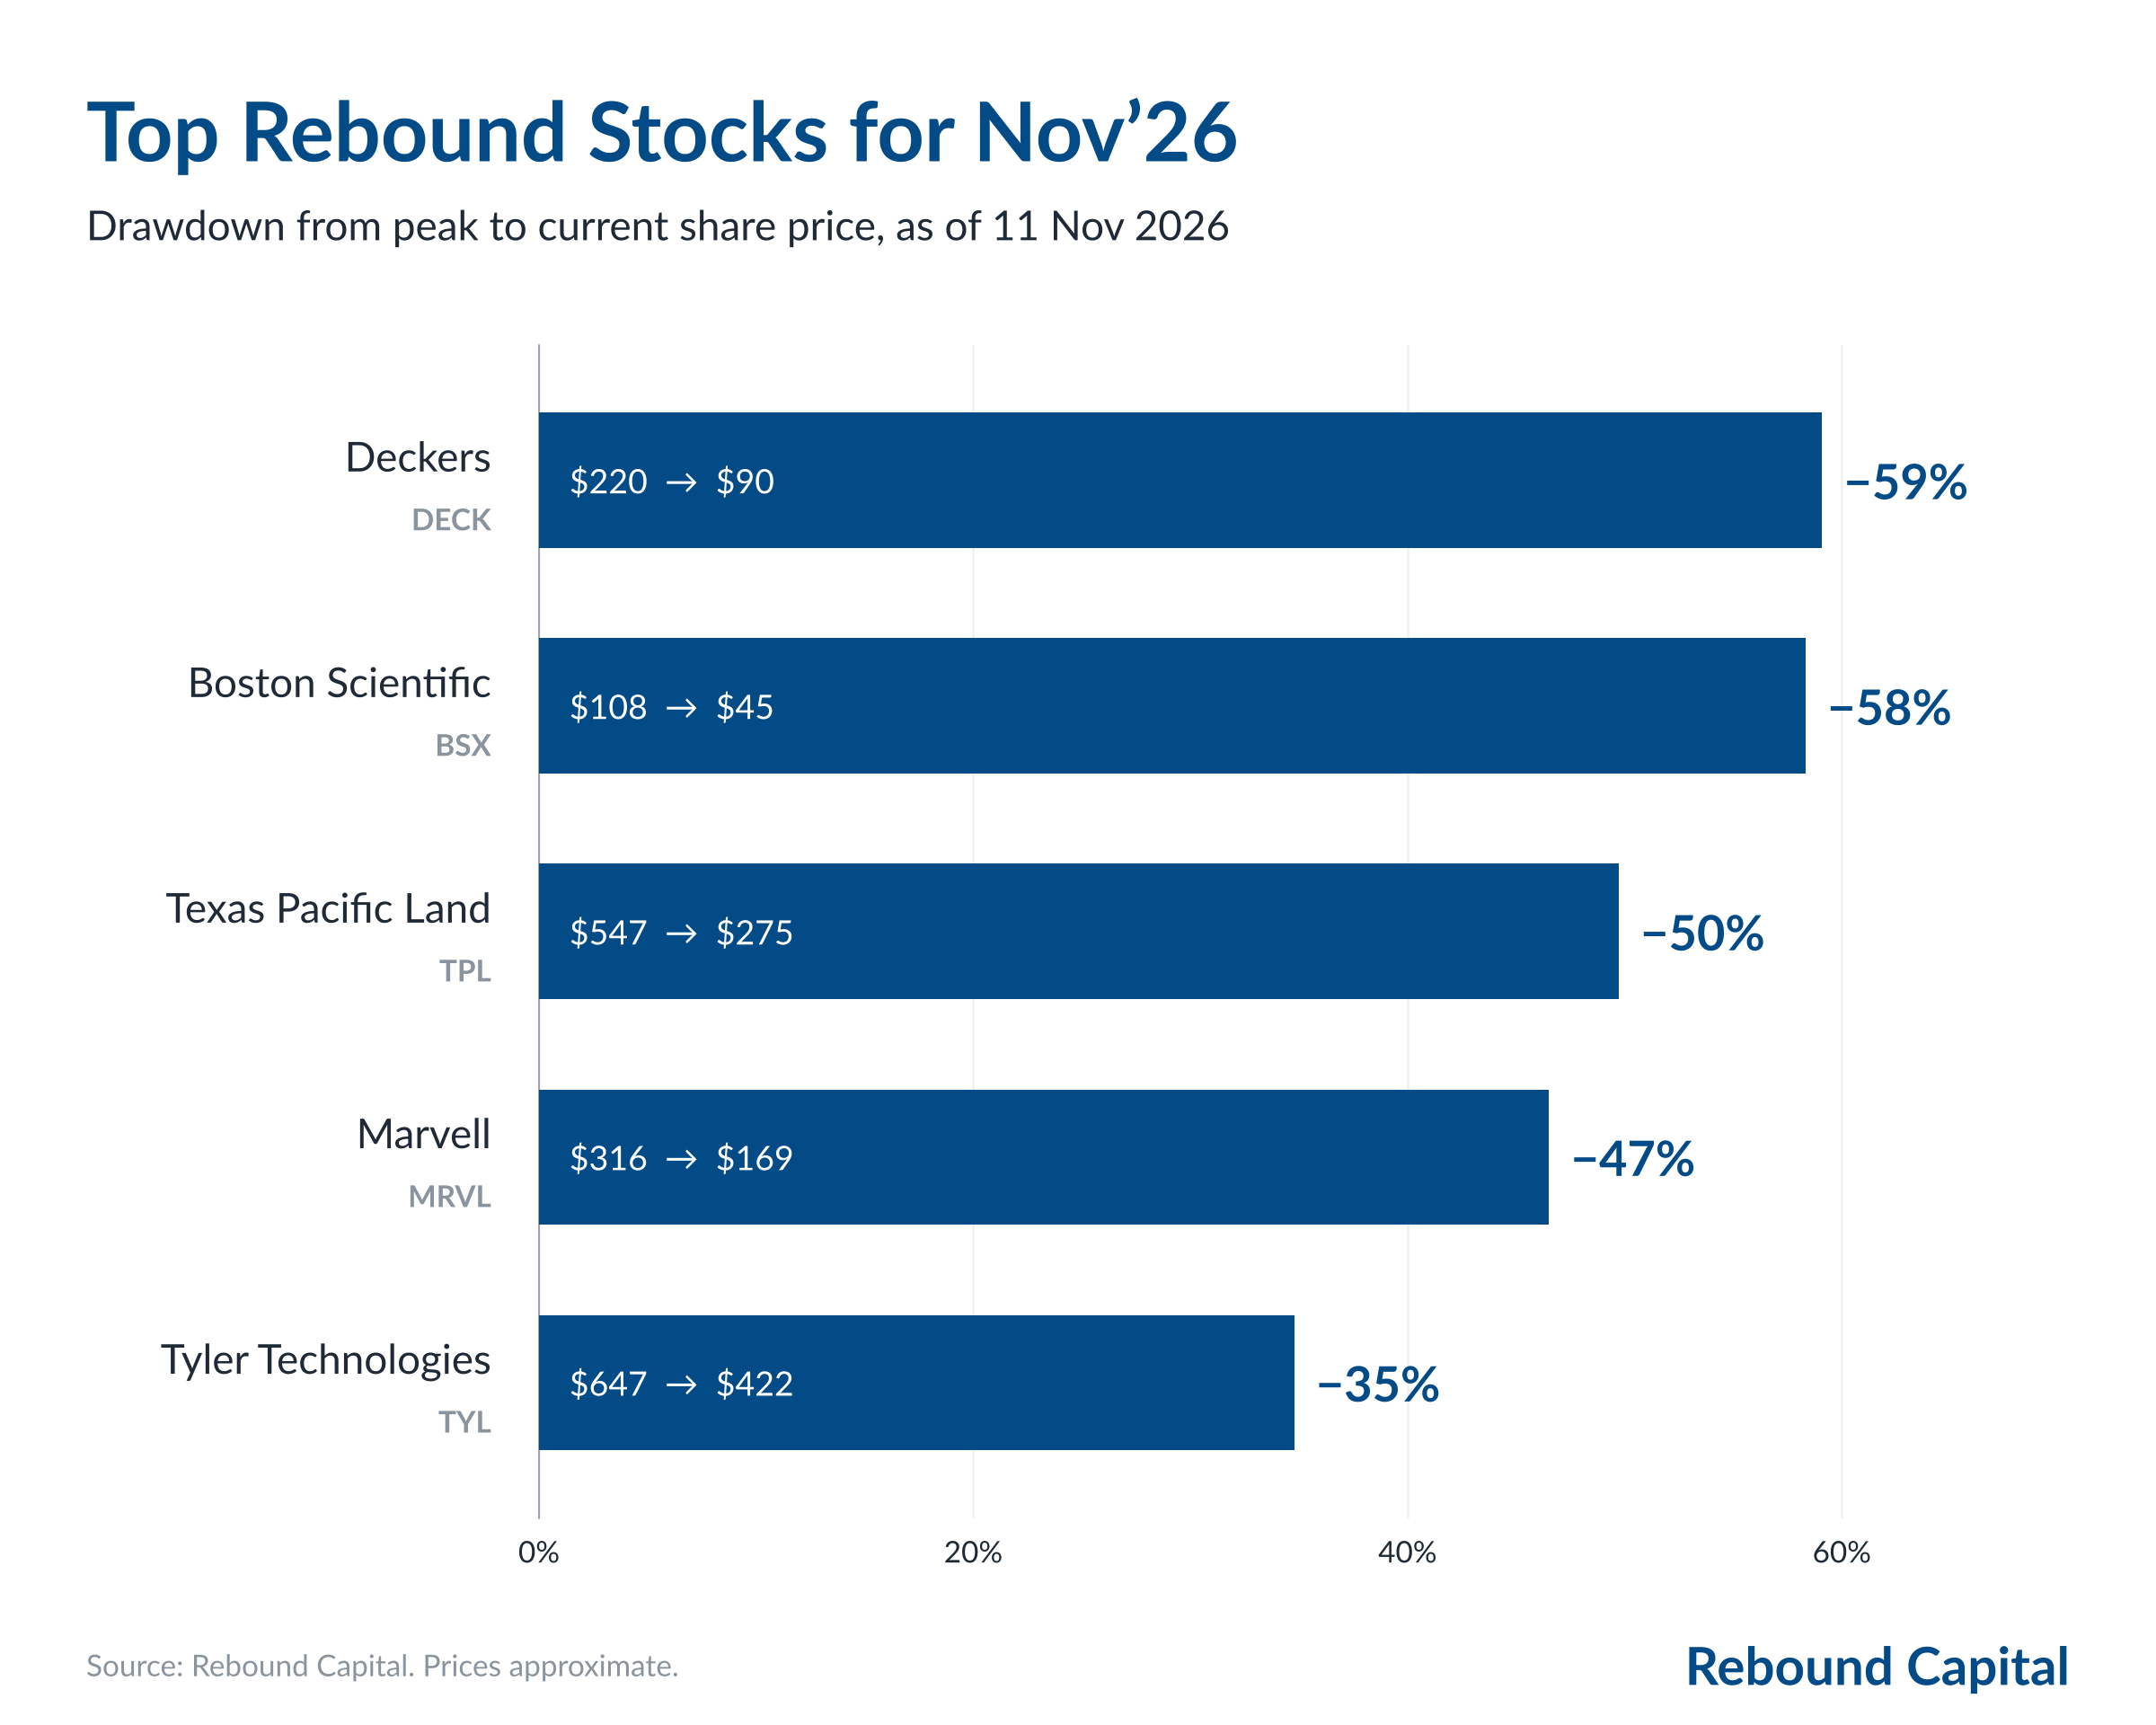
Texas Pacific Land's 50% selloff reflects faded data-center expectations, while its Permian royalty business generated $498 million of 2025…
S Rebound Capital 26h ago 2 clicks
Medtronic’s Affera, PulseSelect and Symplicity Spyral platforms expand cardiac and hypertension procedures, while Hugo and Stealth AXiS…
SA Crosslight Partners 32h ago Roblox CEO David Baszucki says AI can make game creation accessible to anyone, expanding Roblox’s role in discovery, cross-platform play…
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 40h ago 2 clicks
Marvell’s all-stock acquisition of Lumentum targets optical supply, DSP synergies and AI data-center demand, while adding fab integration,…
S P Equity Research 44h ago 3 clicks
Hewlett Packard Enterprise offers lower valuation and better memory-price downside protection than Dell, backed by higher-margin…
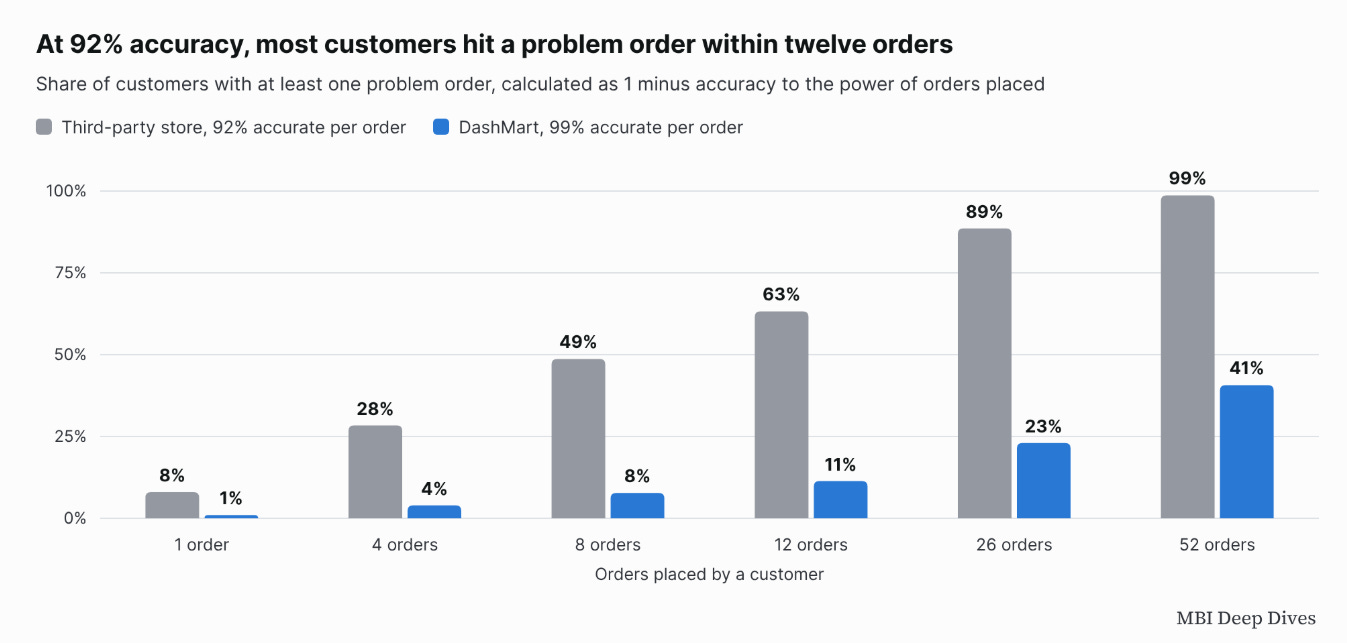
SA Benjamin C. Barry 45h ago 4 clicks DoorDash’s $17 billion Instacart deal targets DashMart warehouse scale, where 99%+ order accuracy and faster delivery address the limits of…
S MBI Deep Dives 47h ago 3 clicks
An unnamed healthcare company became the portfolio’s largest position at 8%, with a $130 target implying 195% upside despite broken…
S Guardian Research Nov 11 6 clicks
FICO is licensing mortgage scores directly to resellers, seeking pricing control as VantageScore competition and regulatory scrutiny…
S scuttleblurb Nov 11 5 clicks
Adobe's compressed 10x non-GAAP EPS multiple reflects AI monetization and ARR-growth concerns; cash-secured puts at $210 or $200 target a…
SA Tim Travis Nov 11 4 clicks Sea Ltd reported Q3 2026 revenue of $8.6 billion, up 43.4% year over year, while net income rose 34.0%.
S SixSigmaCapital: Navigating the Financial Markets Nov 10 7 clicks
CoreWeave reported 168% revenue growth to $3.66 billion, but $20.4 billion of trailing free cash outflow and $42.7 billion in net debt keep…
BL Cestrian Capital Research Nov 10 4 clicks
Constellation Software’s 3Q26 organic revenue grew 2%, while $609 million of acquisitions and improving acquired-business margins supported…
BL Speedwell Research Nov 10 2 clicks
CoreWeave's Q3 report leaves its data-center business looking structurally unattractive despite major changes since the prior earnings…
BL The Technology Letter Nov 10 3 clicks