Consumer agents: an ethics race, a prisoner’s dilemma, and the obvious OTA short
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
NASDAQ
BKNG
13 stories
$117B Market cap · 2026-10-23
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
$BKNG discourse regarding agents: If the interface to book changes, OTAs lose. Boutique hotels don't need to be tech savvy. They will run some white label SaaS product that interfaces with agents and handles booking. OTAs are bad for society. Huge take rates (20%+) due to rent seeking. No real innovation / value add to society. Disruption here is good. Disruption will be slow because I imagine bkng contracts will stifle adoption and agent usage is still nothing and won't be anything material for at least a decade. If bkng trades at 30 p/e, it would be an easy short. But today's valuation isn't too demanding. But still tempting to short.
mentioned: $SCHW $LPLA $RJF $AMP $JPM $BAC $BKNG Meta’s Muse Comes for Financial Stocks https://t.co/dqxVL8KJ2U
@JerryCap Of course. Although I would think you'd like $BKNG and their mngmt as well.
@JerryCap 1) ASML, Hyperscalers (GOOGL, AMZN?) 2) $FOUR, $GPN, $BKNG? 3) $CSU
Booking Holdings trades at 19x earnings, its lowest since 2022, after a 20% annual decline, with the thesis resting on durable online…
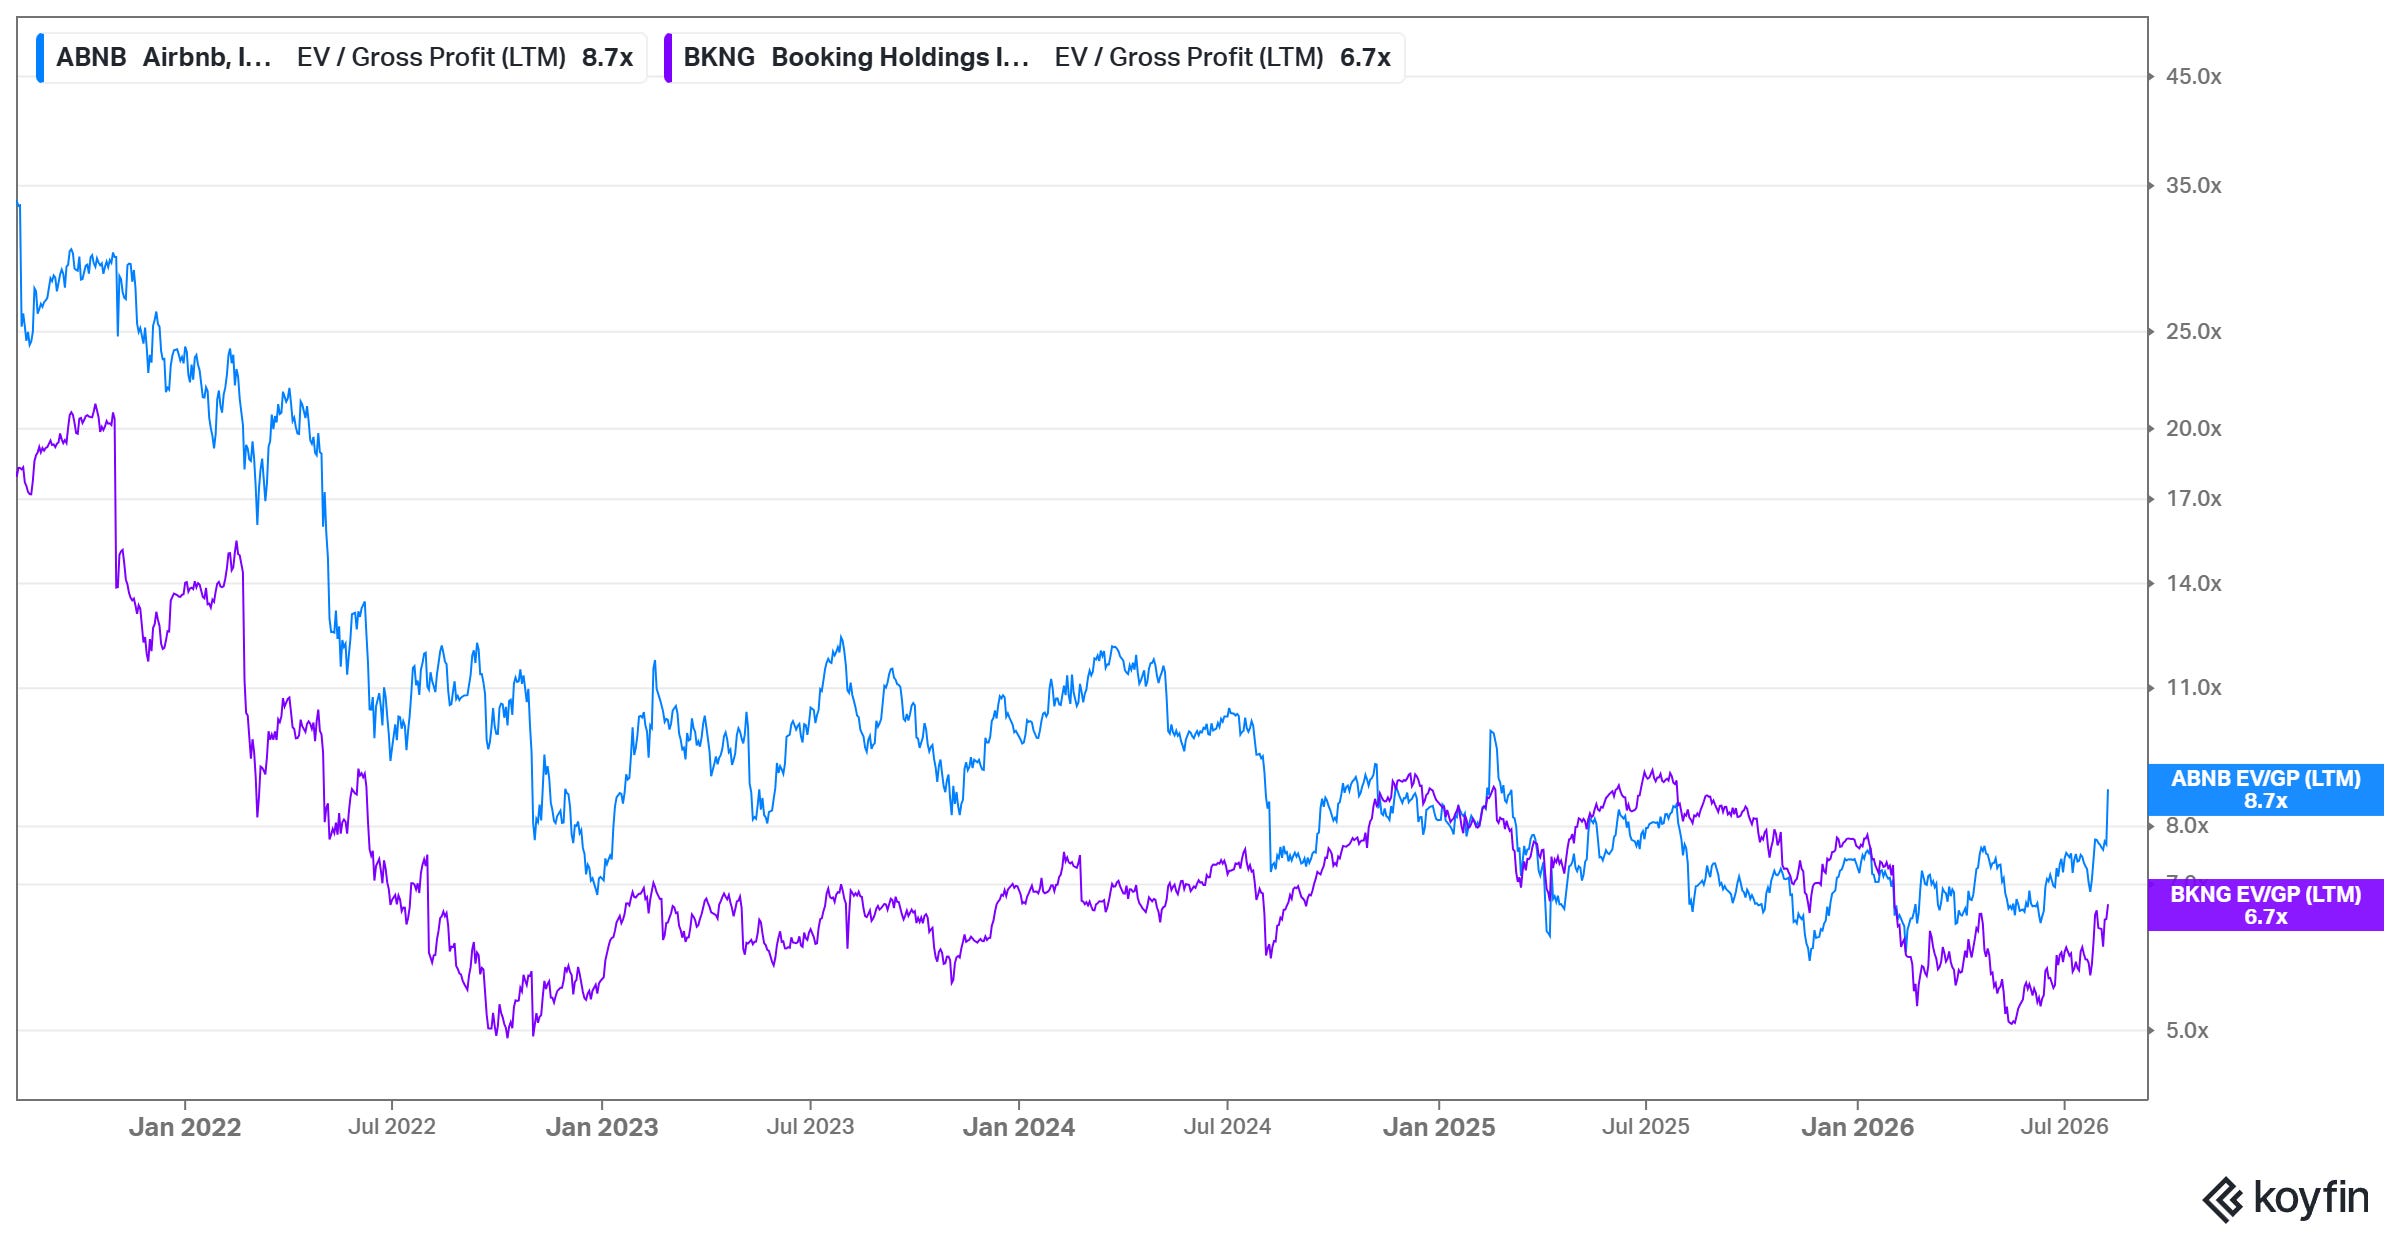
Airbnb added 14 million booked nights and seats, up 10%, and guided low-double-digit third-quarter growth as North America and EMEA…
Booking Holdings beat Q2 guidance as room nights grew 5%; connected trips, merchant payments and Genius loyalty strengthened direct…
Remember the good ole days when covering internet meant you just needed to have a view on: - If $GOOGL Search was going to accelerate or decelerate and what the opex was likely to be - $META fxn ad revs...how big a beat? Opex? - $NFLX are they going to beat on subs? - $AMZN AWS to accelerate? How much? Margins? EBIT guide? - $BKNG room nights ! I started my career covering these companies and a bunch of other internets....at that time capex was not something we cared about bc it didn't matter. It was a simpler time.
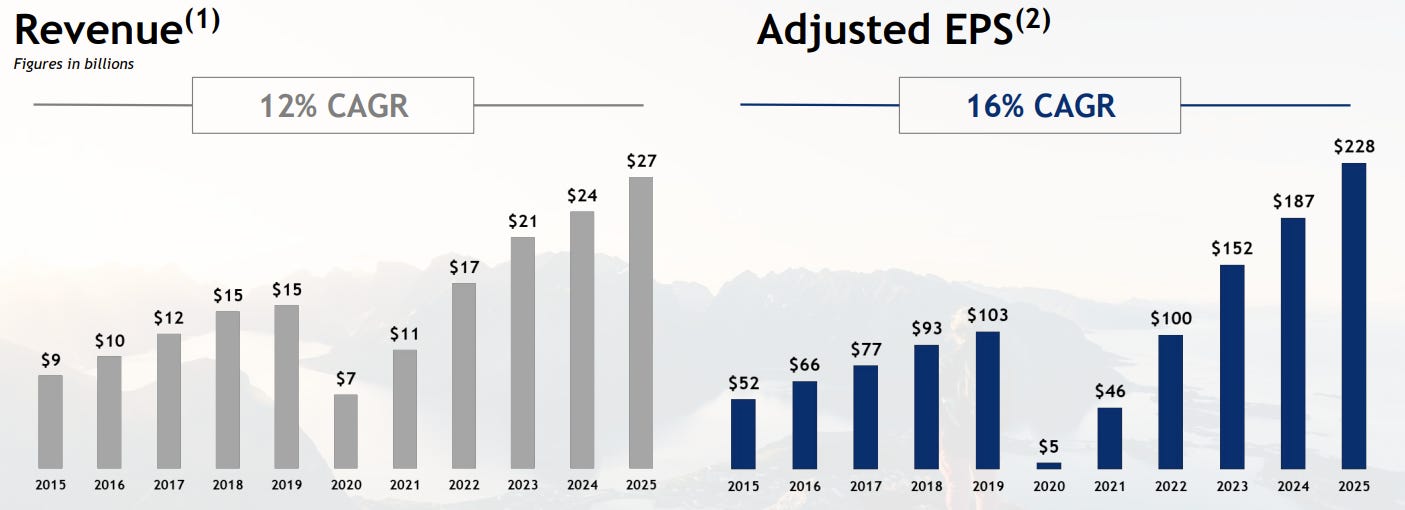
Booking Holdings generated $9.1 billion in 2025 free cash flow and targets 15% annual EPS growth, trading at 16.8x forward 2026 earnings.
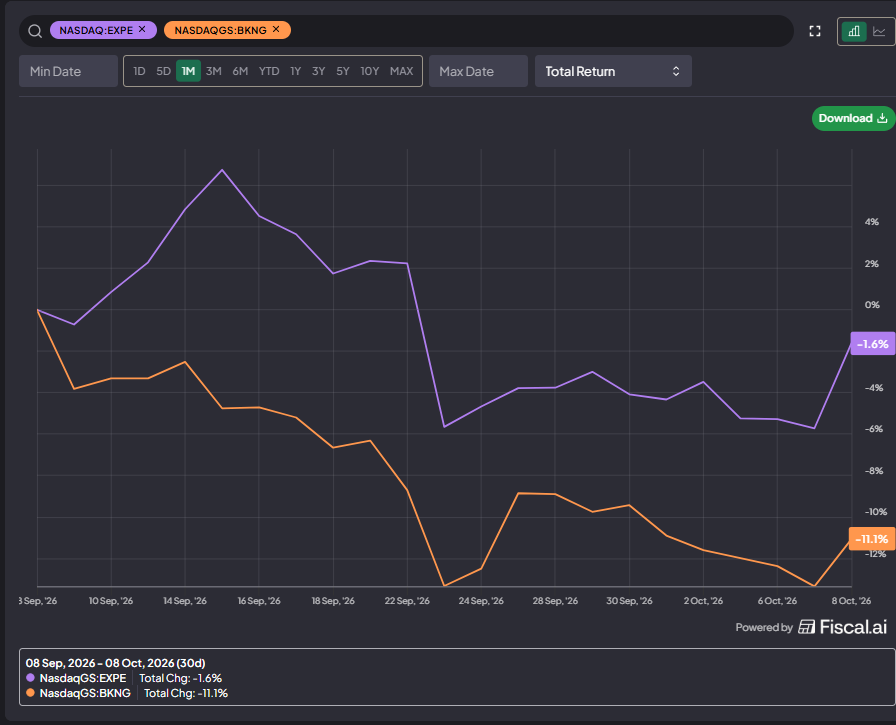
$BKNG vs $EXPE https://t.co/zzuhmvsl0k
"Rally of the 2nd Tier": the runner-up is running the show over 6m/3m/1m time periods: • Silver > Gold ( $SLV > $GLD) • ETH > BTC • Small caps > S&P 500 ( $IWM > $SPY) Seeing it occur even in individual stock levels: • $AMD > $NVDA • $EXPE > $BKNG • $LYFT > $UBER What it implies: That breadth + beta has been improving, perhaps in anticipation of rate cuts and overall healthier economy than anticipated. Likely keeps the bull run going for now. Charts below
$EXPE has always been a much slower grower than $BKNG, won't be surprised if it's a fav pair trade of hedge fund (long booking, short expe). Over the years though Expedia has been going through internal changes, sold some businesses (Egencia to AmEx travel and few other sites), went through a technology transformation for internal sites (Expedia, https://t.co/ap3OIandej, Vrbo). 50% improvement in operating margin since 2019. But not as profitable as Booking (operating margin at 12% vs 32% for bkng). Mainly a US focused player (unlike bkng) with a very strong B2B segment that's growing mid teens and about 30% of total revenue), now looking to expand internationally. To be seen if that would drive higher margin given the much fragmented hotel market internationally vs US. Bkng on the other hand seeing revenue growth slowing down to high single digit and mid teens eps growth with margins declining since 2019. Expedia needs to show higher top line growth but possible still delivers mid teens eps growth. Travel is cyclical but these OTA are very robust, they saw revenue growth even in the financial crisis, as more ppl look for deals. AI is an unknown, Expedia is embracing it. Finding a hotel with the right deal is not same as getting an answer to a question from LLM, distribution/platform should remain valuable. Interesting to see how the pieces fall for Expedia, PEG < 1 and these multiples should atleast provide downside protection
Letters that discuss BKNG.
Companies the stories above are also about, besides BKNG.