Adobe's compressed 10x non-GAAP EPS multiple reflects AI monetization and ARR-growth concerns; cash-secured puts at $210 or $200 target a…
SA Tim Travis 9h ago 1 click Sea Ltd reported Q3 2026 revenue of $8.6 billion, up 43.4% year over year, while net income rose 34.0%.
S SixSigmaCapital: Navigating the Financial Markets 14h ago 4 clicks
CoreWeave reported 168% revenue growth to $3.66 billion, but $20.4 billion of trailing free cash outflow and $42.7 billion in net debt keep…
BL Cestrian Capital Research 14h ago 3 clicks
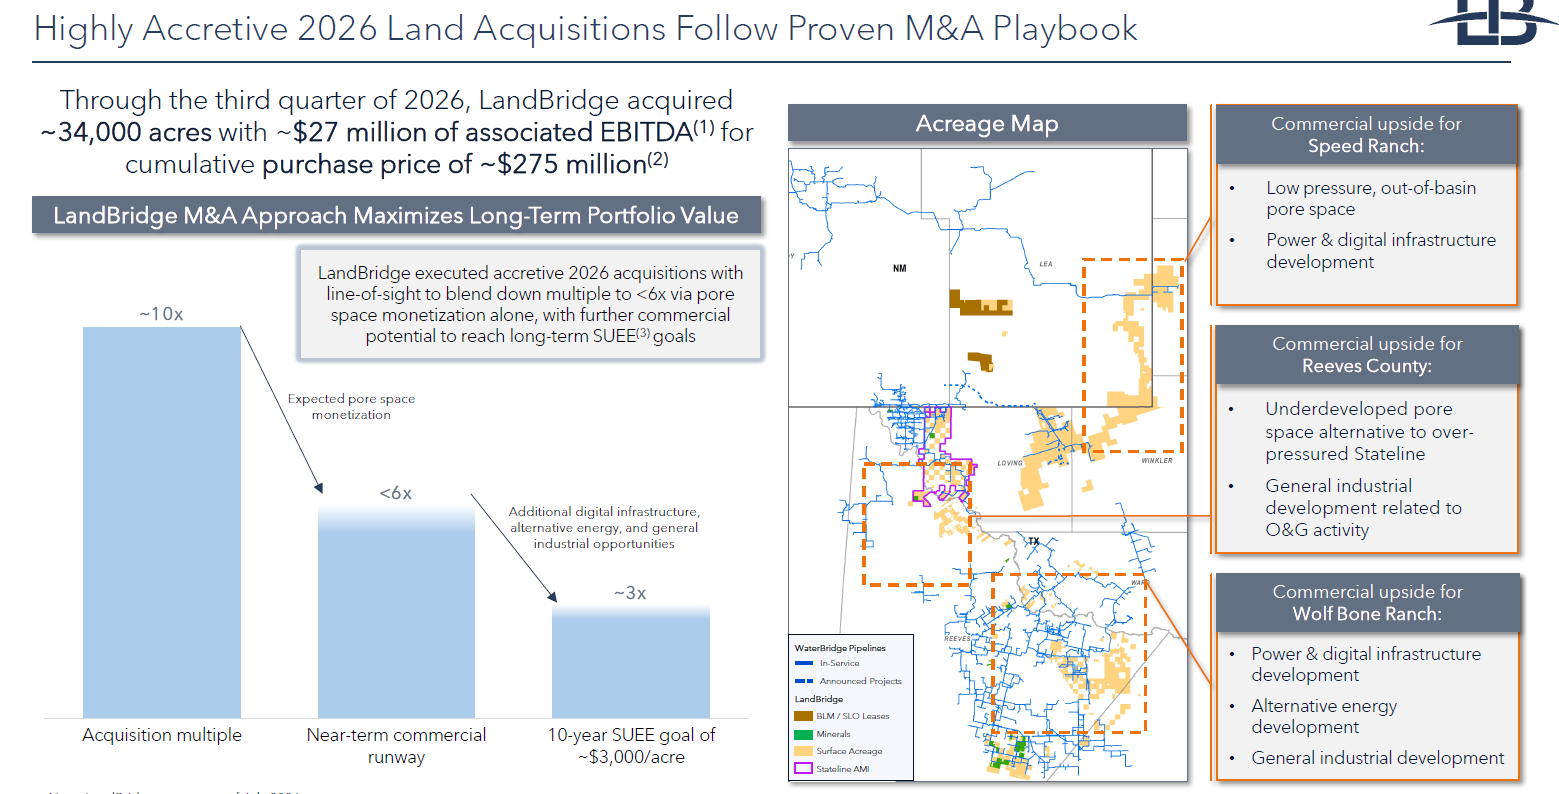
LandBridge’s Q3 revenue rose 39%, while newly acquired pore space could lift pro forma EBITDA and cut its 2027 EV/EBITDA multiple from…
S 310 Value’s Newsletter 15h ago 1 click
Constellation Software’s 3Q26 organic revenue grew 2%, while $609 million of acquisitions and improving acquired-business margins supported…
BL Speedwell Research 15h ago 1 click
CoreWeave's Q3 report leaves its data-center business looking structurally unattractive despite major changes since the prior earnings…
BL The Technology Letter 16h ago
Intel and AMD’s diverging earnings reflect longstanding strategic differences and raise the case for Intel returning to an earlier model.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 16h ago 1 click
Airbnb’s 3Q26 revenue rose 19% to $4.9 billion as nights and seats grew 16%, with app bookings up 29% and Reserve Now Pay Later adding…
S Speedwell Memos 20h ago 2 clicks
Joby Aviation reported $55.1 million in Q3 revenue, raised 2026 guidance to $135 million to $140 million, and expects FAA pilot training in…
BL Cestrian Capital Research 20h ago 2 clicks
Airbnb’s 3Q26 revenue rose 19% to $4.9 billion as nights grew 16%; app rebuild, AI-assisted releases and social travel features aim to…
BL Speedwell Research 20h ago 2 clicks
OSW · short OneSpaWorld (OSW) faces about 37% downside as its valuation requires unattainable growth in average revenue per customer after major-market…
BL Value Investors Club Aug 13
SA Louis Gerard 12h ago Nvidia faces unverified allegations involving CEO Jensen Huang, a customer executive and claimed China-linked influence over AI chip…
S Kakashii's Materials 23h ago 3 clicks
S&P Global research will assess Platts, Kensho and ratings growth; Benefit Systems’ 72% YTD rally changed its valuation, while Netflix and…
S Global Outperformers 24h ago 3 clicks
Occidental Petroleum generated $4.3 billion of Q3 EBITDA and cut principal debt to $10 billion, but each $1 WTI decline reduces annual…
BL Cestrian Capital Research 25h ago 2 clicks
Rocket Lab reported Q3 revenue up 73% to $267.8 million and backlog up 52% to $3.57 billion, but Neutron’s first flight slipped to 2027 and…
BL Cestrian Capital Research 26h ago 2 clicks
Vir Biotechnology’s hepatitis delta therapy posted 44% primary endpoint success in Phase 3, alongside a new Gilead partnership and $991.3…
SA Cypriot Invests 27h ago 1 click AutoNation shed rentals and megastores, focused on dealerships, and retired 91.1% of its shares through buybacks after its 1990s roll-up…
S Cannibal Stocks 28h ago 3 clicks
Celestica trades at 9.6 times projected 2027 adjusted EPS after an 83% Q3 revenue gain, while lower free cash flow guidance reflects growth…
SA Ryan Canady 28h ago 2 clicks Quanta Services’ backlog rose 63% year over year to $64 billion as shares fell 30%, while AI power and data-center construction demand…
S Monte Independent Investment Research 28h ago 2 clicks