NASDAQ

Advanced Micro Devices INC

AMD

38 stories

$925B Market cap · 2026-10-29

@aleabitoreddit

Serenity on X

Following the Lumentum / Marvell deal: My opinion is that independent Western laser players, like $AAOI, $COHR, and $SIVE became a lot more strategically valuable. $MTSI and $SMTC should get some attention too as emerging laser players in 2027. If I had to guess: 1. Companies competing against Marvell, or not in the $NVDA ecosystem bandwagon, such as $AMD, are likely going to rethink their relationship with $LITE. If getting bottlenecked by Nvidia capacity agreements wasn't enough... Incentives around qualifying + bringing up other laser players, seems very necessary now. Since you generally don't want competitors like Marvell to have influence or visibility over your roadmaps, IP, capacity, pricing, etc. even if there is a "firewall". 2. $MRVL acquiring Lumentum opened pandoras box in a way of acquiring a critical chokepoint all your competitors + buyers use. $LITE was used by your major hyperscalers and across AI supply chains. Now, your leaders might wonder if weaponizing capacity agreements might not be as effective.... If someone else can just buy the entire company. There's only a few major public merchant Western players out there, and I'm also sure many others will want to follow the Marvell / Broadcom route via vertical integration, given I think $MRVL saves around $1B+ in costs/year. So M&A premiums likely went up. $SMTC was actively looking to buy laser capacity via M&A so I'm sure they're looking at $SIVE given their 100M CW DFB laser expansion + tiny MC. $JBL also probably wants to vertically integrate down the road too so $SIVE is also an acquisition target for their 1.6T program. $AMD was looking for ELSFP + CW capacity given Nvidia bottlenecks, so I'm sure they've looked at $AAOI. can go on and on about other ASIC players (like in Taiwan) that likely are looking at vertical integration too. Since multiple players use a small subset of laser suppliers, if competitors just go ahead and buys them... There's a lot pressure to M&A for their own supply chain defensibility. TLDR: Independent laser suppliers should capture a material strategic revaluation since $MRVL + $LITE, sets a new precedent + implications. We'll see what happens.
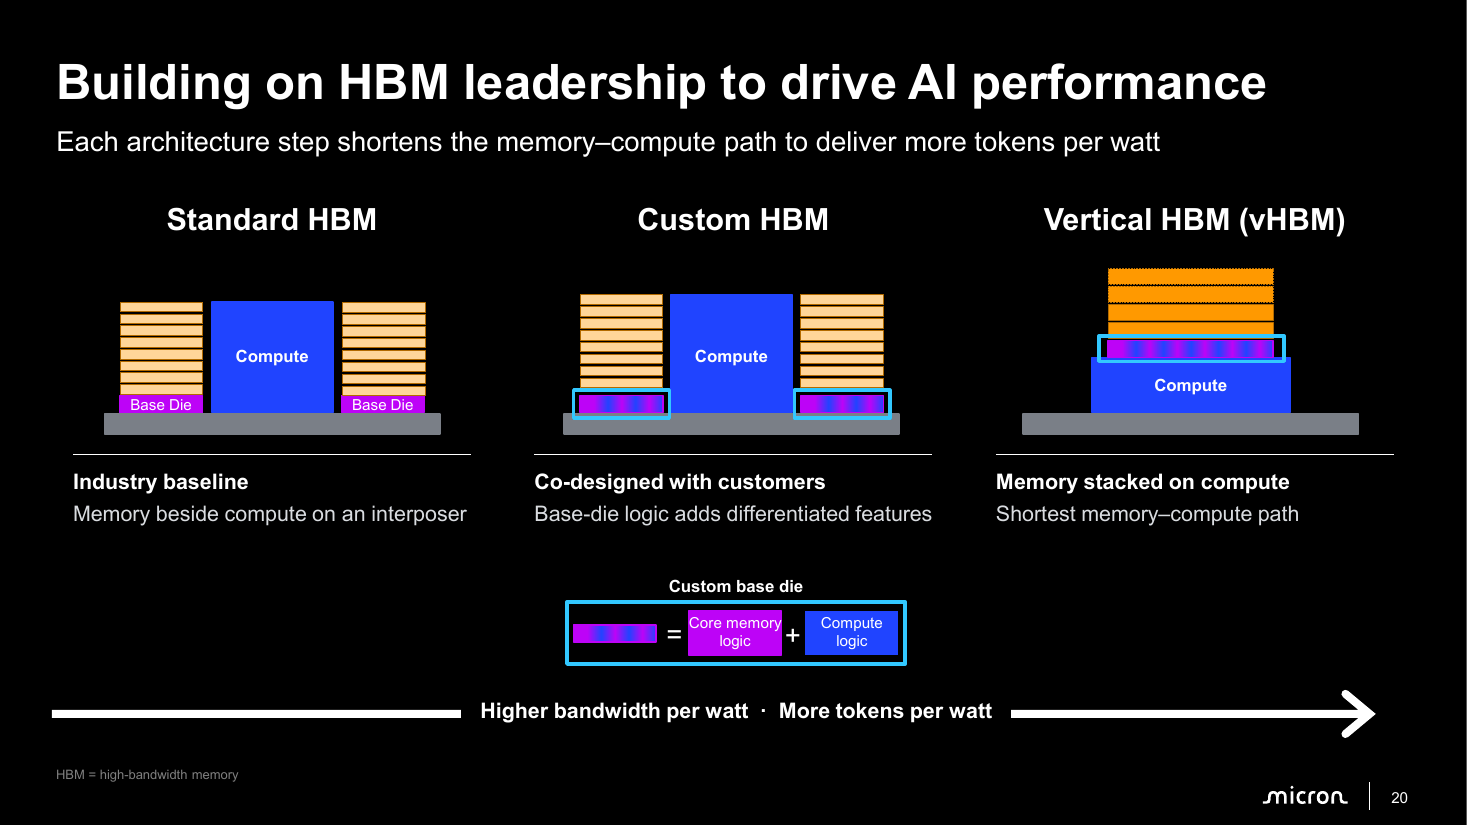
Right-Sizing Memory

Micron’s AI memory demand depends on workload-specific accelerator designs that shift bits among HBM, GDDR and LPDDR, changing wafer…

@StableBread

Fajasy on X

$AMZN, $GOOGL, and $MSFT play five roles for Anthropic at once: 1) Suppliers Anthropic has committed at least $269.4B to "regardless of actual usage." 2) Cloud marketplaces that sold ~48% of Anthropic's H1 2026 revenue. 3) Shareholders. 4) Customers. 5) Competitors. Some of Anthropic's suppliers also help fund its compute: → Anthropic can sell up to $20.0B and $15.0B more of notes or non-voting stock to $GOOGL and $AMZN, subject to certain conditions. → Anthropic can sell up to $42.0B of notes to $AVGO or a financial partner $AVGO designates, solely to pay the rent on its five-year chip lease. → $AMD agreed to buy up to $5.0B of Anthropic's non-voting stock in a July 2026 GPU supply deal, if certain conditions are met. So up to $82.0B of Anthropic's future funding can come from the same companies selling it compute.
@ActAccordingly 2 clicks

PAA Research on X

Gavin, you're always generous with your time on this platform and forthcoming with your views, which I genuinely appreciate. Where are you getting the $35Bish in future annual commitments when they have $500B in compute purchase commitments over a 5-7 year span PLUS the $AMD chip leasing deal (uncertain tenor) which is another $160B? Anthropic might very well grow fast enough not to burn cash, but that's not how the company frames it in their S-1. Rather than take my word for it, here's the relative language in the S-1: "As a result, we expect these investments to result in significant net cash used in operating and investing activities for the foreseeable future, and our net cash used in these activities may increase regardless of whether our financial performance improves" The business model is changing going forward. $ANT
@ActAccordingly 9 clicks

PAA Research on X

The way we were... I've been wondering why there was such a rush to get the $ANT S-1 filed amidst a brutal sell-off in AI related names. Then I read the filing and it's painfully clear. $ANT has scaled at a mind-boggling clip up until this point. Yes the company did generate operating cash flow and profits in 2Q26, but that no longer is representative of the business model going forward. With $500B+ of compute cost commitments with $MSFT $GOOG $AMZN and $SPCX and a $161B equipment lease with $AMD, the entire cost structure of this business is now changing under the "Anthropic Direct" initiative. They're showing you that delivering inference was a structurally high margin business in 2Q26 (50%+ margin). Will it be going forward? Well they're sitting on something that looks like $85-100B in compute commitments ANNUALLY. As a point of reference they spent $5.5B in 2Q26 on compute. Even if they get towards $80B of ARR by year end (which could be optimistic), it's a big hurdle to get to profitability in 2027 unless ARR doubles (or more). There is a placeholder for October 2026 ARR in the S-1. I cannot think of another single sentence in a SEC filing that will have more of an impact on the fate of capital markets than that one. My guess is everyone in the VC and tech community will up their Claude spend this month for that very reason.
@ActAccordingly 5 clicks

PAA Research on X

The way we were... I've been wondering why there was such a rush to get the $ANT S-1 filed amidst a brutal sell-off in AI related names. Then I read the filing and it's painfully clear. $ANT has scaled at a mind-boggling clip up until this point. Yes the company did generate operating cash flow and profits in 2Q26, but that not longer is representative of the business model going forward. With $500B+ of compute cost commitments with $MSFT $GOOG $AMZN and $SPCX and a $161B equipment lease with $AMD, the entire cost structure of this business is now changing under the "Anthropic Direct" initiative. They're showing you that delivering inference was a structurally high margin business in 2Q26 (50%+ margin). Will it be going forward? Well they're sitting on something that looks like $85-100B in compute commitments ANNUALLY. As a point of reference they spent $5.5B in 2Q26 on compute. Even if they get towards $80B of ARR by year end (which could be optimistic), it's a big hurdle to get to profitability in 2027 unless ARR doubles (or more). There is a placeholder for October 2026 ARR in the S-1. I cannot think of another single sentence in a SEC filing that will have more of an impact on the fate of capital markets than that one. My guess is everyone in the VC and tech community will up their Claude spend this month for that very reason.
@aleabitoreddit

Serenity on X

Markets often miss second order implications until it shows up in direct statements. - If $LITE is completely sold out... (largely due to $NVDA bottlenecking everyone else, eg. securing Greensboro capacity), where else do your other companies like $AMD / hyperscalers / etc. get their supply procurement? - $SIVE is coming online with like 1/6th of the world's current laser capacity by themselves. (100M+ cw dfb lasers vs. 608M EML/CW globally per Trendforce). Not even including their partner foundries that they're targeting 2:1 for. - $AAOI is coming online with a ton of capacity too next year enough to produce 400k ELSFP + $471m/month of transceivers. Then combine that with other supply chain statements like "Having 2-3 suppliers used to be the norm, now it is 5-7" from Lightcounting. So as long as your products actually work + can scale, it's hard to see anyone else with capacity not get qualified into your supply chains. Since optical component shortages are a massive bottleneck now.
@aleabitoreddit

Serenity on X

Everyone is asking "Where is Serenity" or "Who is Serenity". But nobody is asking... "How is Serenity"? I do read things from $AMD $8.2B acquisition of World Labs... but feeling pretty sick right now, so taking a little break. I remember saying physical AI + world models would major shift way back when, so maybe I should have invested in private companies at the time... Apart from that... other interesting news: - Some channel checks from ECOC was that $NVDA apparently secured 50% of $LITE Greensboro UHP laser capacity? And possibly contracts that allow them to secure the remaining capacity per Barclays. That's $5B in lasers (annual capacity)... so it's hilarious to see Nvidia go out and bottleneck the rest of the industry by doing this. But this just puts more strategic value on other merchant laser suppliers + more visibility for Lumentum. It's kinda game theory over allocation, since if you secure all the HBM, lasers, and others it inadvertently makes it much harder for competitors to scale their programs. - Then there's your massive $150B Nvidia authorized buybacks (just look at $AAPL when they did buybacks..) They're printing too much. - What's also interesting is that Samsung Electro-Mechanics is expanding their FC-BGA substrate capacity today... but customers are the one funding this. I also remembered $MRVL in SEC filings cited large body substrates as one of the core bottlenecks of their program (alongside $TSM sole source dependencies). So they also went out and did some other expansion agreements with related companies like AT&S recently. - OpenAI delaying Astra-6.1 October release over safety concerns just now. Nvidia also happened to launch an AI safety platform. I don't think this is meaningfully bearish that the models are just getting 2 good.
@aleabitoreddit

Serenity on X

All right $META Muse is cooking. I can hear all the $AMD, $INTC, and $ARM CPUs vrrrring in the background. Along with the memory + components (NICs, SSDs, DRAM) needed for all the browsers/VMs When I ask it to do a bunch of long form tasks… Intel CEO also said recently that CPU demand is so strong they can only support 50% of what customers need, so there’s some signals there. I’m also curious how much $AMZN or $NBIS is involved with running Muse, or if Meta hosts everything inhouse. Kinda an ADHD post but Meta beat my expectations with this release. Will keep trying it out
@aleabitoreddit

Serenity on X

$SIVE and $AAOI, yes for a 2027 timeframe. That's the nuance. Sivers you're coming on with 100M CW DFB laser capacity + 2 external foundries (maybe 300M in total), and all my supply chains mapping maps to larger hyperscaler suppliers. AAOI you're coming on with $471m transceiver revenue + 400K ELS units for 2028 timeframe. With hyperscalers + demand eating up all their capacity. There's just a $600m ATM which presents overhang near term. $NBIS already got re-rated but it's very positive upcoming for Q4 2026 (esp. with price hikes). Legacy memory like $ESMT + (some I haven't named yet) + regular memory names like Samsung, I do think will strongly outperform near term. And obviously CPUs names like $INTC $AMD $ARM as of recent.

Investor Letters

Letters that discuss AMD.

Every letter that discusses AMD

Tickers on this page

Companies the stories above are also about, besides AMD.