Calvin Blissett on X
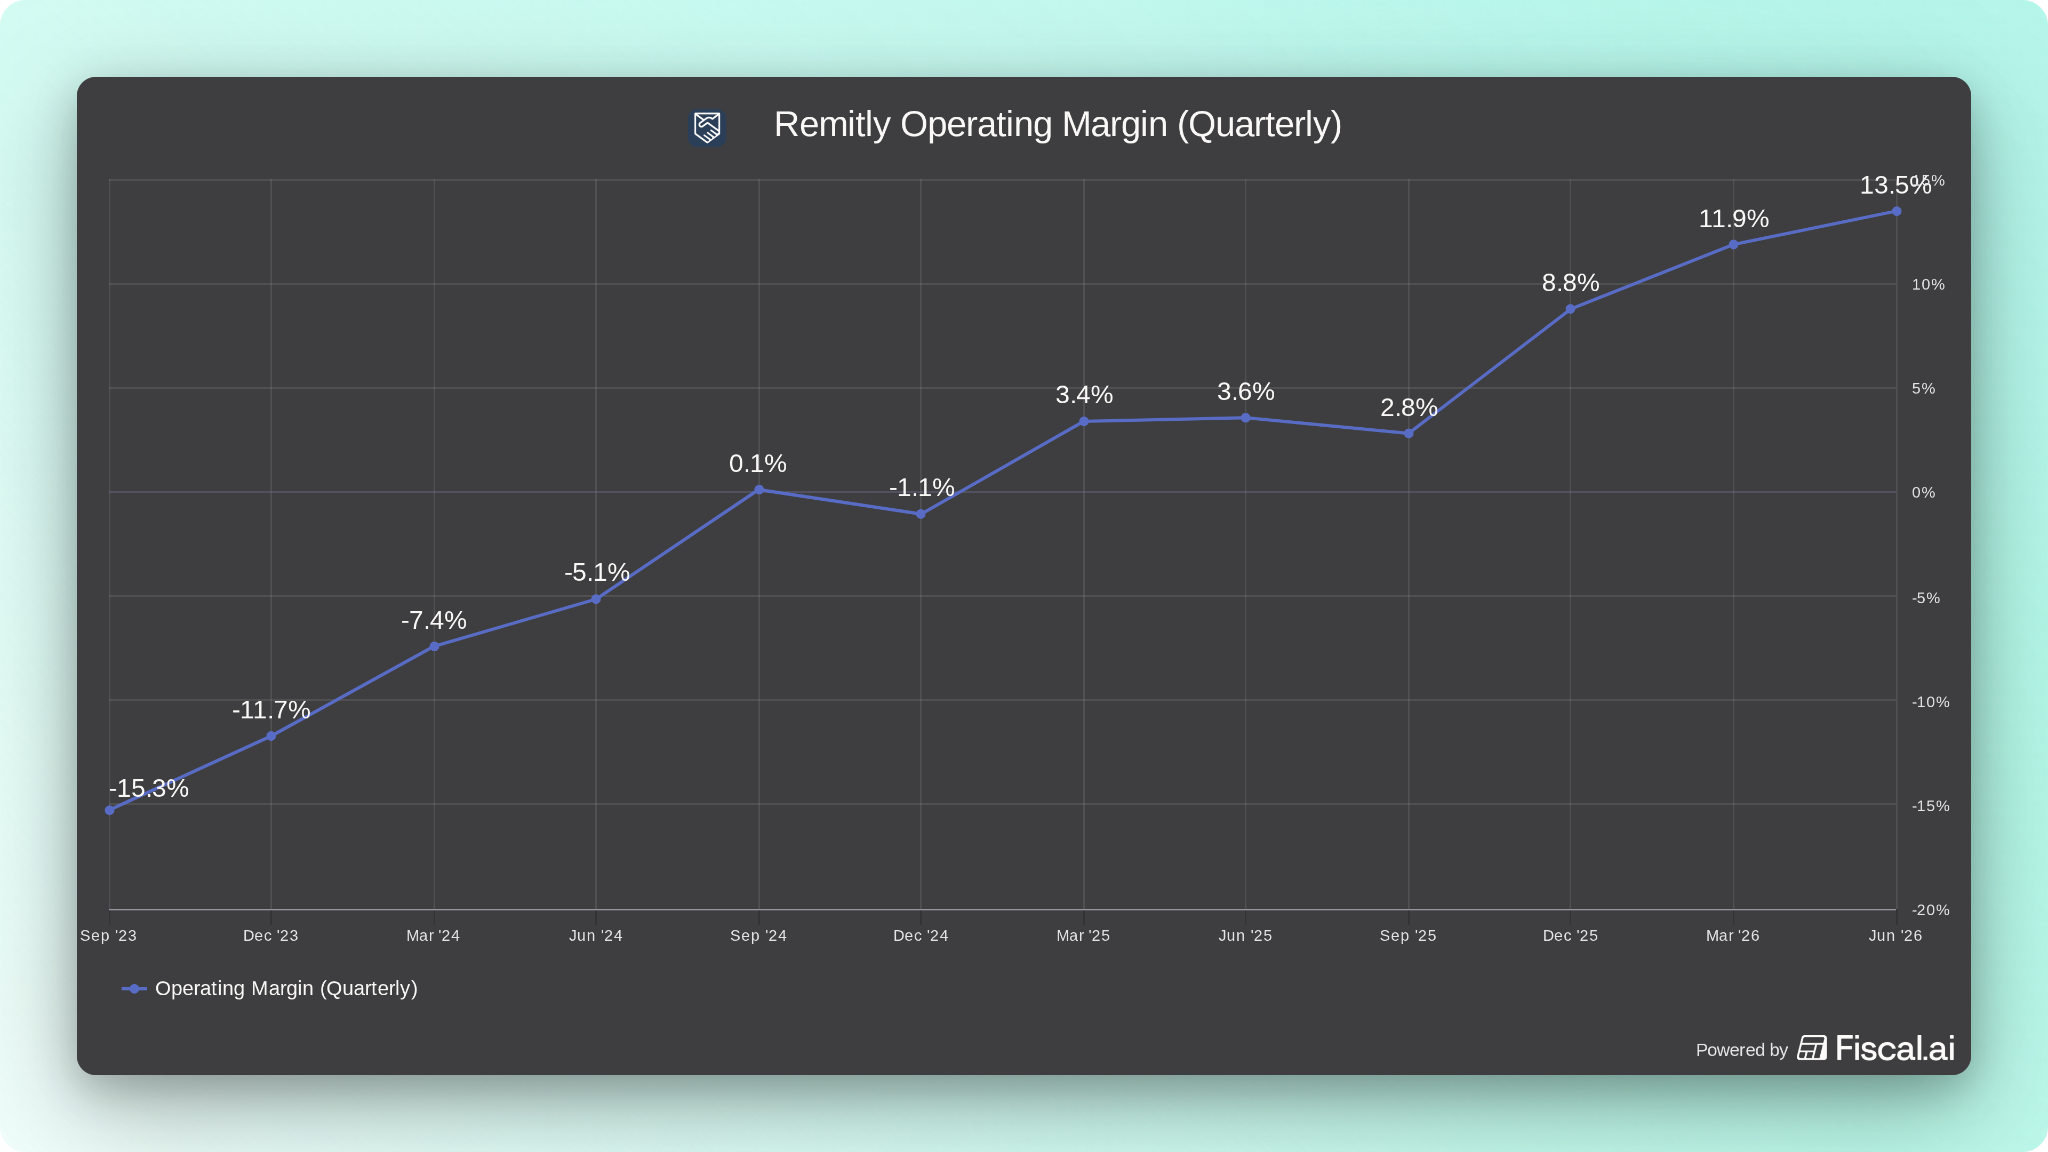
$IMXI now father from deal price than pre deal price. Market obviously saying deal won’t get done. I get AI treadmill math if 10x 2025 Owners Earnings (36m) but H1 2026 annualized is only 10m, FCF for H1 was like 60m due to pre paid wires working Capital benefit. What is interesting is the amount of interest and suitors that made in far before $WU agreed to buy, and also the pretty obvious value/synergies for an acquirer if regulatory hurdles as we’ve seen can be overcome