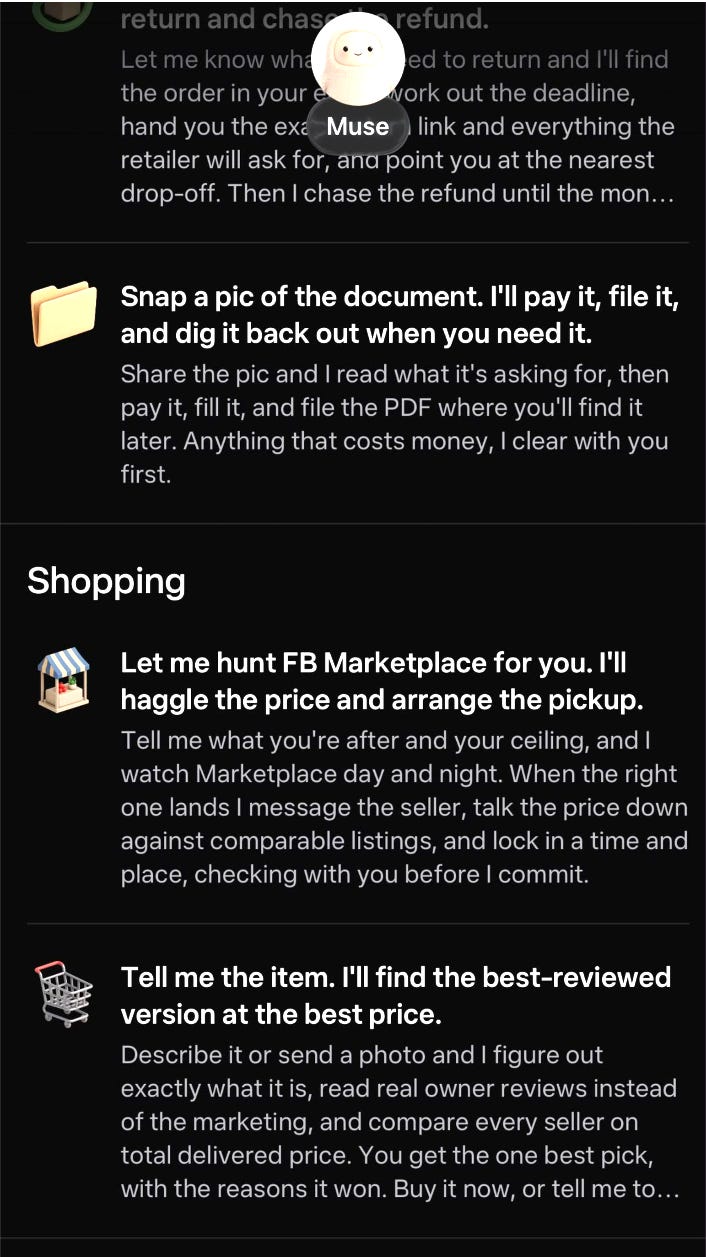
First Impression of Muse
Meta’s Muse personal agent connects multiple Gmail accounts, automates recurring tasks and offers free usage capped at 100 million weekly tokens.
Meta’s Muse personal agent connects multiple Gmail accounts, automates recurring tasks and offers free usage capped at 100 million weekly tokens.
if "MNO’s will never give SpaceX and Amazon low band" is true, then invert the logic and consider what SpaceX, $AMZN, and the MNOs would pay to prevent someone else from getting $NN's low band. This how you get the extreme upside case. Multiple parties that NEED to own it. https://t.co/EnjF9Wpc86
@DSacksCreative $NN The low band spectrum controlled by NN is quite valuable. $GSAT is a terrific comp. Sold for 11.6 billion. In many ways, our spectrum is extremely valuable and can carry more data and is more vital. Very desirable asset.
Seems like $PSUS and $PS going to trade worse than I expected. Looks like PSUS could open at a 20% discount to NAV and PS to trade below the $10 bn valuation from the latest 3rd party pre-IPO raise. https://t.co/Ix6uqF61LJ https://t.co/F5UNDNNVMb
@EricTheUmpire If you want exposure, buy $PSH.LN (or $PSHZF) which is trading at around 70% of NAV (implies $35/share for $PSUS). https://t.co/oSFLPLfnqr
I just published my Earnings Update about the Q1 2026 of Evolution $EVO $EVVTY. You can find it in the Portfolio section of the blog :) https://t.co/QXlBS93lji
@ramahluwalia how much are you investing in $acn as a % of your book?

Dell’s Q2 revenue rose 57.7% to $47.0 billion and RPO tripled to $132 billion, but its stock trades at 32 times unlevered pretax free cash…
Dyne Therapeutics fell 16% after Novartis’ HARBOR failure raised doubts that RNA-targeting biomarker gains translate into functional…
 Petri Dish Reports 1 click
Lululemon’s Q2 revenue fell 4% and Americas comparable sales 12%, as markdowns, tariffs and activewear rivals pressure its premium apparel…
Qualcomm targets $15 billion of data-center revenue by FY2029 through AI accelerators, custom ASICs, Arm server CPUs and hyperscaler wins.
 Khaveen Investments
Ryan Tunis discusses P&C insurers, favoring Travelers over Chubb in a soft commercial market and calling AIG a near-book-value self-help…
MBI Deep Dives will update prior company analyses through year-end, beginning with Uber, while deferring new work on Micron and S&P Global.
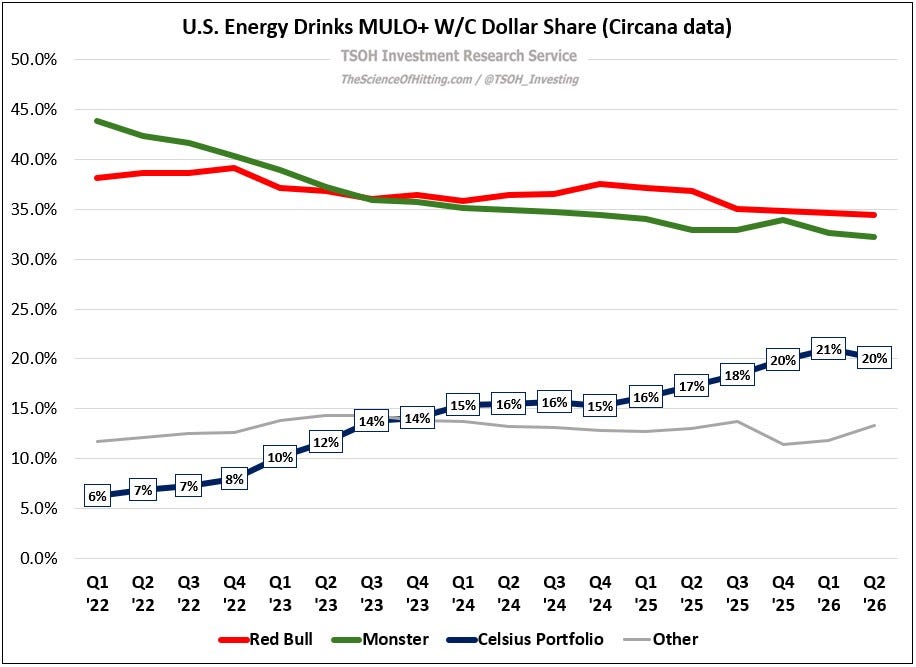
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
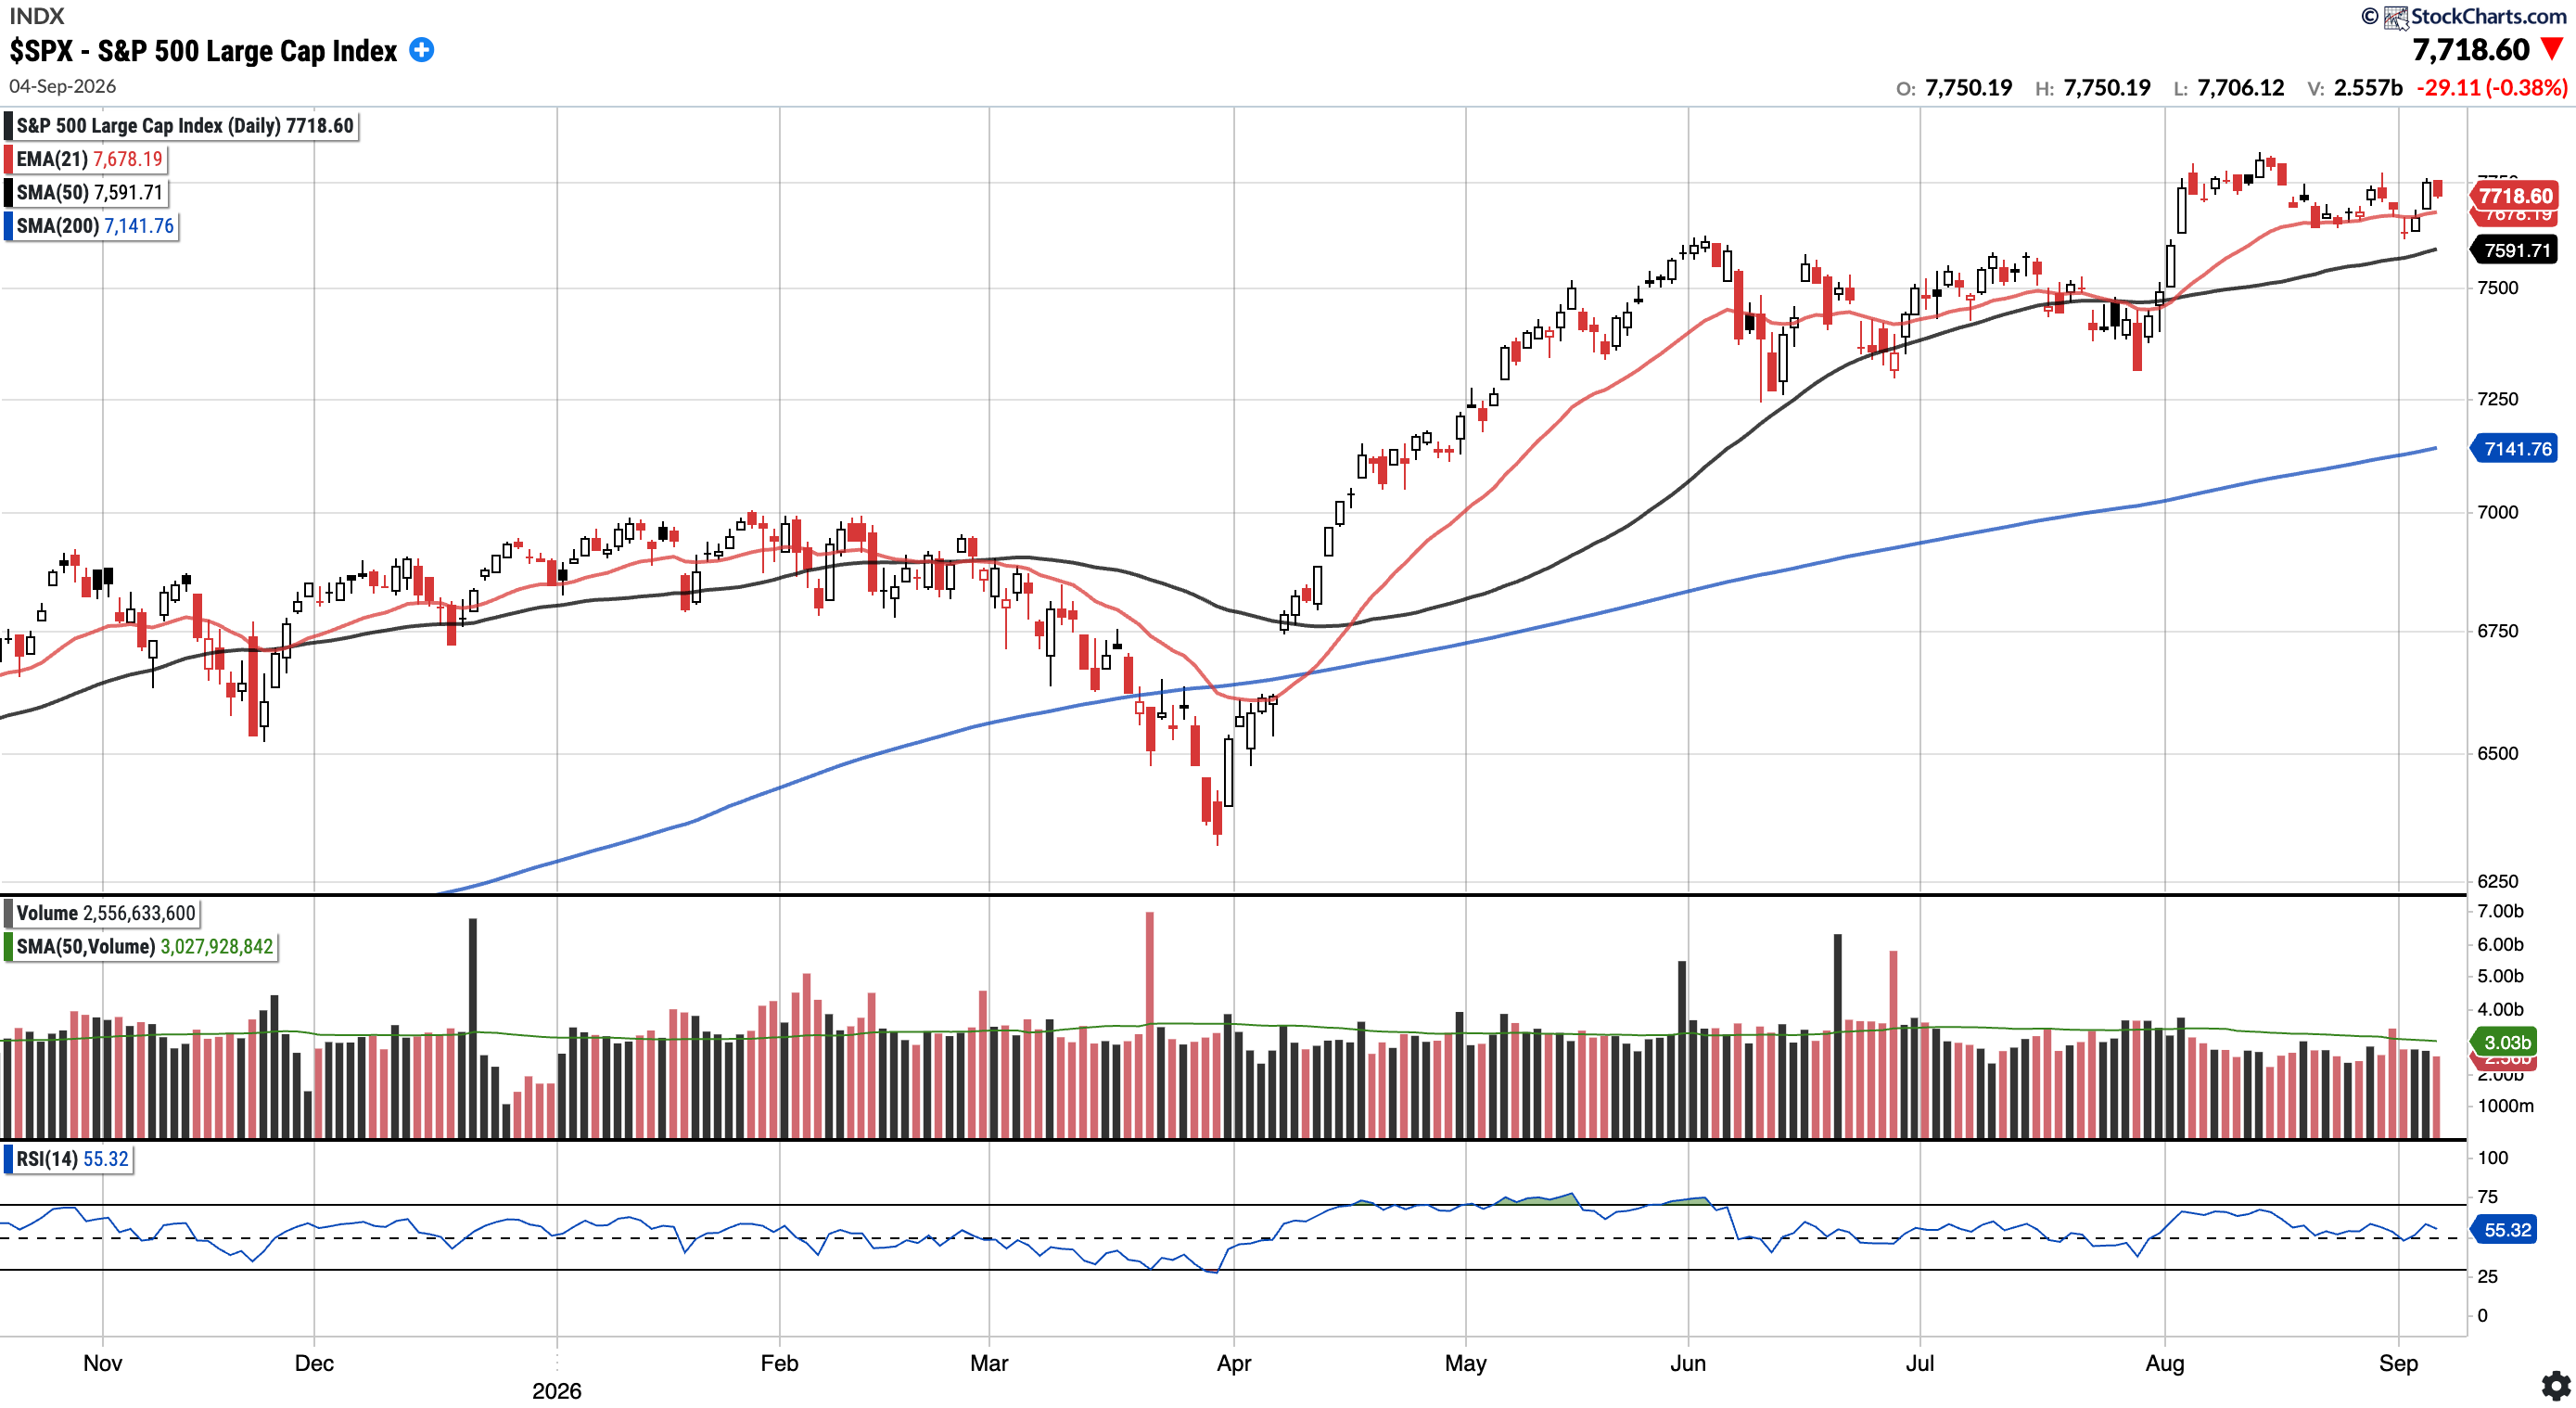
U.S. CPI and PPI headline the September 7 week as the S&P 500 holds key averages, Bitcoin faces $82,000 resistance and gold tests its…
AppLovin is down 48% YTD after its first guidance miss, with revenue 1% below expectations and EPS 2.5% short, reviving fears of an adtech…
RBC Bearings' Q1 2027 revenue rose 19.2% and net income 48.2%, while a $2.3 billion backlog driven by aerospace and defense supports growth…
 Daniel Jones 1 click
 FTAI · long
FTAI Aviation, valued near $23 billion at roughly $226 per share, is presented as a long investment.
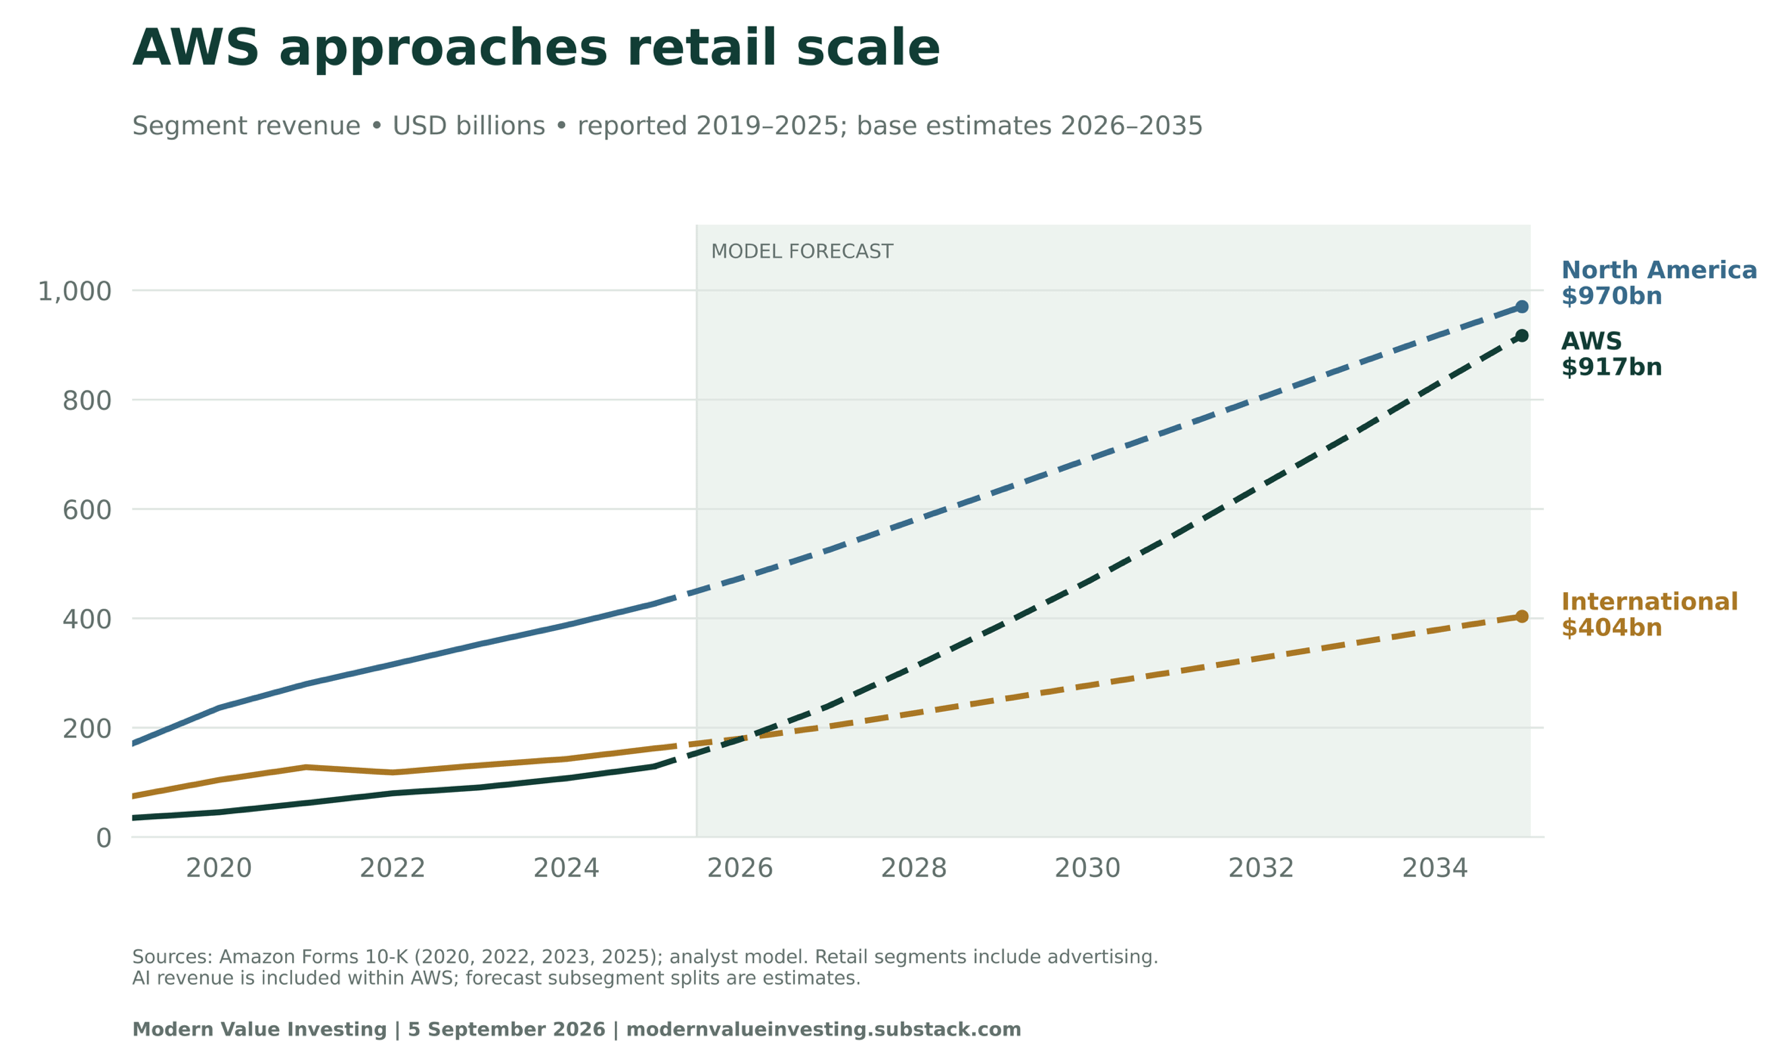
Amazon combines AWS AI infrastructure, model-company stakes and retail automation, with AWS targeting $1 trillion in annual revenue over…
Netflix’s roughly $20 billion content budget can become an editorial advantage as generative AI cuts production costs and floods viewers…
Wells Fargo Series L preferred shares yield 6.55%, with preferred dividends consuming 4% of Q2 2026 profit and no call risk.
 The Investment Doctor 1 click
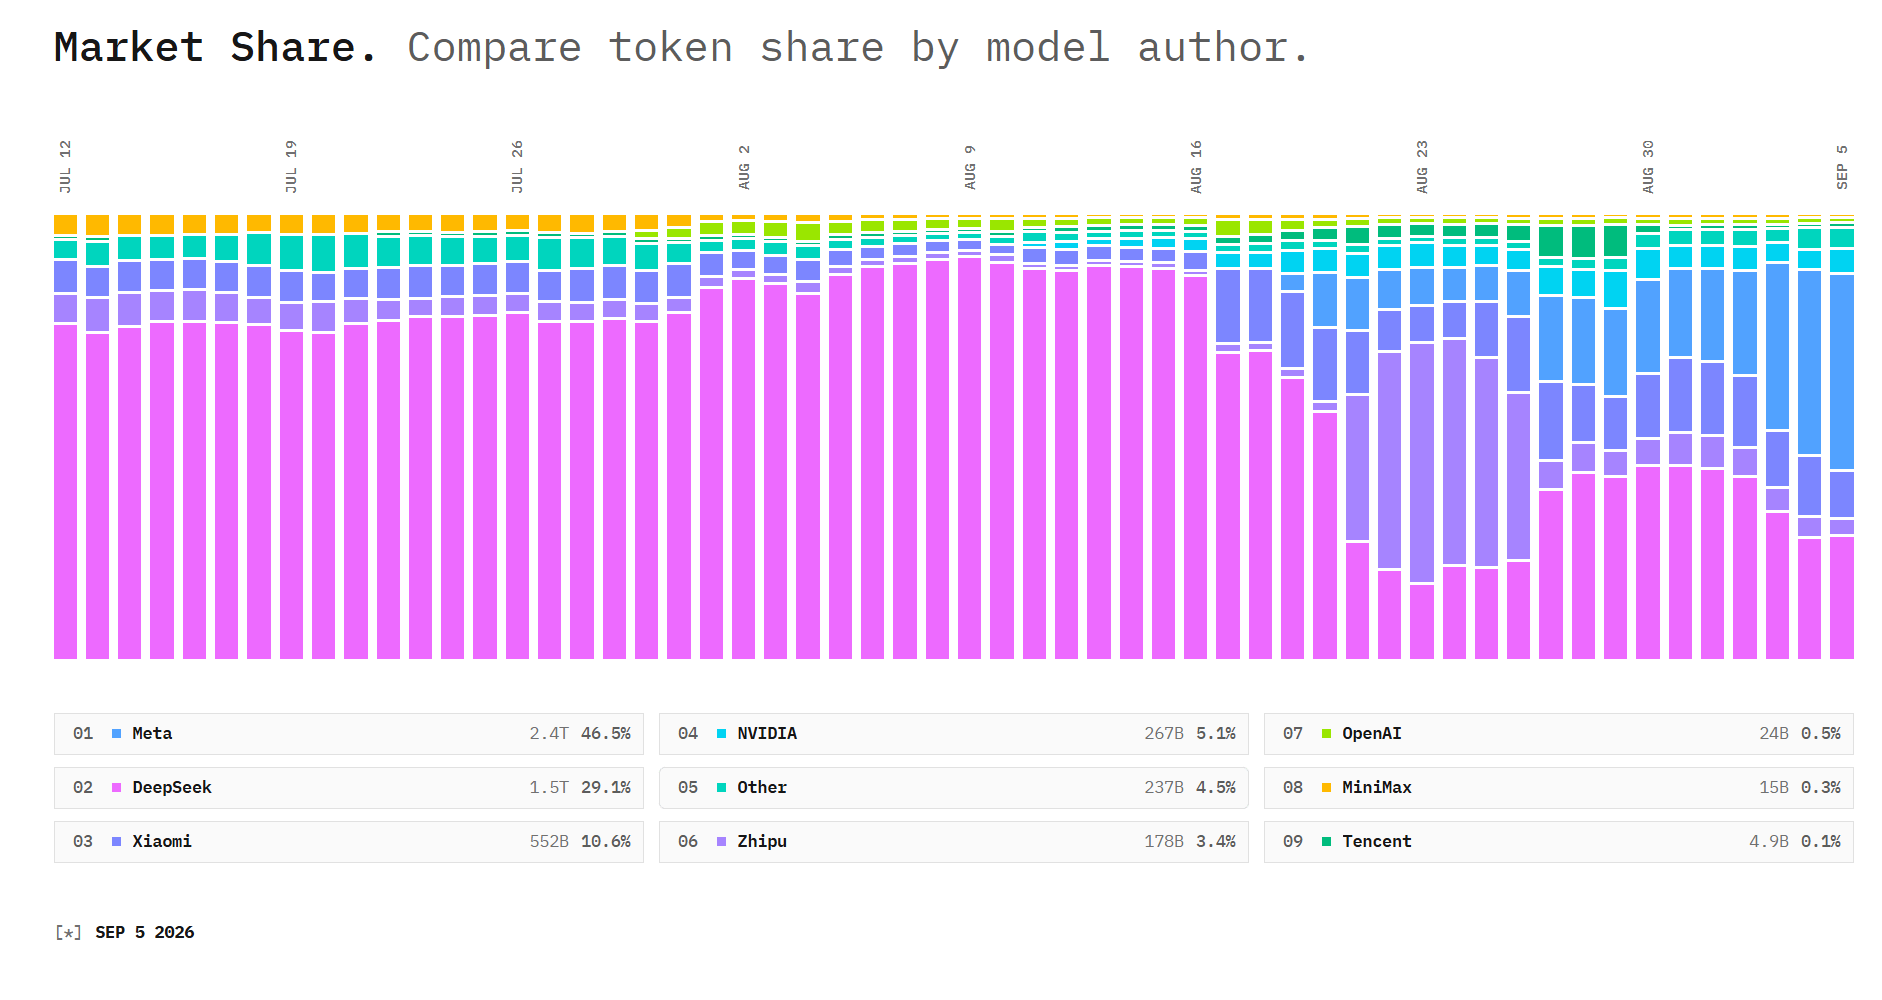
Meta’s free model strategy lifted OpenCode token share from 25% to 40%, building coding-data feedback loops and reducing reliance on…
OpenAI's potential failure could expose the US economy's growing dependence on AI capital spending, according to Steve Eisman.
 Petri Dish Reports 3 clicks
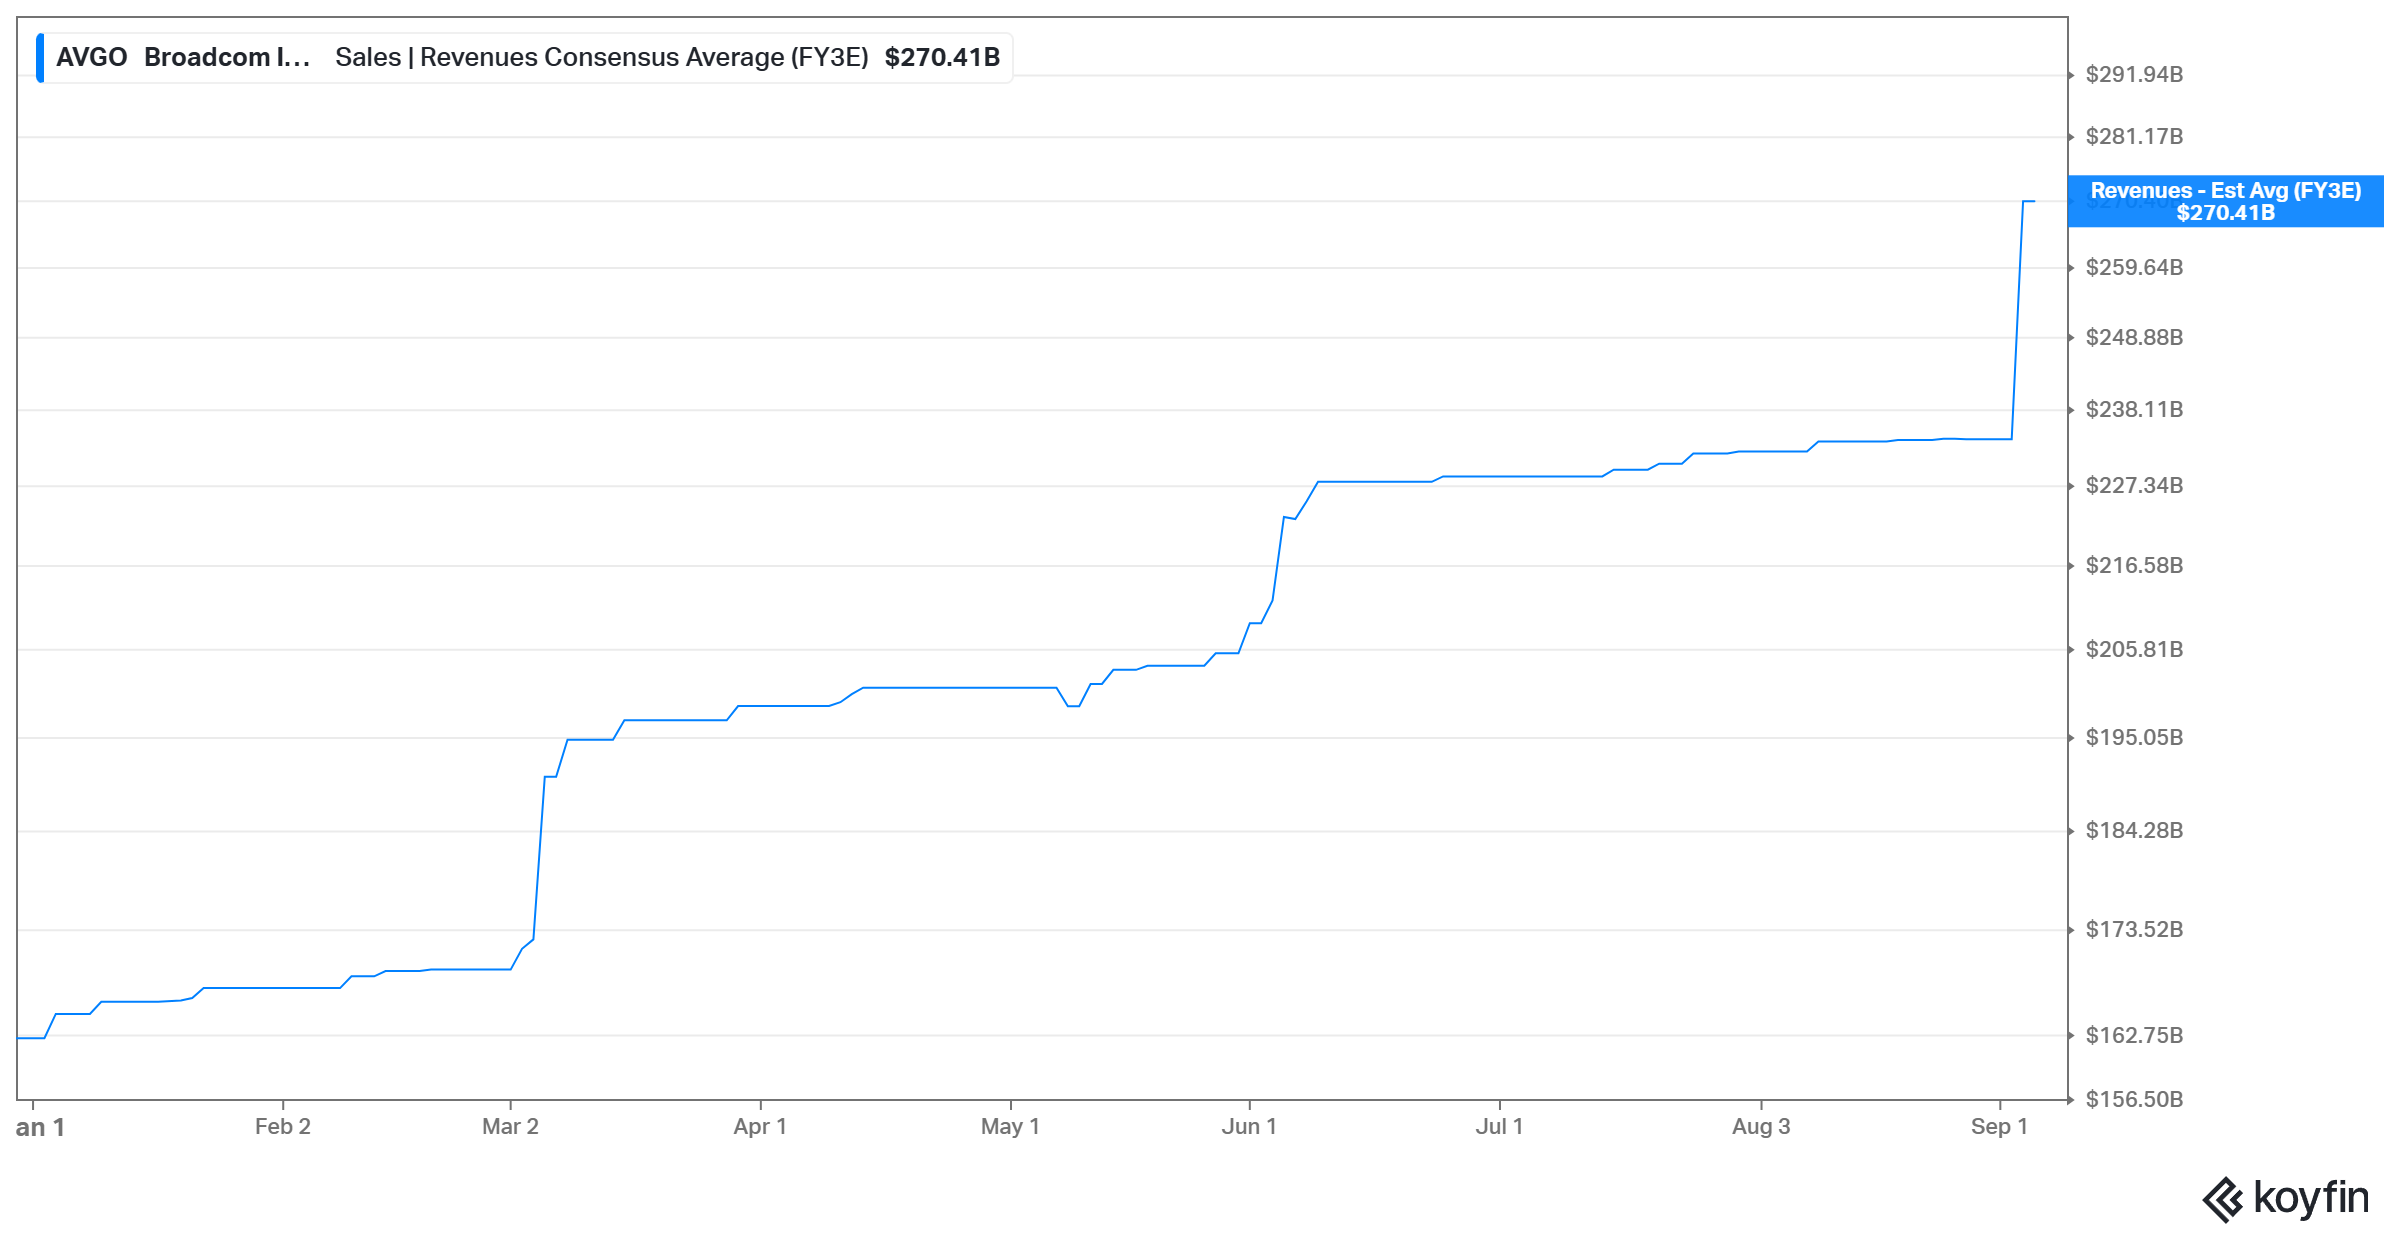
Broadcom’s FY2028 revenue estimate rose from $162 billion to about $270 billion and EPS from $17.60 to $30, while the stock remained flat…
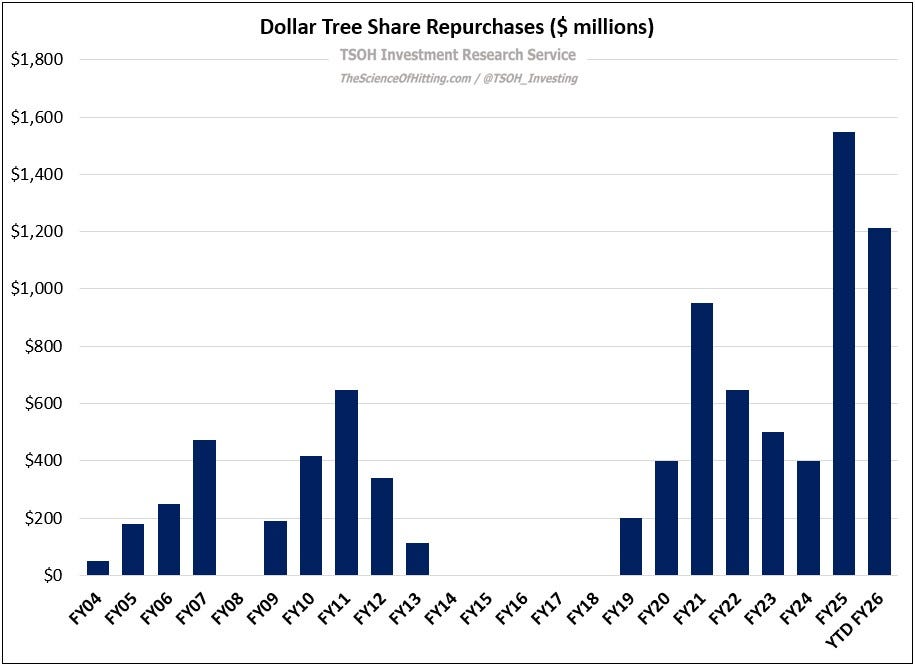
TSOH Weekly Roundup covers Costco’s $4.99 chicken supply chain, Celsius’s 20% energy-drink share, and California utilities’ wildfire…
Broadcom's AI semiconductor revenue rose 221% year over year as custom silicon programs and VMware software cash flows fund further…
 Simple Investment Ideas 3 clicks
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.