
Consumer agents: an ethics race, a prisoner’s dilemma, and the obvious OTA short
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
NASDAQ
EXPE
12 stories
$31B Market cap · 2026-10-07
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
Anyone have any suggestions how Muse and Grokbot and more versions to come of agent personal assistants is bullish of communication stocks like $RNG and $FIVN? Took out some of the intermediary businesses like $EVER and some pressure on $EXPE earlier in the day but seems next level is EXPE, some of the insurance brokers, and then phone communication systems seem at the top of losers from changing engagement and channels for B2C and B2B comms
One of the many ways how the new market structure is so frustrating at times..... $EXPE moves higher both days this week despite a significant increase in both rates (credit cards) and oil (jet fuel) that directly makes their business more challenged moving forward (weakened consumer + high airfares), but the power of sector buying Software/ai disruption (where an its sits) as people push out of semi and forced to cover their paired shorts overwhelms the fundamentals. Headless flows dominate the market
still feel the rotation from July-current is more about a short squeeze (the opposite end of the Situational Awareness portfolio) and the dispersion of having to unwind the long semi trade portion. But that rubber band is similarly stretched as it was the opposite direction at the end of June. Still feel its in the process of reversing (even the morning action today looks like a top could set in?) $RNG, $IT, $APPN, $TGT, $EXPE, $FDS, $PAYC, $ELF, $MET, $MFC, $GDDY, $V, and many more that were AI losers that have had incredible runs in the past 4-6 weeks seem like good ways to be short against a snap back to AI or a more seasonal unwind from policy risk trying to control rates, midterm/fall seasonal factors, etc. Especially with SaaS earnings taking the stage later this week and next (overshadowed by $NVDA on Wednesday)
Oil up 7.5% and $EXPE continues its squeeze because it's simply the opposite end of the ai trade? How long can these on/off trades define every stock in the market? Crazy
Dispersion trade creating opportunities of fundamentals not matching price: $FDS now higher than the before SaaS (apocalypse) took off. Hard to argue they are not one of the most disrupted names across data services / software $PAYC $PCTY $WDAY - same challenges across software names and pricing / seat pressures. These names also face heavy increased competition from Rippling $EXPE - Hotels going direct has already started and OTAs should see supply pressure and take rate pressure $RNG - Does anyone legitimately believe they're an AI play? Agents don't need calls, don't need phones, and you don't need RNG to provide those agents - especially as every sb and up software provider and crm/erp Many others across software but also in financials, industrials and consumer
Yesway, Dollar General and Expedia feature in a research roundup spanning convenience retail, discount stores and AI-driven travel search.
I recently sat down with @StockJabber at @IdeaBrunchEmail to discuss the strategy behind Multiples Capital's outperformance in 2025. The full interview is behind a paywall, but here are 4 core themes we discussed: 1/ The Multi-Asset Edge While many leaned on the "Magnificent 7," we found alpha in global de-dollarization and the massive electricity demands of AI data centers. This approach delivered a 3.15 Sharpe Ratio—with roughly half the turbulence of the S&P 500. 2/ Garrett Motion ($GTX) Update Since my last feature, $GTX has surged ~170%. We discussed the "perfect storm" of index inclusion and aggressive capital allocation that drove this run, and why the "EV-only" fear proved to be premature. 3/ AI Disruption vs. Mispricing The market is correctly identifying "AI Losers" in SaaS, but it’s applying that same anxiety with broad stroke. We broke down why Expedia ($EXPE) is a prime example of this mispricing, trading at a 12%+ FCF yield despite its essential role in the global travel ecosystem and it's growing B2B setment. 4/ My Favorite "Tokenization" Play We closed with a deep dive into the digitalization of finance. I shared my top idea for playing the tokenization trend, a company currently acting as the "digital infrastructure provider" for institutions and growing it's subscription and service revenues. Read the full deep dive here: https://t.co/kuRyJtSPMh Note: As this is premium content, I cannot share the PDF on a open platform. However, if you’d like to join my quarterly investor letter distribution list to see how we are positioning for the "Broadening Trade" in 2026, please send a DM.
It's always amazing for me to see $expe stock getting pummelled evertime there is AI disruption related sell off in the market. Expedia is a platform, for an AI app to replace it, one will need to build something equivalent, get all the hotels to list it there (as inventory) and manage the bookings. Not that it can't be done but it's not same as replacing a SaaS company. Instead I see Expedia using AI to navigate the change. It's more likely that AI replaces how users find hotels on Expedia vs via google search now than the former happening. Also, it's a super recession proof business model. Time will tell for sure :)
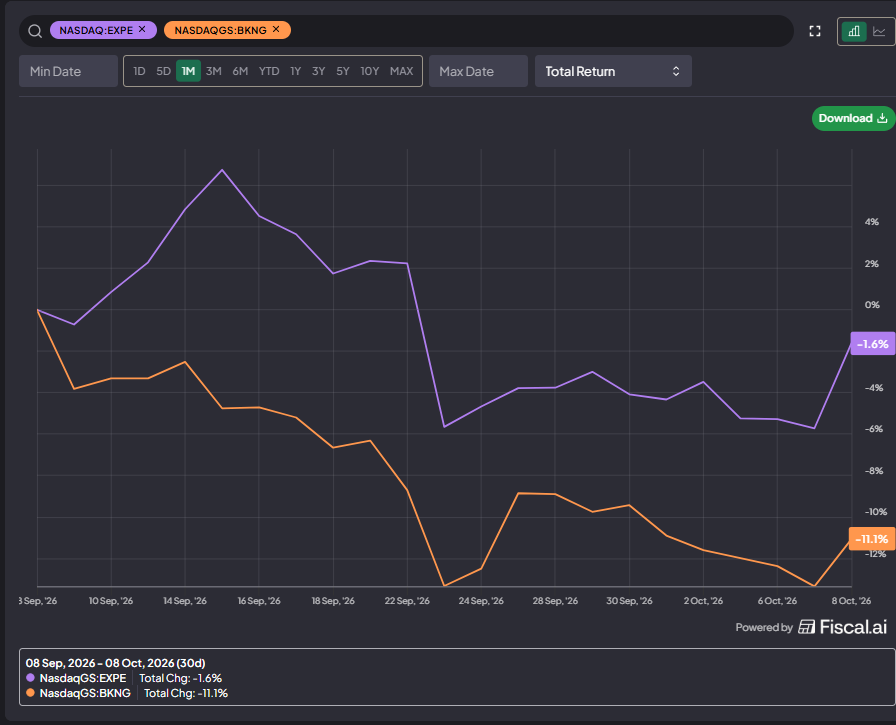
$BKNG vs $EXPE https://t.co/zzuhmvsl0k
"Rally of the 2nd Tier": the runner-up is running the show over 6m/3m/1m time periods: • Silver > Gold ( $SLV > $GLD) • ETH > BTC • Small caps > S&P 500 ( $IWM > $SPY) Seeing it occur even in individual stock levels: • $AMD > $NVDA • $EXPE > $BKNG • $LYFT > $UBER What it implies: That breadth + beta has been improving, perhaps in anticipation of rate cuts and overall healthier economy than anticipated. Likely keeps the bull run going for now. Charts below
$EXPE has always been a much slower grower than $BKNG, won't be surprised if it's a fav pair trade of hedge fund (long booking, short expe). Over the years though Expedia has been going through internal changes, sold some businesses (Egencia to AmEx travel and few other sites), went through a technology transformation for internal sites (Expedia, https://t.co/ap3OIandej, Vrbo). 50% improvement in operating margin since 2019. But not as profitable as Booking (operating margin at 12% vs 32% for bkng). Mainly a US focused player (unlike bkng) with a very strong B2B segment that's growing mid teens and about 30% of total revenue), now looking to expand internationally. To be seen if that would drive higher margin given the much fragmented hotel market internationally vs US. Bkng on the other hand seeing revenue growth slowing down to high single digit and mid teens eps growth with margins declining since 2019. Expedia needs to show higher top line growth but possible still delivers mid teens eps growth. Travel is cyclical but these OTA are very robust, they saw revenue growth even in the financial crisis, as more ppl look for deals. AI is an unknown, Expedia is embracing it. Finding a hotel with the right deal is not same as getting an answer to a question from LLM, distribution/platform should remain valuable. Interesting to see how the pieces fall for Expedia, PEG < 1 and these multiples should atleast provide downside protection
Letters that discuss EXPE.
Companies the stories above are also about, besides EXPE.

