KEDM.com on X
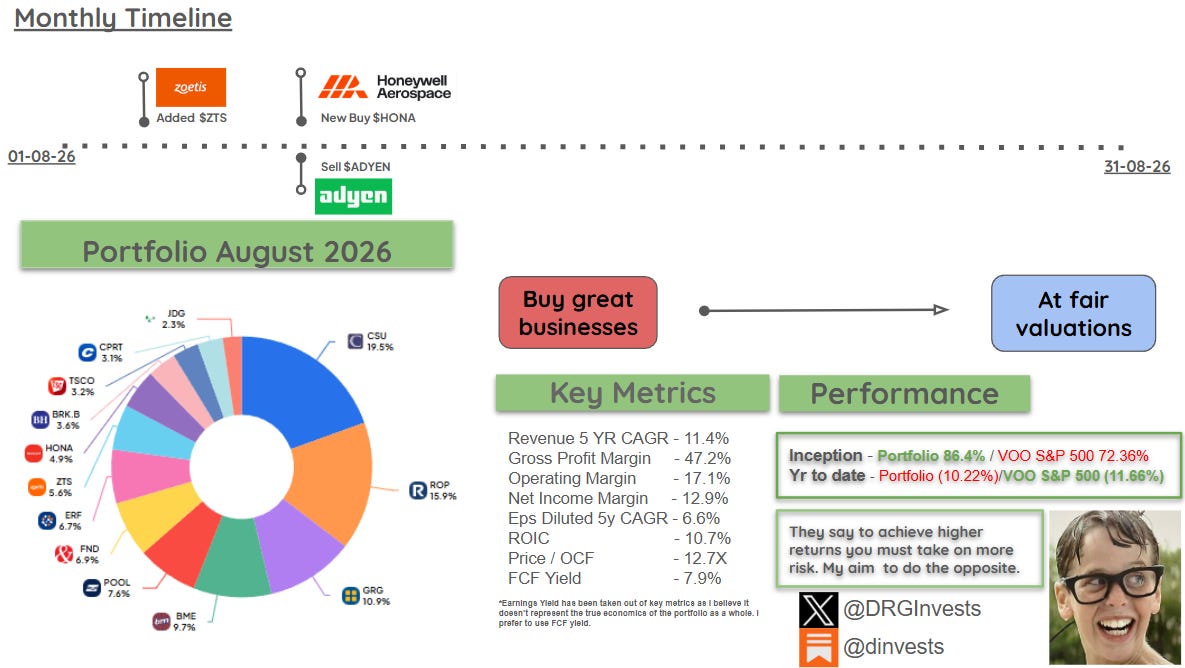
A company that is not having a good time is the recent spin-off, Honeywell Aerospace $HONA, which is still not recovering from the poor set of results. A reminder that these guys are targeting 6-8% organic growth through 2030, with EBIT and FCF growing faster than revenue. The business combines leading OEM positions with a large aftermarket franchise, including the #1 position in APUs (~65% share) and the #2 position in avionics. Cheaper than its peers, but for a reason? That's why it's interesting to see the first insider buying shares on the open market.