Merger Monday & Election Implications
EQT’s $50 billion merger with Range Resources and Ovintiv’s $1.26 billion acquisition of Logan Energy reshape North American oil and gas alongside Brazil and British Columbia election…
EQT’s $50 billion merger with Range Resources and Ovintiv’s $1.26 billion acquisition of Logan Energy reshape North American oil and gas alongside Brazil and British Columbia election…
Another consecutive solid double beat this morning for $ROP with acceleration across all their prop data verticals https://t.co/mdWiAnYwpo
I do deep value and small companies, however value can be anywhere. I did enjoy reading this though and it is compelling. $ORCL https://t.co/Ix1PyWwNIF
Whoops. Investors beginning to realize that $META issuing equity for capex is a shitco move. https://t.co/JZaCvO2fOC https://t.co/i7TIcEVCyk
$AAPL has outperformed SOX by around 40% since June https://t.co/6G1LMCerLs
Truist Financial trades at 10.5x earnings and 1.5x tangible book as new CEO Mike Lyons sells non-core assets and targets 16% to 18% ROTCE.
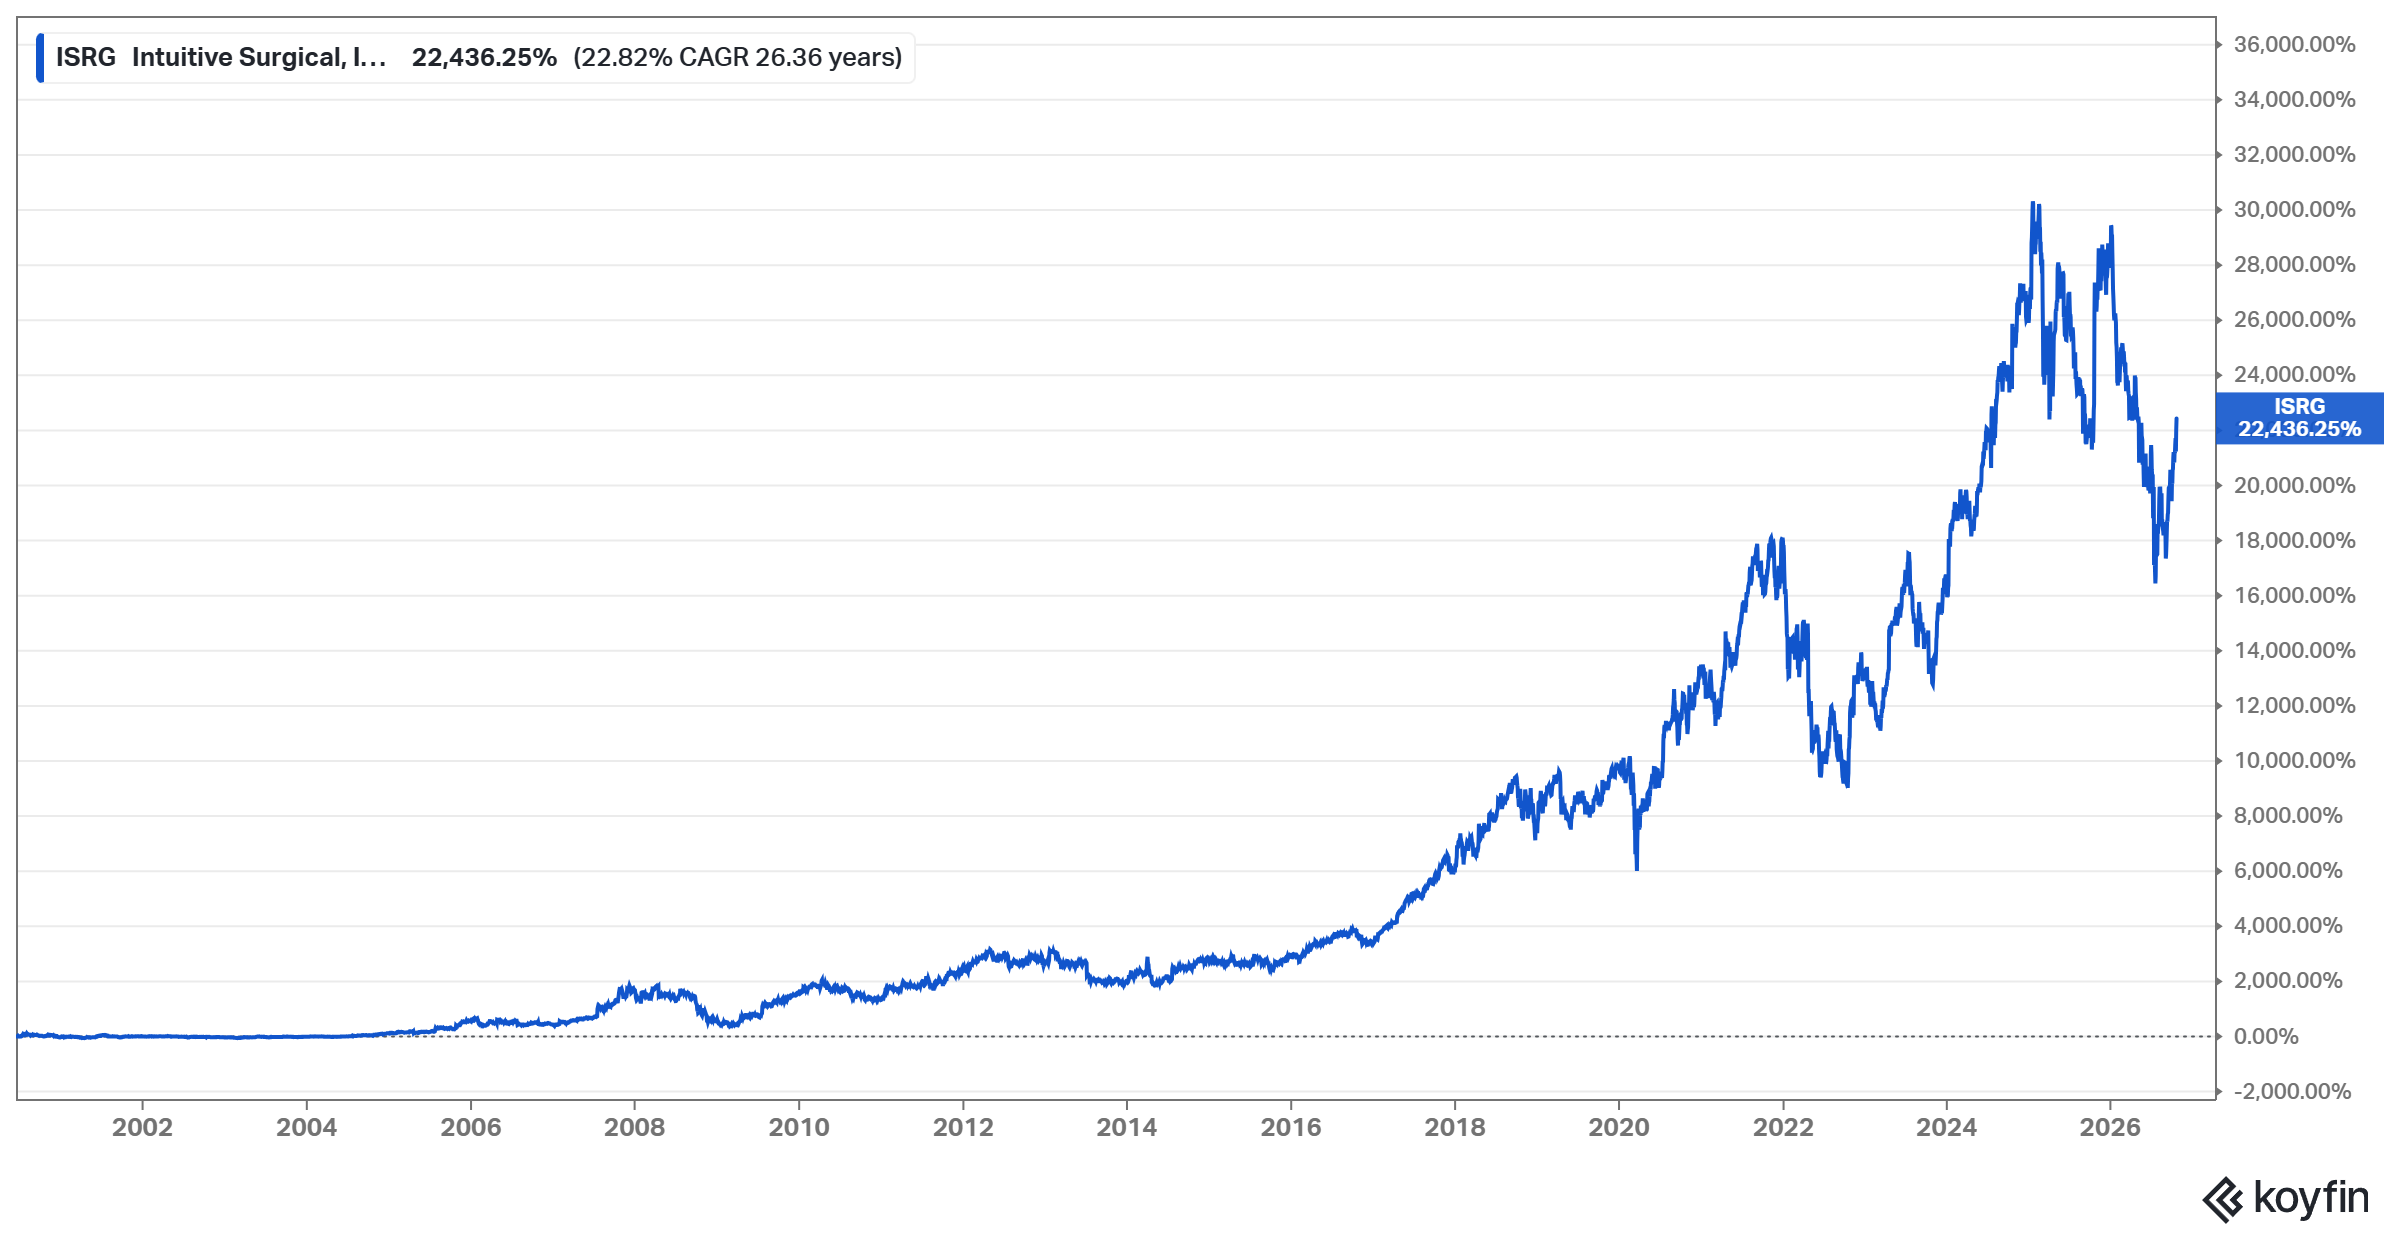
Intuitive Surgical built da Vinci into a 12,000-system surgical-robotics network performing 10,000 daily procedures, while high-volume…
Molina Healthcare and Kinsale Capital’s earnings are reassessed through a long-term lens, emphasizing conviction and detachment during…
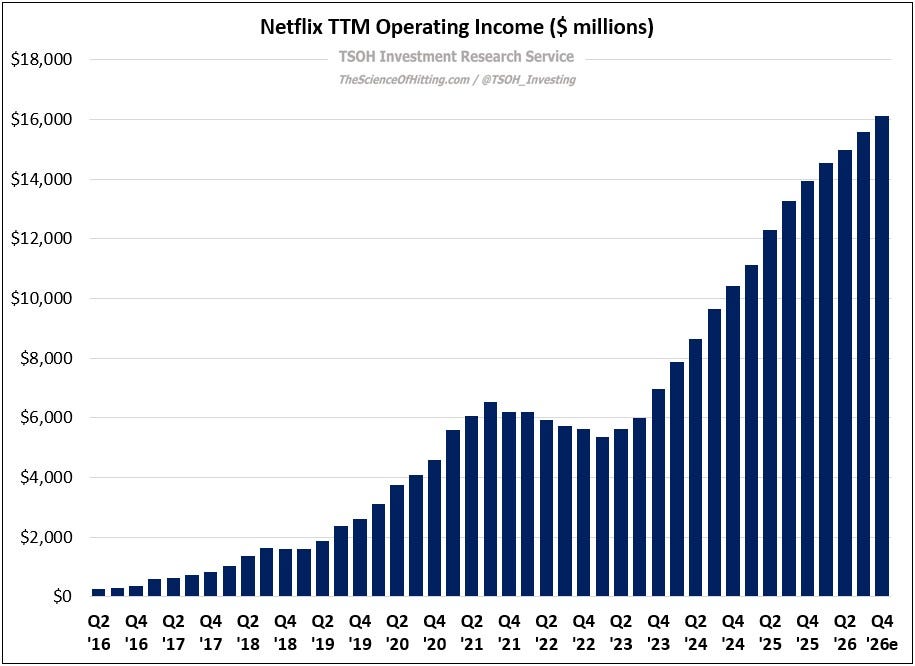
Netflix’s $51 billion FY26 revenue outlook and global streaming scale underpin its core strategy as management addresses slowing…
CEWE sold its low-margin printing unit and agreed to buy Kodak Moments for €88M, expanding into North America.
Analog Devices generated Q3 revenue of $4.02 billion, up 40% year over year, with AI and data centers contributing under 20% of sales…
 Narek Hovhannisyan 6 clicks
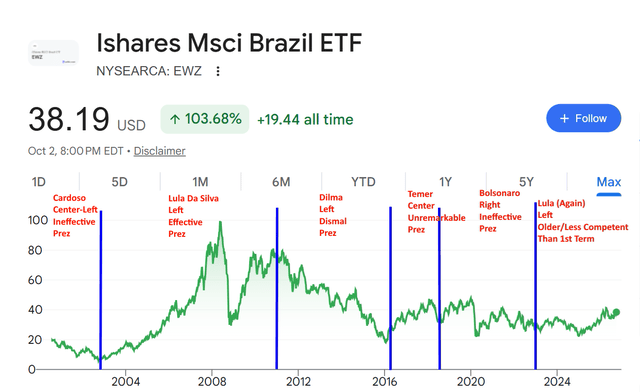
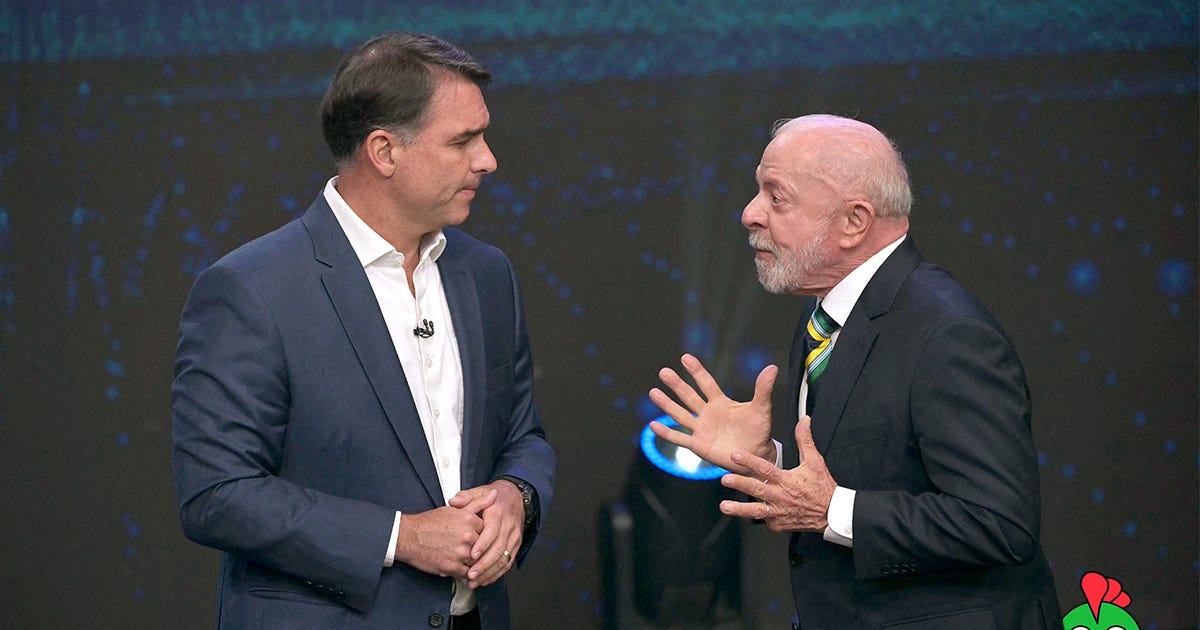
Brazil’s Lula victory leaves Nu and Inter’s thesis intact, while JetBlue heads toward bankruptcy and Mexican airlines pursue a merger.
American Express’s Q3 billed-business growth slowed and cards in force fell sequentially, but management attributes the weakness to…
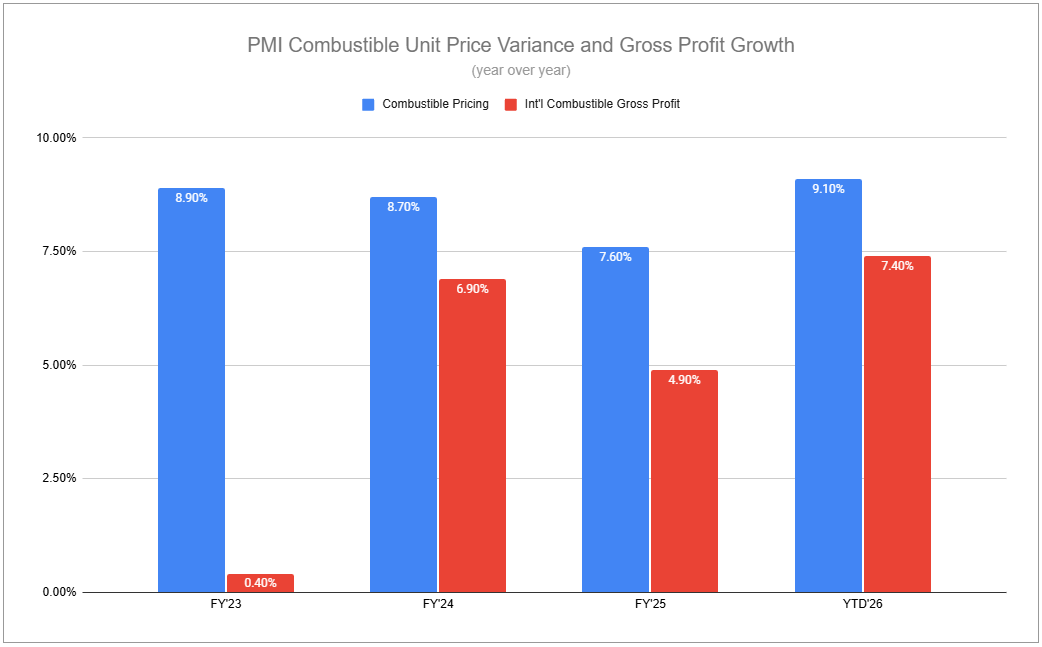
Philip Morris posted 7% organic Q3 revenue growth and 10% operating-income growth as 9.1% cigarette pricing offset flat volumes, while IQOS…
Meta posted 26% revenue growth and $9.89 billion in legal charges while funding $35 billion of capex, as AI lifts ad pricing and pressures…
 Tim Travis 1 click
 DLTR · long
Dollar Tree is long after divesting Family Dollar, separating its stronger banner from its weaker business.
Tower Semiconductor’s low-loss photonics chips halve lasers in 1.6T optical modules, supporting a $680 million annualized photonics run…
Super Micro’s 2026 xAI rack orders, GB300 price increases and B300 mix frame its gross-margin outlook.
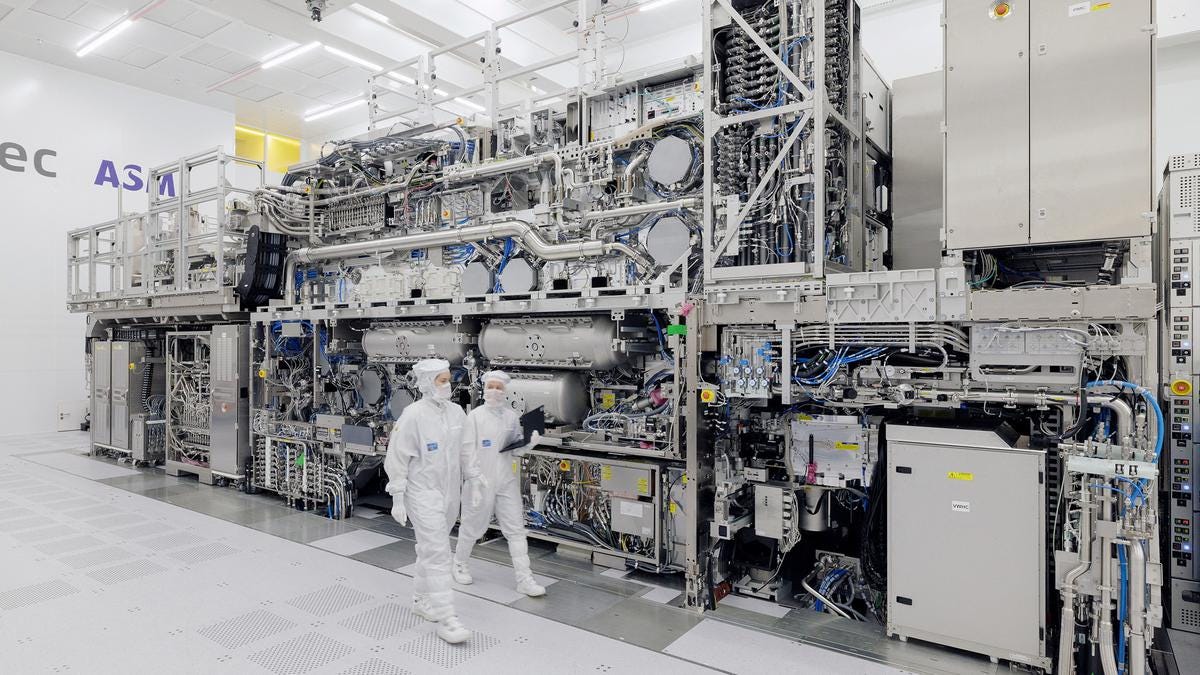
ASML’s €230 million EUV machines underpin advanced AI chip production, with demand booked through 2028 after nearly $9 billion and two…
Netflix pairs international engagement, free cash flow and buybacks with plans for double-digit revenue growth, margin expansion and larger…
 Juxtaposed Ideas 8 clicks
Petrobras’s Morpho-1 well revived hopes that Brazil’s Equatorial Margin can become a major new oil frontier after hydrocarbons were…
 Dhierin Bechai 2 clicks
CoreWeave’s rising debt yields and fading confidence in AI data-center economics frame a weekly review of Meta, Tesla, SpaceX, Netflix,…
CoreWeave's financial statements point to a business model familiar to the authors after a closer review of the AI infrastructure company.
 Star Investments 9 clicks
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Dane Bowler
 David Zanoni
 Deep Value Investing Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen Tim Travis
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.