WD #360: New Trade, Recent Market Action, Brazil/Inter Update
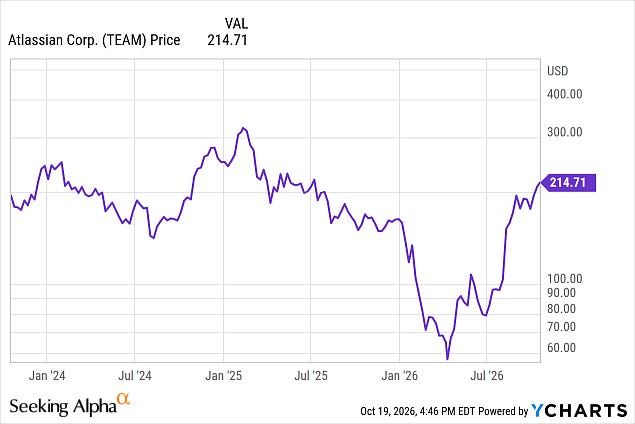
Atlassian is sold after a 130% gain, while iShares MSCI Indonesia ETF is added following the market plunge; the update also assesses the AI-stock selloff and CoreWeave’s collapse.
Atlassian is sold after a 130% gain, while iShares MSCI Indonesia ETF is added following the market plunge; the update also assesses the AI-stock selloff and CoreWeave’s collapse.
This POS $CRWV will go bankrupt IMHO. https://t.co/wiuFzGG4XD
We are short $CRWV from 107 and just recently doubled the position at 81. Subscribe to the Noble Update for unrivaled performance. https://t.co/GhjVp50I4z
Michael Intrator belongs in jail. What an odious lying piece of garbage. $CRWV remains a core short for the Noble Update. https://t.co/TwdWQzjwn4
Excellent post. Explains why $ARE shares are down 44% over the past 12 months (and 79% over the past 5 years). https://t.co/kJbaNHubJh
I once had an argument on Reddit with a guy that refused to buy $VT because he didn't want to pay 8 bps in fees. He was worth like $20M.
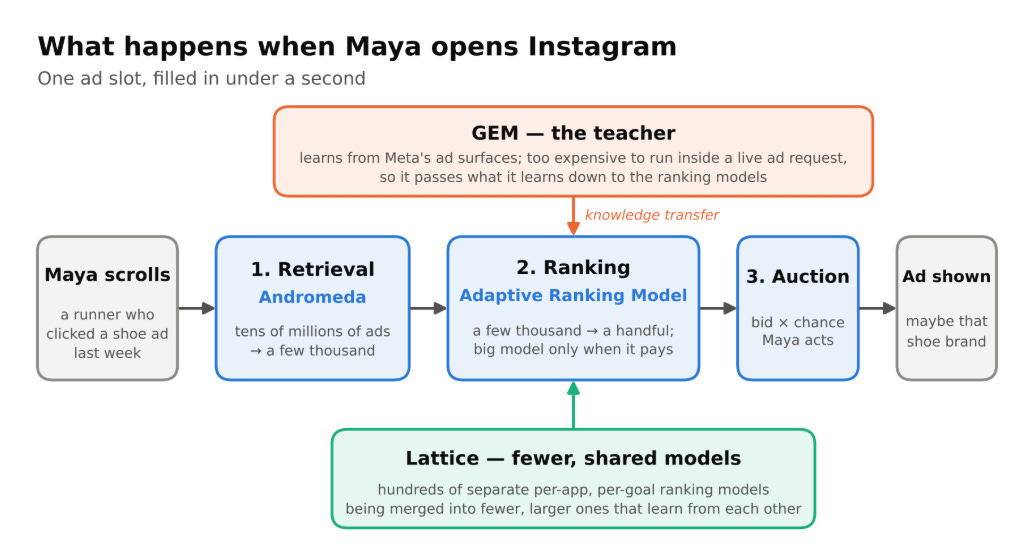
Meta’s GEM trains smaller ad-ranking models across its platforms, with Kunlun showing performance scaling predictably as compute rises.
Lanxess can force Advent to buy at least half its Envalior stake in April 2028, potentially raising about €745 million to reduce net debt.
Eagle Point Credit's NAV is down 25% YTD and shares nearly 50%, while its expense ratio climbed to 9.21% despite a 25% yield.
 Anthony Cataldo 3 clicks
SaaS companies including Salesforce, ServiceNow, CrowdStrike, Synopsys and Veeva are ranked by agentic AI progress, from pilots to…
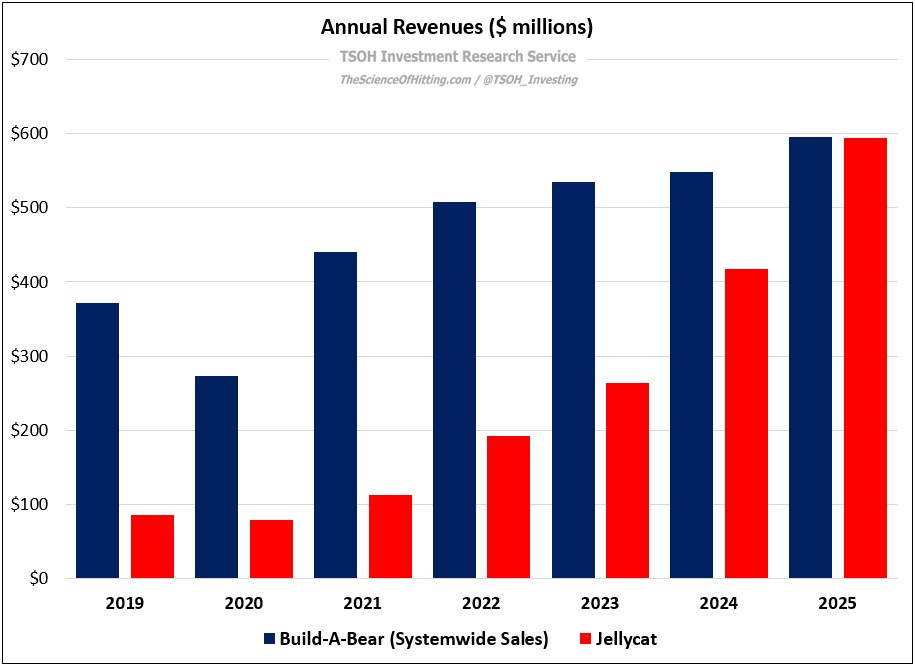
Build-A-Bear's push into prestuffed toys and broader retail distribution tests brand stretchability, but recent results warrant caution.
Lennar’s land-bank costs pressure homebuilding margins, while Flowers Foods weighs a Tastykake sale after falling branded-bread share,…
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
 Michael Fitzsimmons 4 clicks
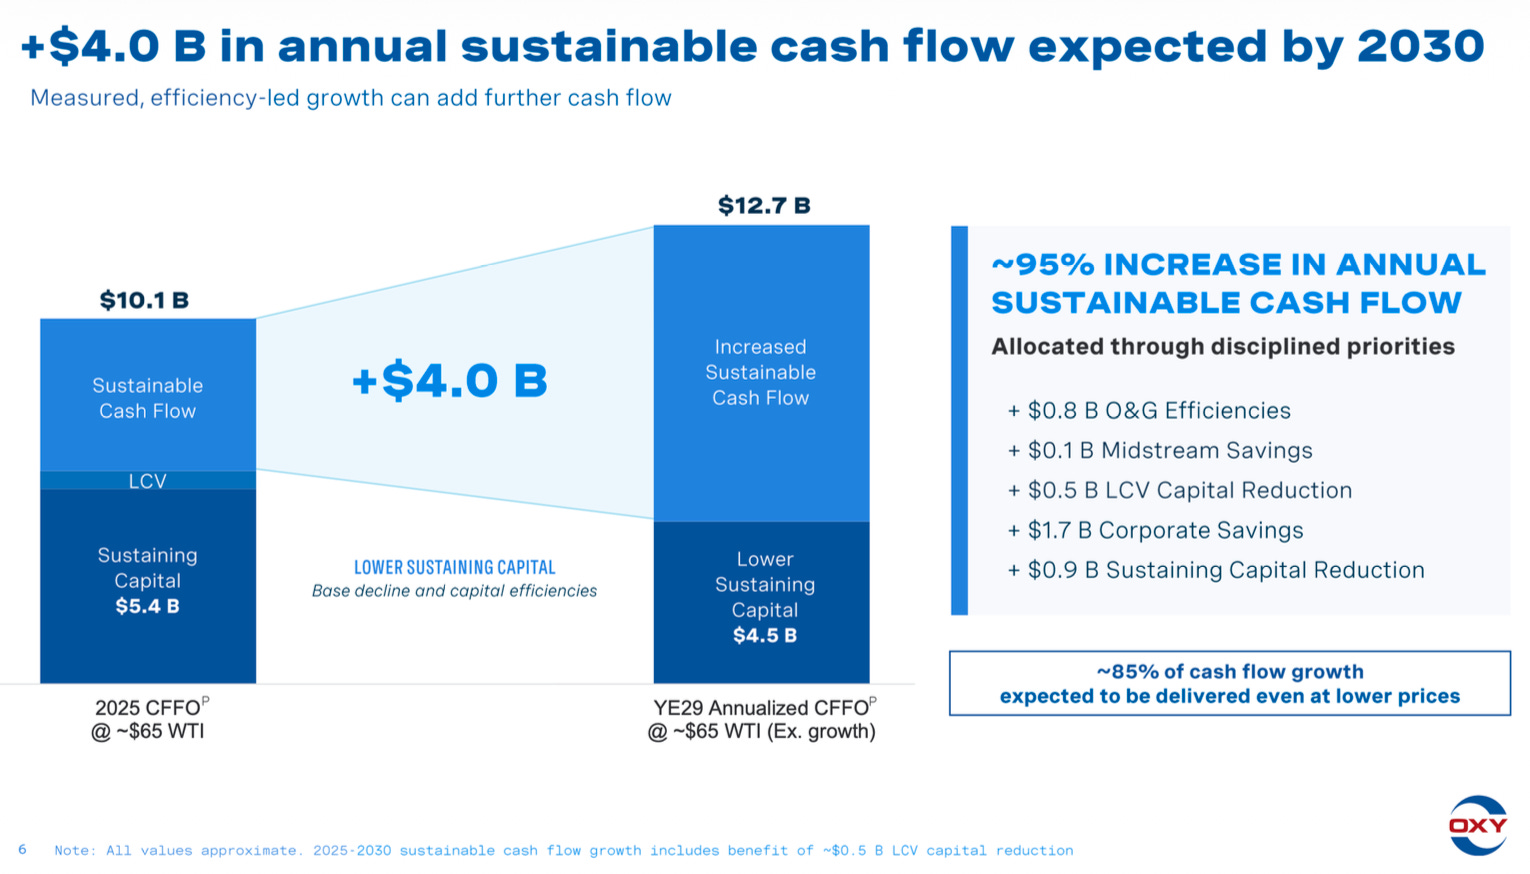
Occidental Petroleum’s debt should fall further after Q3 oil prices averaged $85 per barrel WTI and $91 Brent.
Elutia’s antibiotic-eluting surgical matrices target breast-surgery infections, with Minot Light valuing $100 million in sales at a…
 SKIN · long
SkinHealth Systems owns a dominant professional skincare consumables franchise but trades at roughly $115 million market cap and $255…
Hess Midstream, Iovance Biotherapeutics, Netlist and nine other lesser-covered stocks make this week’s Undercovered Dozen.
 The Undercovered Dozen 14 clicks
Zscaler CEO Jay Chaudhry and CFO Kevin Rubin discuss the cybersecurity company’s growth prospects and valuation.
Apple’s HomeView strategy ties Siri, privacy and smart-home control to consumer trust in its vision for the home.
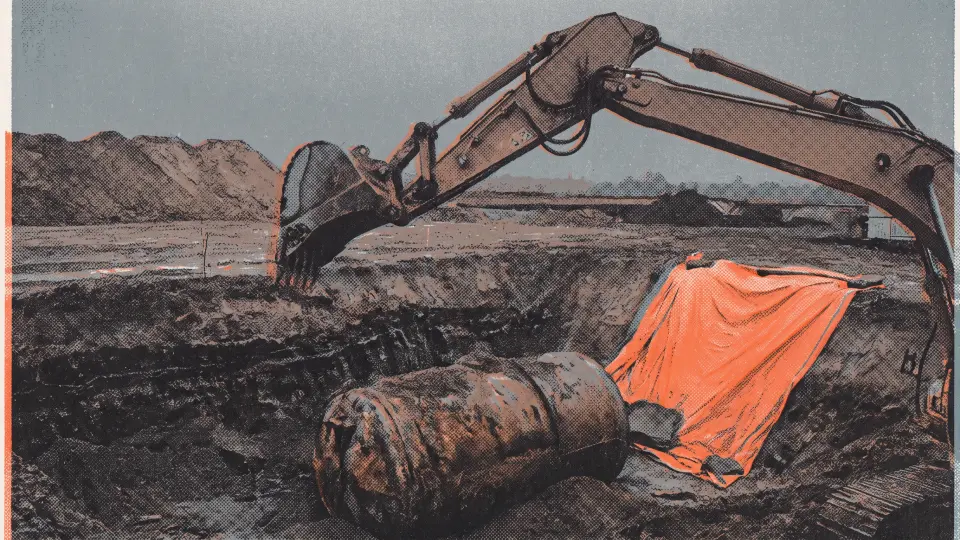
Digital Realty paid $120 million for Atlanta-area parcels including a former Army dump with buried carcinogens and military ordnance.
Wells Fargo’s Q3 EPS beat and $12.5 billion net interest income failed to move shares, while WFC.PZ preferreds yield 7.10%.
 Jeremy LaKosh 7 clicks
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper…
DigitalOcean’s CEO says the cloud company will not take on extraordinary leverage to fund its AI push.
Optical-component vendor call covers 800G and 1.6T demand, AI cluster optical density, market share, pricing and 2027 growth for Coherent,…
PayPal’s 10.3x forward earnings multiple and more than $6 billion in free cash flow frame a turnaround driven by cost cuts, Venmo and BNPL…
 JR Research 12 clicks
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.