Is The Market Turning The Page?
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
好吧,这视频也太酷了吧... $TSLA 现在居然都有飞行汽车了,感觉我们真的活在未来了 https://t.co/WjY9tP9JIF
Is it only for jet fighter pilots or will us mere mortals get training on how to land it coming off ramps like this? $TSLA https://t.co/2WaQSMobji
Real value investors own four annual reports for $MCCK. https://t.co/7Di8p87MX7
@andrew1corpora1 Some of my other large positions are Nice Info services in Korea, $VIL, $FRP.L, $AMZN
@HiddenGemsInves $CLPT - I just think over 10 years they get at very least a handful of partners to commercialization and it’s 10x higher.
CoreWeave’s 2032 notes yield over 15%, signaling a 54% default probability as borrowing costs exceed rental yields on AI infrastructure…
 Dustin Quasney 18 clicks

AppLovin rebuilt its ad model with AXON 2.0, lifting LTM revenue to about $7 billion and margins to 77% as Unity competition threatens…
Dream Finders Homes’ controlling owner borrowed against DFH stock before the homebuilder agreed to finance an acquisition with costly…
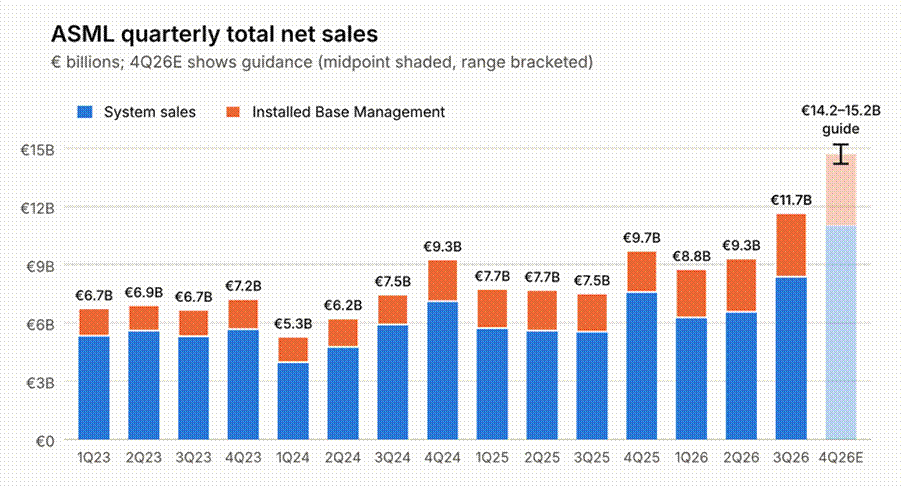
ASML reported €11.7 billion in 3Q 2026 sales, up 55%, and raised full-year guidance to €44–45 billion as AI-driven semiconductor demand…
Park Aerospace’s 11% Q2’27 sell-off overlooks sole-source PAC-3 rocket-motor materials and A320neo engine composites, with missile capacity…
UniQure's Huntington's gene therapy faces an FDA accelerated-approval decision around November 1 after three-year data met both agency…
 Bhavneesh Sharma 10 clicks
Marvell is positioning networking, optical connectivity and server-management chips as AI data centers link GPUs, custom accelerators and…
AeroVironment's $465M LOCUST laser award and earnings beat support its 2027 growth outlook despite government budget uncertainty.
 Melissa Tucker 6 clicks
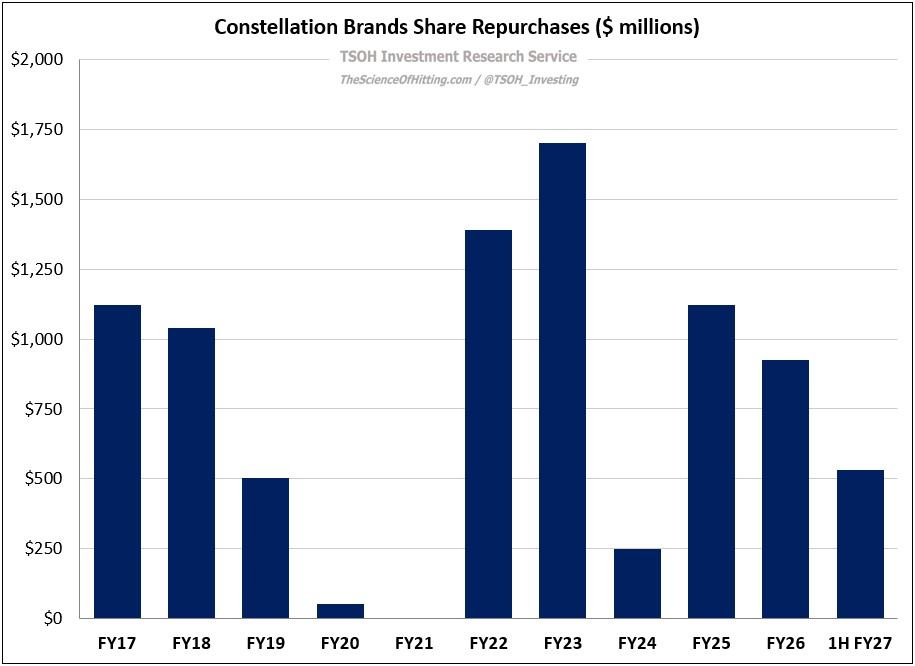
Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
Transocean’s Valaris merger clears regulators, creating a 68-rig offshore driller controlling four in 10 global drillships.
 AMADF · long
Amadeus IT Group turns long after shares fell more than 20% since a November short call.
Paramount Skydance’s debt-heavy Warner Bros. Discovery acquisition, streaming bundle pricing and alcohol-industry diversification anchor…
Blackstone Secured Lending Fund faces a likely dividend cut after its first shortfall in 28 quarters, despite 1.8% non-accruals, $2.8…
 Rubicon Associates 1 click
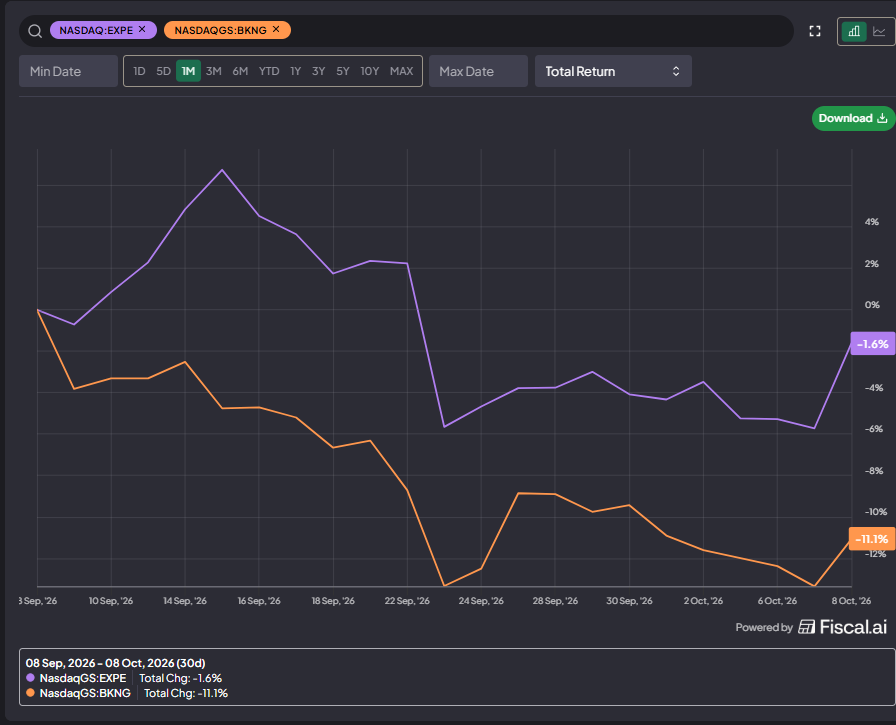
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
Alphabet pairs 17% Search growth, 82% Cloud growth and 500,000 weekly Waymo rides with a $195–205 billion AI capex plan.
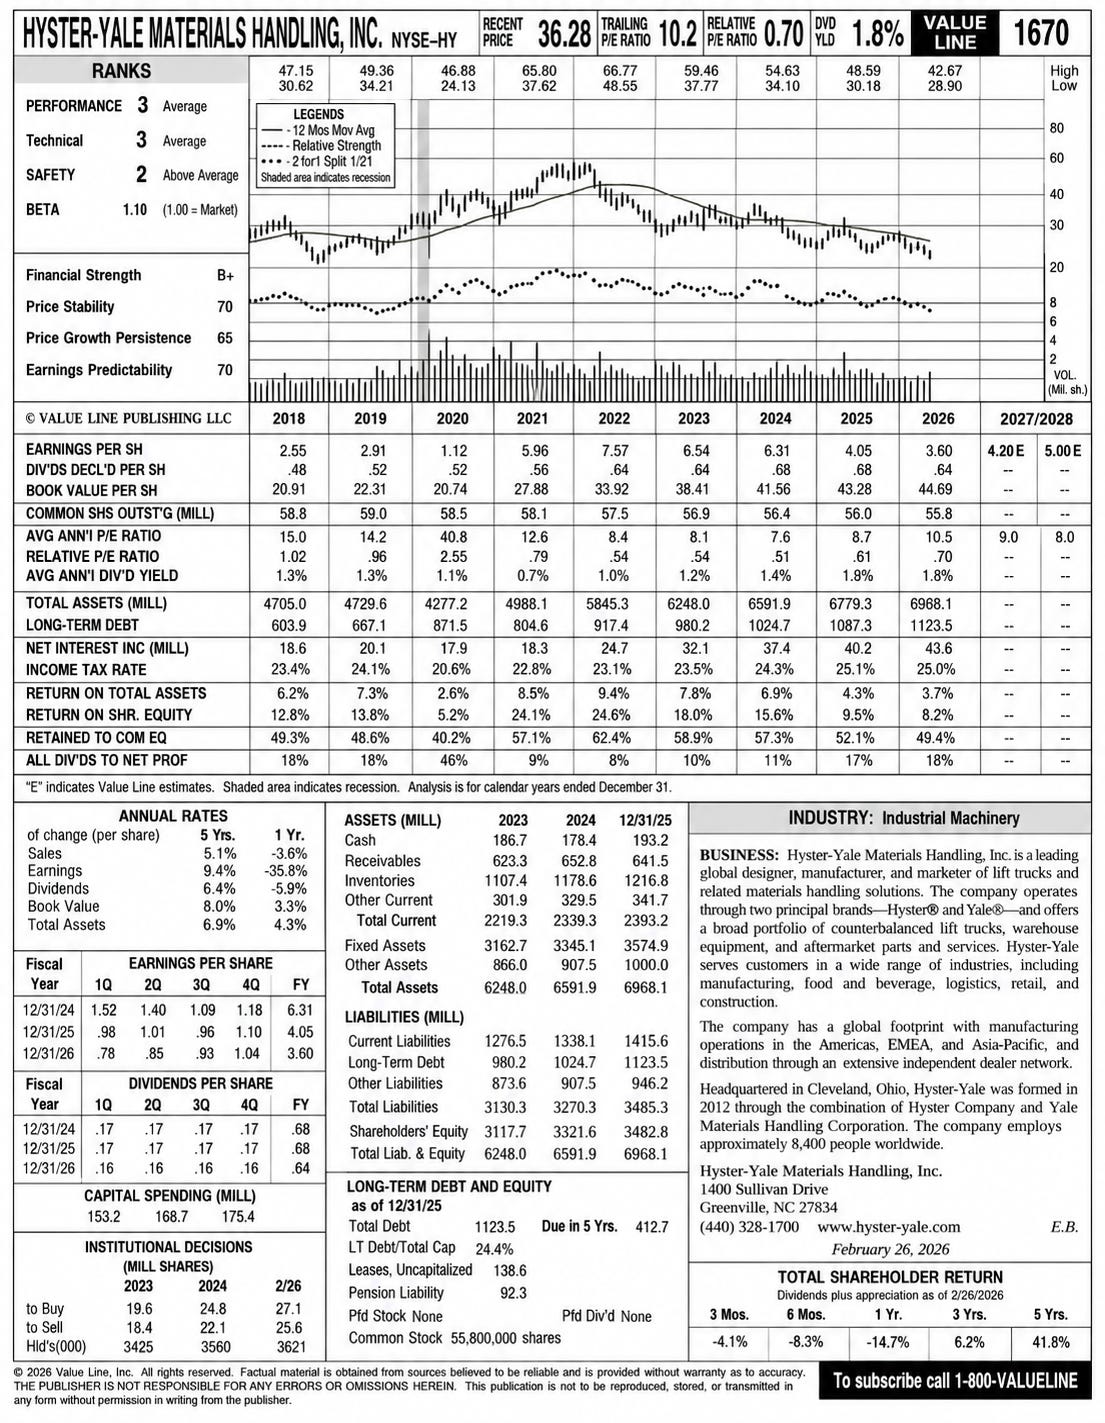
Hyster-Yale trades at 0.16 times sales as lift-truck bookings rebound and restructuring targets $85 million to $100 million in annual…
AppLovin's Ads Manager targets middle-market e-commerce advertisers as Q3 guidance calls for 47% sales growth, while legal and compute-cost…
 Jack Elias 3 clicks
Legence trades at 10.4x EV/aEBITDA with a $5.7 billion backlog, as AI data center installations drive growth and expand its maintenance…
GoDaddy’s Airo bookings run-rate rose from $10 million to $50 million in one quarter, but legacy Applications & Commerce declines still…
 Fernanda Galvez Jalil 2 clicks
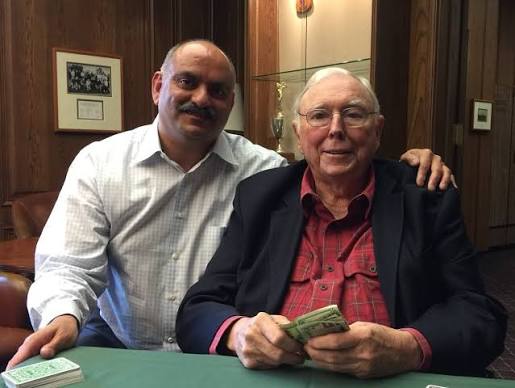
Mohnish Pabrai’s 69 quarterly filings are rebuilt into a never-sell portfolio, including Horsehead, Berkshire, Alphabet, Ferrari and…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Equity Eagle
 Eudaemon Research Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.