Is The Market Turning The Page?
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
@MrMojoRisinX @ArbSensei @Msp194 Also worth visiting what happened with Johnson & Johnson/Kenvue a little over three years ago. $JNJ $KVUE Proration in that case was 23.23%
@patientinvestor $CHTR too! ;)
A “gift” is when some person and/or organization creates a narrative misperception that creates a dislocation in an equity. Dario did it with $CORZ / $CIFR this weekend. Bloomberg News continues to do it with $OWL https://t.co/z7VfaqffDk
What price does $GFL get acquired for?
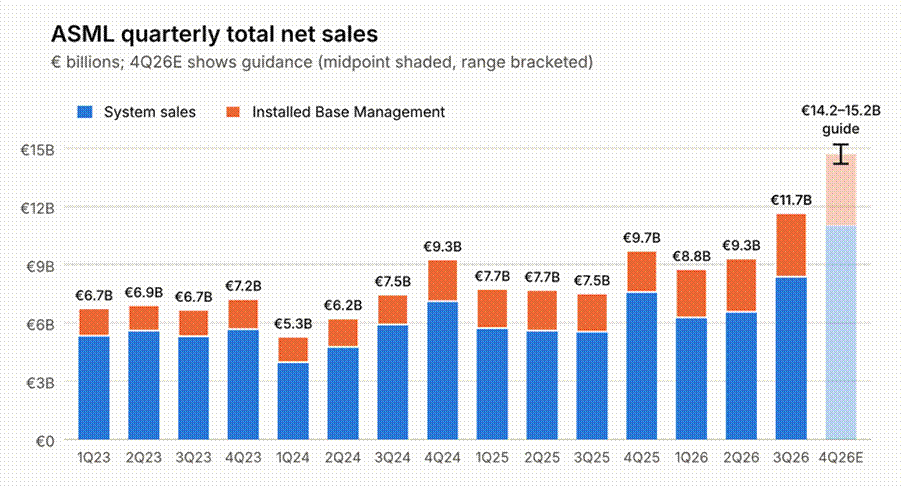
ASML reported €11.7 billion in 3Q 2026 sales, up 55%, and raised full-year guidance to €44–45 billion as AI-driven semiconductor demand…
Berkshire Hathaway trades at 1.46 times book as reinsurance pricing pressure, softer P&C, concentrated equities and cash weigh on its…
 Pearl Gray Equity and Research 3 clicks
Marvell is positioning networking, optical connectivity and server-management chips as AI data centers link GPUs, custom accelerators and…
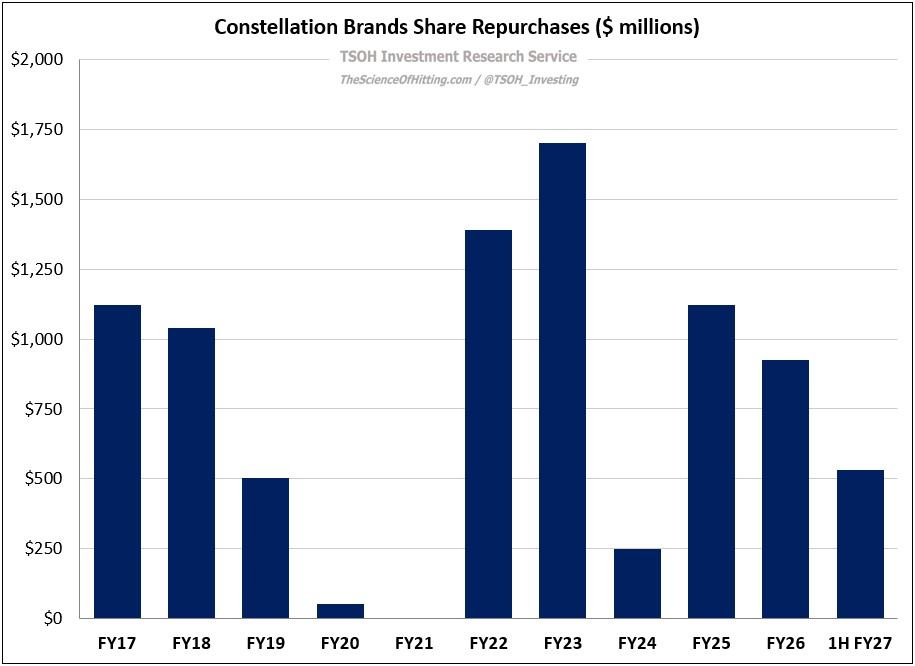
Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
TSMC reported excellent Q3 results, guided Q4 revenue growth higher and saw its shares slip despite strong AI-driven earnings momentum.
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI…
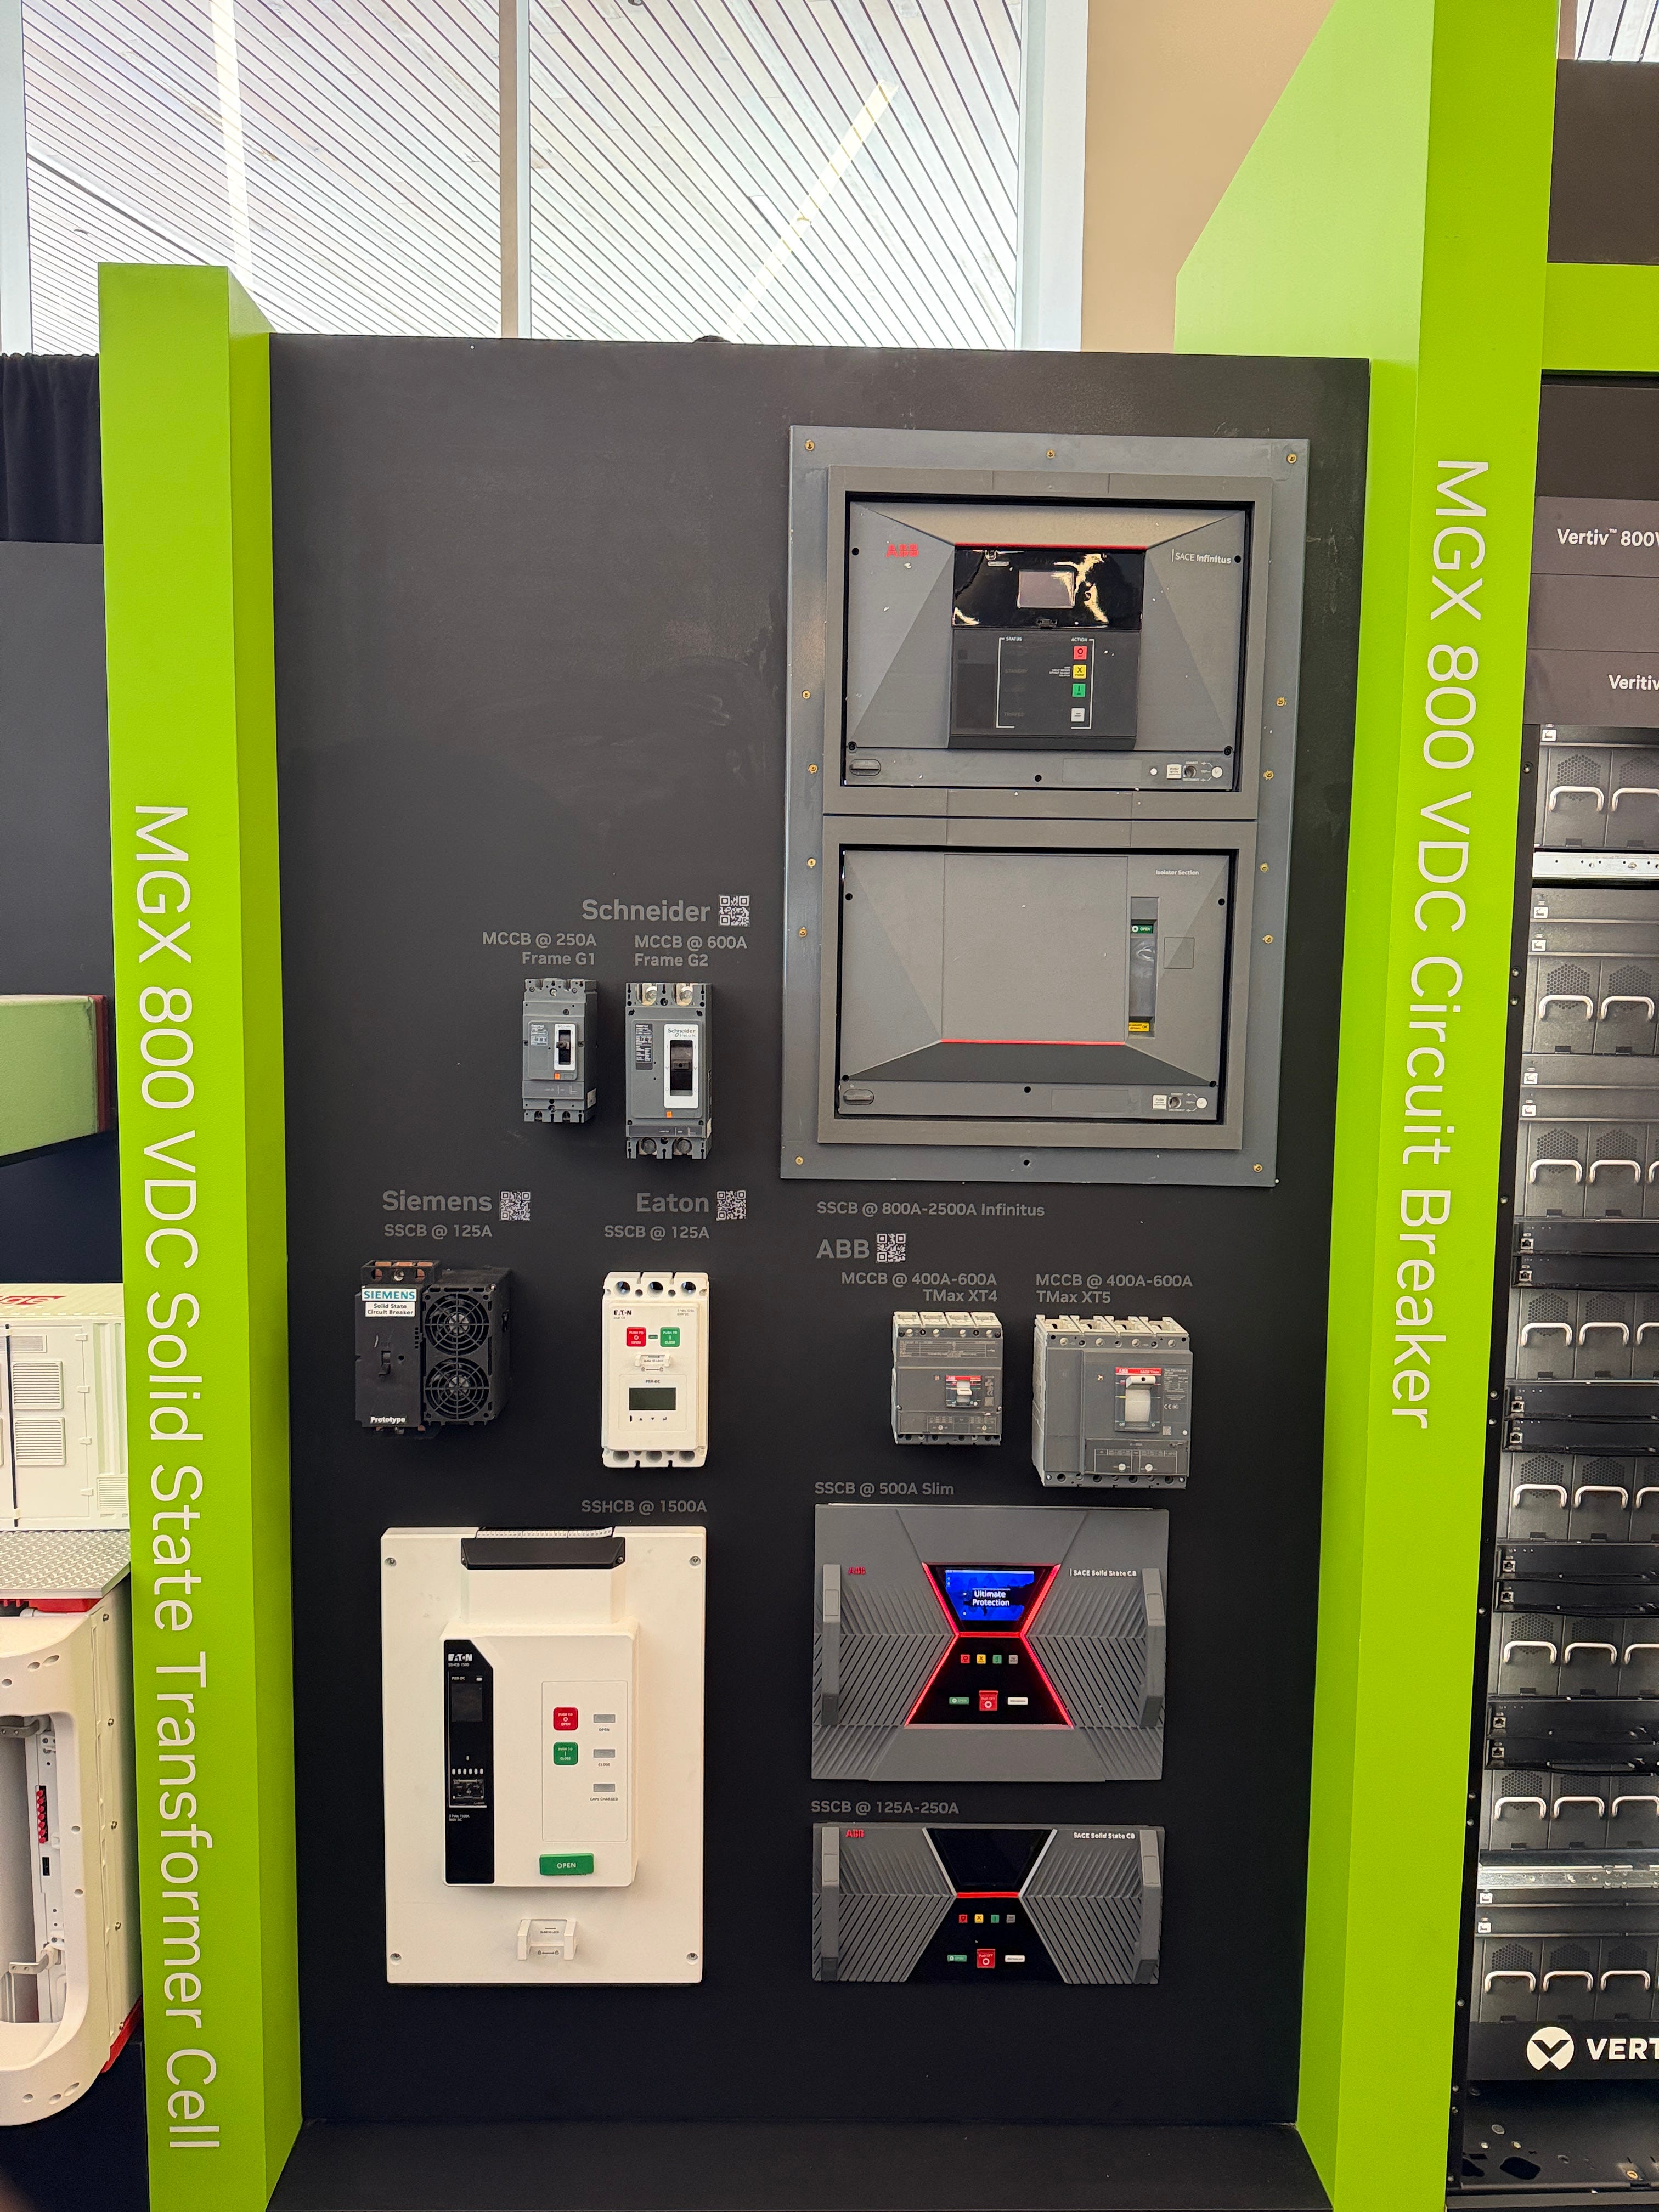
Nvidia’s Ian Buck says CUDA’s software ecosystem, GPU flexibility and annual Vera Rubin upgrades lower token costs as agentic AI pushes…
CoreWeave faces fresh skepticism as another AI trade selloff collides with bullish defenses of the company.
Ari Emanuel discusses AI’s impact on Hollywood, live events, social networks and the future of advertising.
RTX’s $289 billion backlog, including $119 billion in defense, supports growth from defense contracts and commercial aerospace aftermarket…
 Blake Winiecki 4 clicks
Tesla’s Q2 revenue rose 26%, but operating margin fell to 1.4% and free cash flow was negative $1.1 billion as valuation reached 215x…
 Julia Ostian 6 clicks
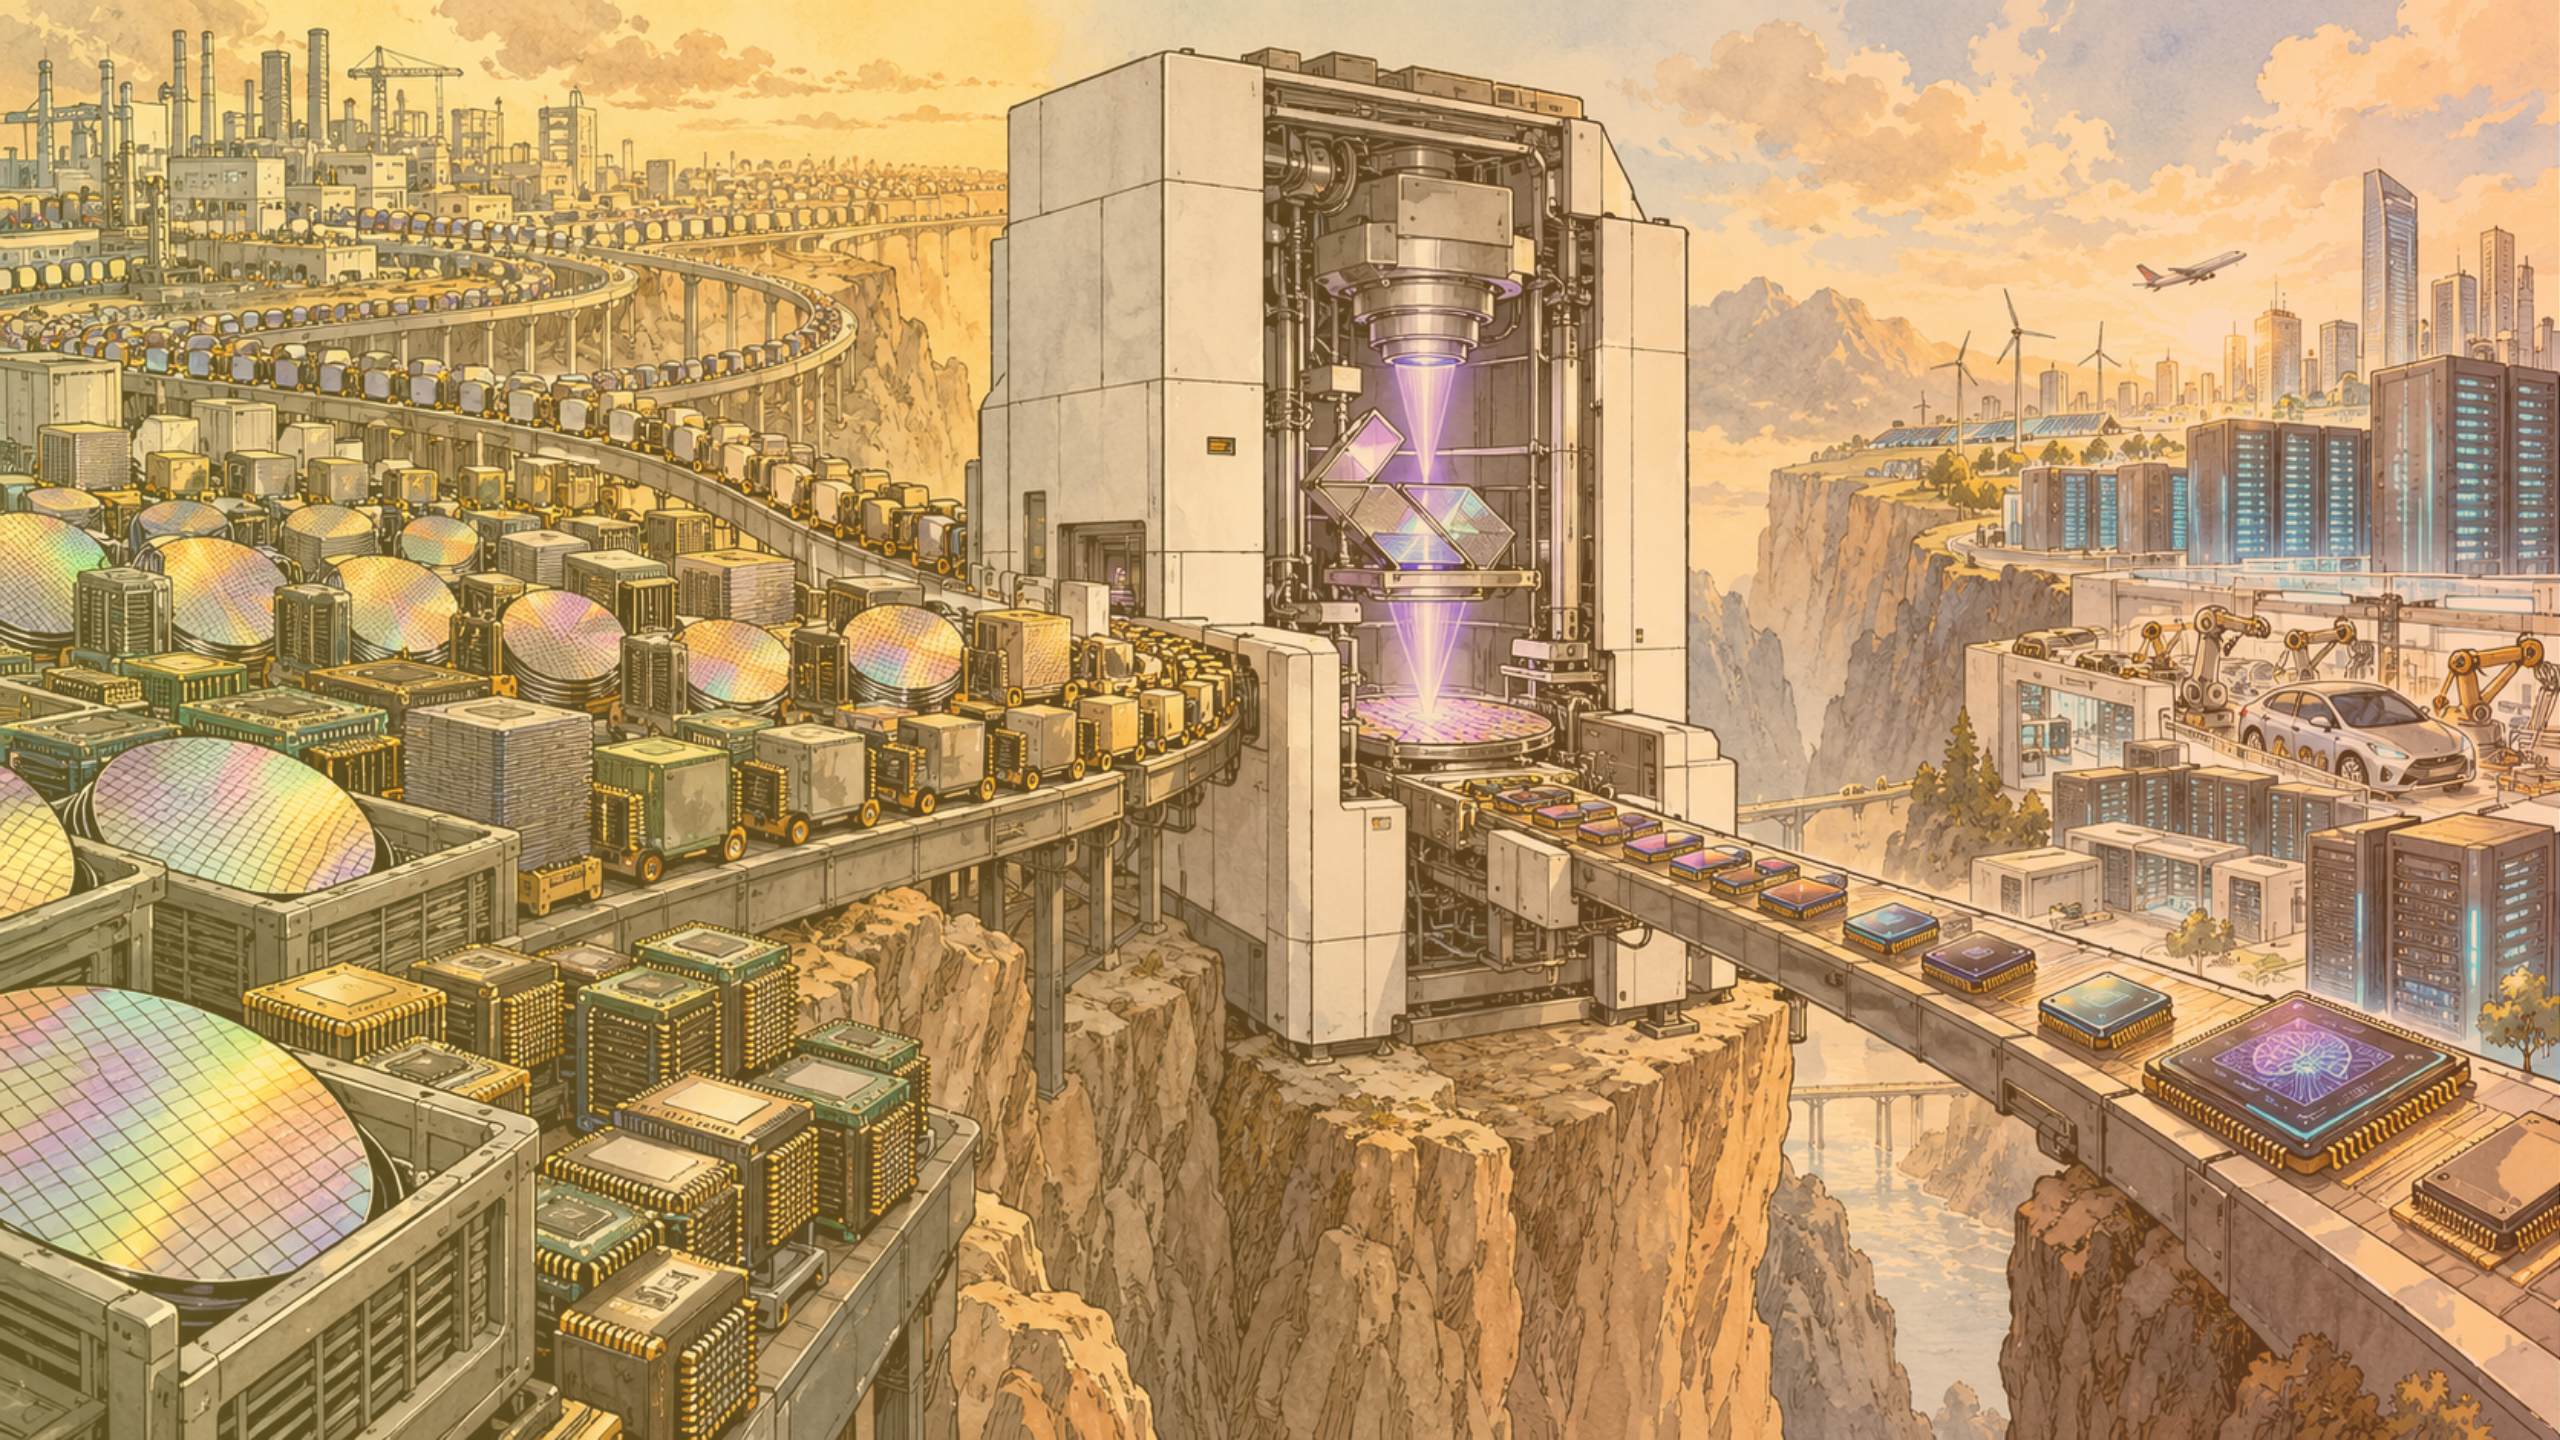
ASML’s €11.7 billion quarter benefited from €3.3 billion in installed-base sales and operating leverage, while the MATCH Act threatens…
Visa’s network economics support long-term compounding, but a 1.7–1.8 forward PEG and risks to high-margin payment revenues limit near-term…
 C Jessen 36 clicks
Applied Materials leads wafer-fab deposition and ranks third in etch, positioning it for tougher 3D chip manufacturing as investors weigh a…
First Tracks Biotherapeutics’ ANB033 posted stronger Phase 1b celiac efficacy than Teva’s IL-15 inhibitor, with $168 million funding…
 Equity Eagle 8 clicks
Howmet Aerospace is framed as a beneficiary of turbine and aircraft-engine demand, while J.B.
Lennar cut build times to 116 days and adopted an asset-light land model, while gross margin fell to 15.8% from 27.5% as land costs rose.
Lennar grew from a Miami builder into one of America’s two largest homebuilders, controlling land largely through options and land banks…
Lennar’s second audio program examines the homebuilder’s business for professional investors and housing analysts.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.