Raging Capital Ventures on X
@TarekAntaki I bought $CHTR stock today as well, Godspeed!
NASDAQ
CHTR
13 stories
$13B Market cap · 2026-10-07
@TarekAntaki I bought $CHTR stock today as well, Godspeed!
@aurelius28 @fundingregime $CHTR comparison doesn't make much sense imo. CHTR faces massively increased competition, high (detrimental) margins, no sticky contracts+capital intensive. Debt would take a decade to pay off if status quo. FIS could pay off its debt in ~5-6 years, changes are glacial.
It's always weird when analysts don't address the elephant in the room - you'd think things were going splendid at $CHTR and they were running with net cash: https://t.co/NPBWGrKxuQ
@KoyfinCharts $CHTR buybacks
But if returns on capital are declining for everyone, the choice is whether to eat or to be eaten? $T is willing to subsidize fiber as a loss leader to protect their wireless margins. $CHTR / $CMCSA are likewise willing to give away wireless to protect their broadband margins… which comes back to the question: which is stickier, your phone or broadband line? I think $CMCSA works because of the spin unlock and sheer strength of their balance sheet. $CHTR is a very long dated call option with more risk, but much more upside if broadband losses attenuate and/or they allocate capital intelligently (although $CHTR’s balance sheet is more levered, there is tremendous optionality in its duration, cost and structure).
@patientinvestor $CHTR too! ;)
@BigIdeasCapital I agree with the logic and own both $CHTR and $CMCSA, but what if cell phones are stickier than broadband lines? $T’s fiber “loss leader” offering might be more attractive than cable’s cheap wireless service?
@retaox The $CHTR broadband offering is much more competitively priced today due to tech upgrades, limited pricing increases in recent years, aggressive retention incentives, and investments into the video/wireless bundle.
Not the greatest quarter but no change in my $CHTR view, although I did sell some of my October calls today. Owning common and LEAPs are most interesting now. The Cox acquisition should close in mid- to late-August, which I view as a catalyst for analysts and investors to revisit their models. $CHTR is now trading at around 2x pro forma 2028 FCF per share, with incredible balance sheet optionality (which they have started to monetize via buybacks and swaps at a discount). I also think $CHTR has front-loaded a lot of ARPU pain and invested heavily to stabilize video in recent years. While broadband will remain challenged, I don’t believe the worst case scenarios and think wireless growth and pricing can provide a valuable offset.
@satsfilip Fixed — at around $353 per $CHTR share / 23% of company.
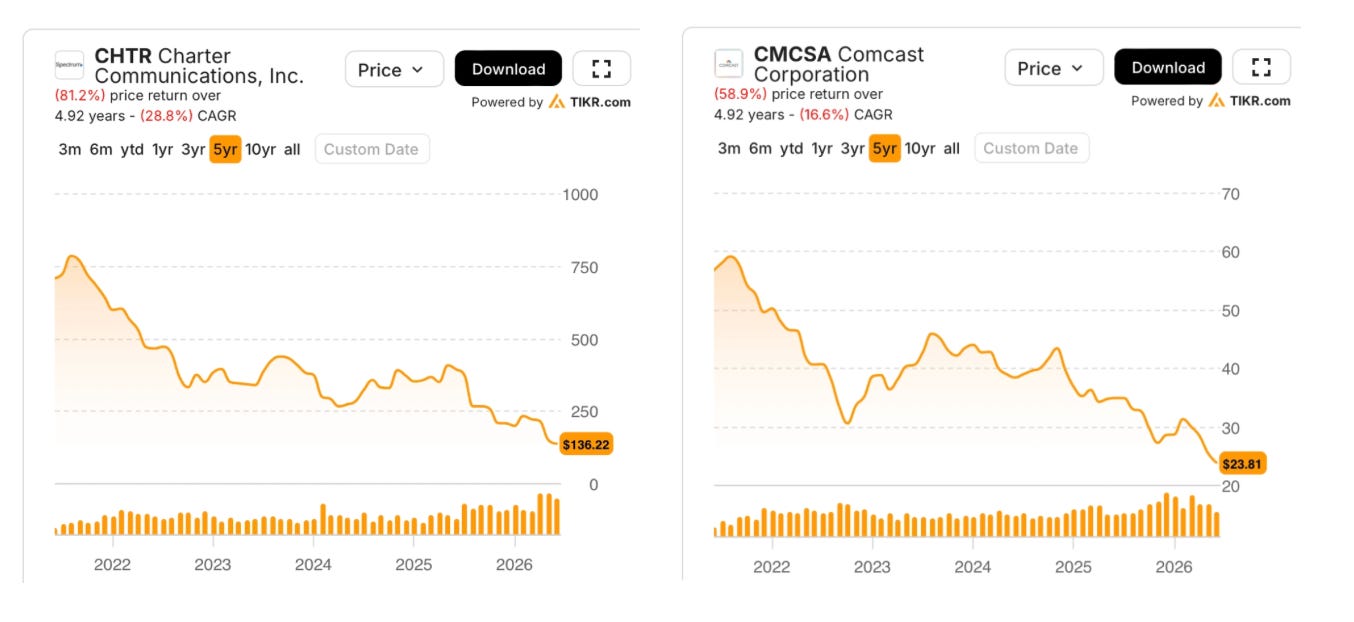
Charter’s $11 billion to $8 billion capex plan may not be durable as copper-network upgrades face fiber competition, while CHTR shares have…
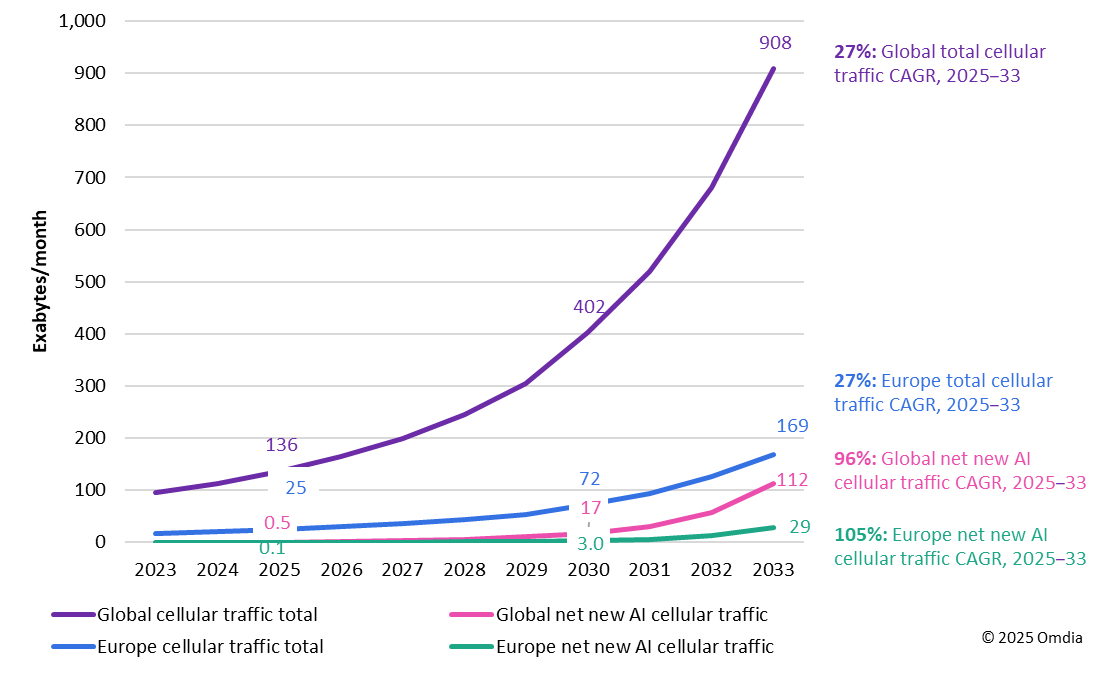
A U.S. last-mile telecom network trades at 3.9x trailing earnings and 5.7x TEV/EBITDA, with AI traffic growth, capex normalization, merger…

Cable stocks face renewed broadband share-loss concerns from LEO satellites, while AI links cover Microsoft, Google, Amazon, Anthropic and…
Letters that discuss CHTR.
Companies the stories above are also about, besides CHTR.