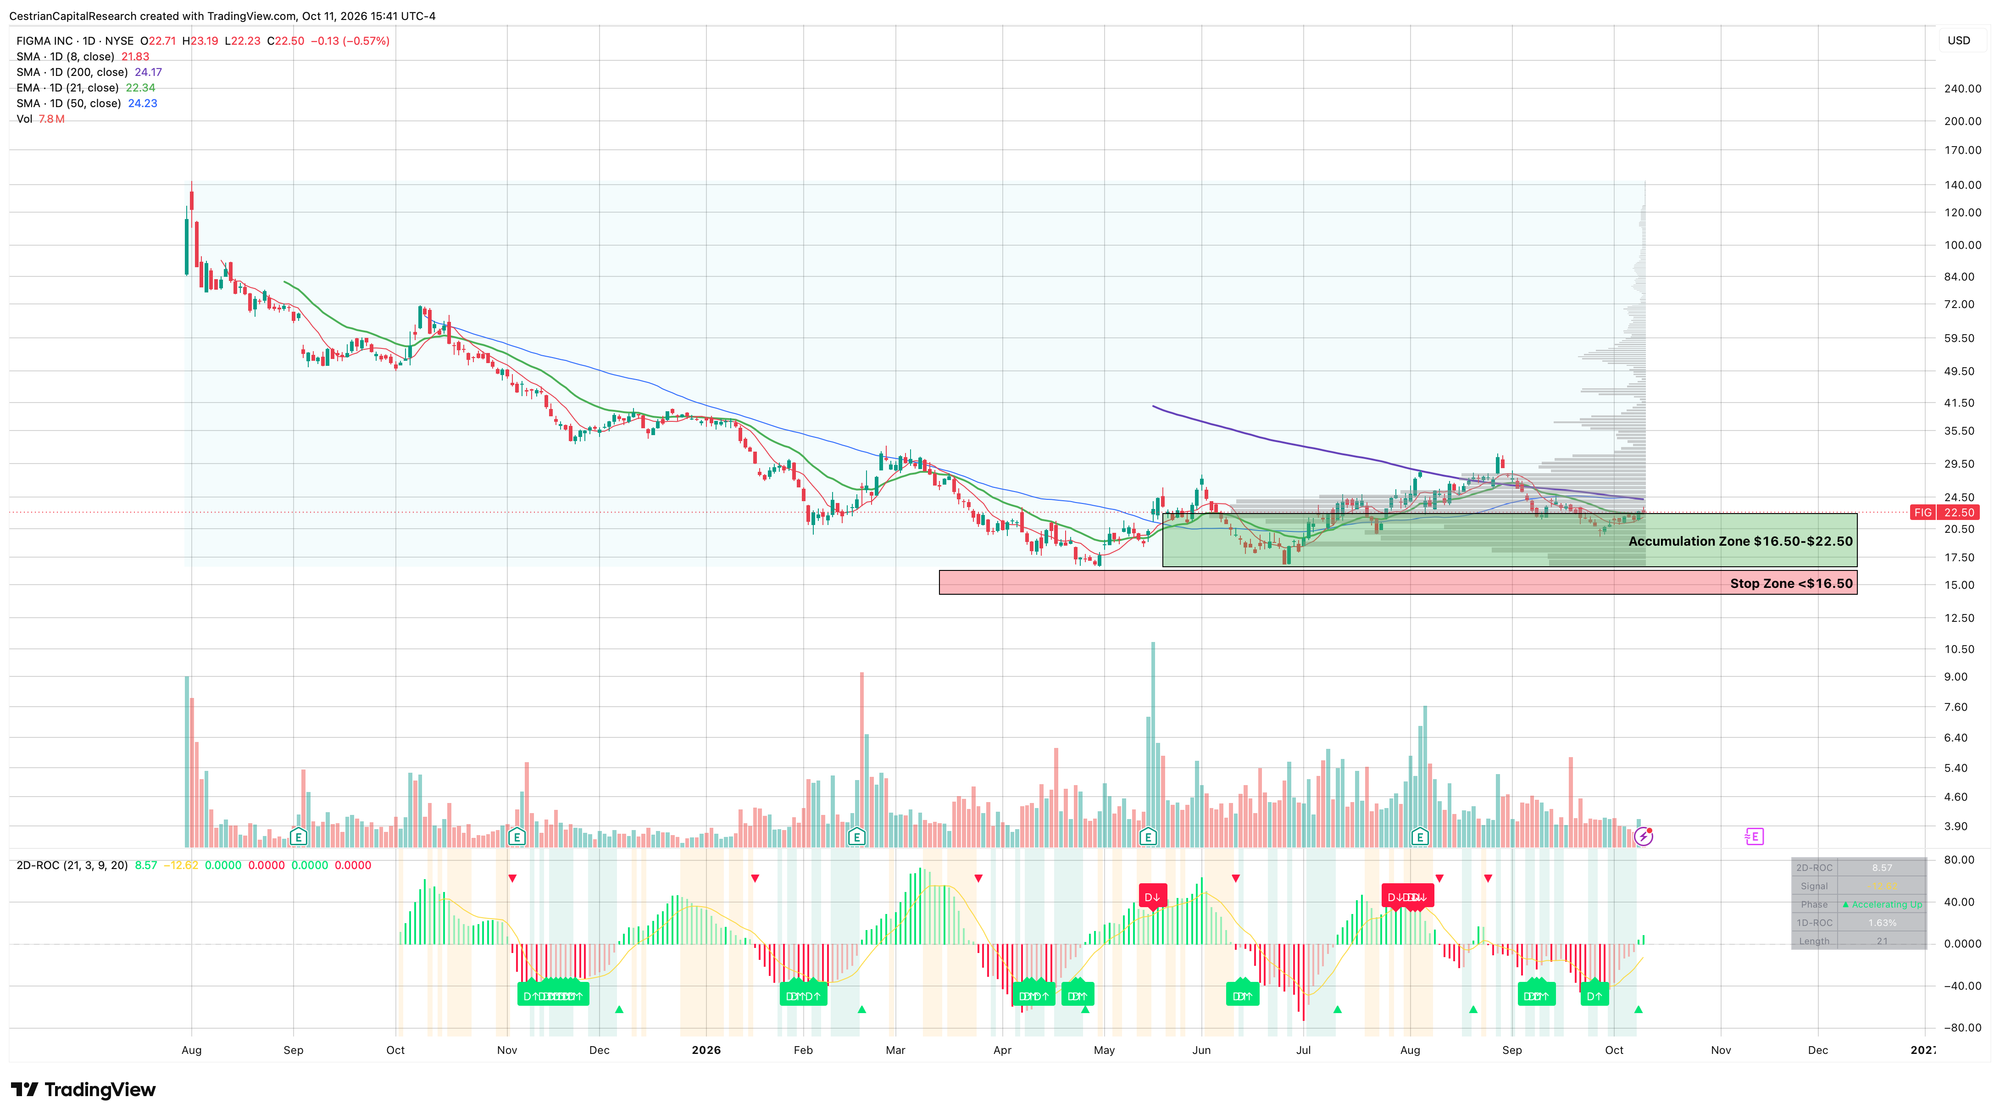
Figma (NYSE: FIG) Stock Rating: Accumulate After Q2 FY12/26 Earnings
Figma’s Q2 revenue rose 48% to $370.1 million as AI credit adoption lifted retention to 136%; FY2026 revenue guidance increased to $1.463 billion to $1.467 billion.
Figma’s Q2 revenue rose 48% to $370.1 million as AI credit adoption lifted retention to 136%; FY2026 revenue guidance increased to $1.463 billion to $1.467 billion.
Continue reading here for the U.S. AP1000 push and the new plant $BWXT is weighing: https://t.co/bPIYua98gd
M&A idea: $BCO closing on cash + stock acquisition of $NATL early 1Q27 Implied BCO market cap ~$5.5B post-close on $1B pro-forma FCF = 5.5x Leverage jumps to ~3.4x so they'll likely spend a few years balancing delevering No real arb situation, but worth watching...
Newest out. Imperial Brands: Collapse $IMBBY $LOG $MO $PM $BTI $STG $HAYPP https://t.co/n7OxkJ7DQj
Inter & Co, Brazil’s second-largest neobank, grew over 20% with controlled delinquencies and 15% book-value compounding while trading at…
Coupang’s November 2025 cybersecurity breach tests whether a selloff is temporary despite its 28% Korean e-commerce share, 14 million-plus…
DHT Holdings earns more than $1 million daily from VLCC tankers, with Q3 EPS near $1.25 and a 20% annualized yield as spot rates outpace…
 Melissa Tucker 4 clicks
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
AMD is rated Hold ahead of Q3 FY2026 earnings after Q2 revenue rose 50% to $11.5 billion, led by 107% Data Center growth.
Meta’s Muse saw downloads fall 8.1% week over week, while daily user additions slowed 62.4% to about 74,000 in early October.
Deckers trades at 11x forward earnings with $1.6 billion cash, no debt and aggressive buybacks, as HOKA growth and UGG profitability…
 TQP Research 5 clicks
Synopsys moved to Distribute after Q3 revenue rose 42% on Ansys, while organic growth was 7% and the stock traded at 11.1 times trailing…
Paramount Skydance’s debt-heavy Warner Bros. Discovery acquisition, streaming bundle pricing and alcohol-industry diversification anchor…
Blackstone Secured Lending Fund faces a likely dividend cut after its first shortfall in 28 quarters, despite 1.8% non-accruals, $2.8…
 Rubicon Associates 1 click
 G · long
Genpact operates workflows AI is designed to automate and can deploy AI across its existing operations.
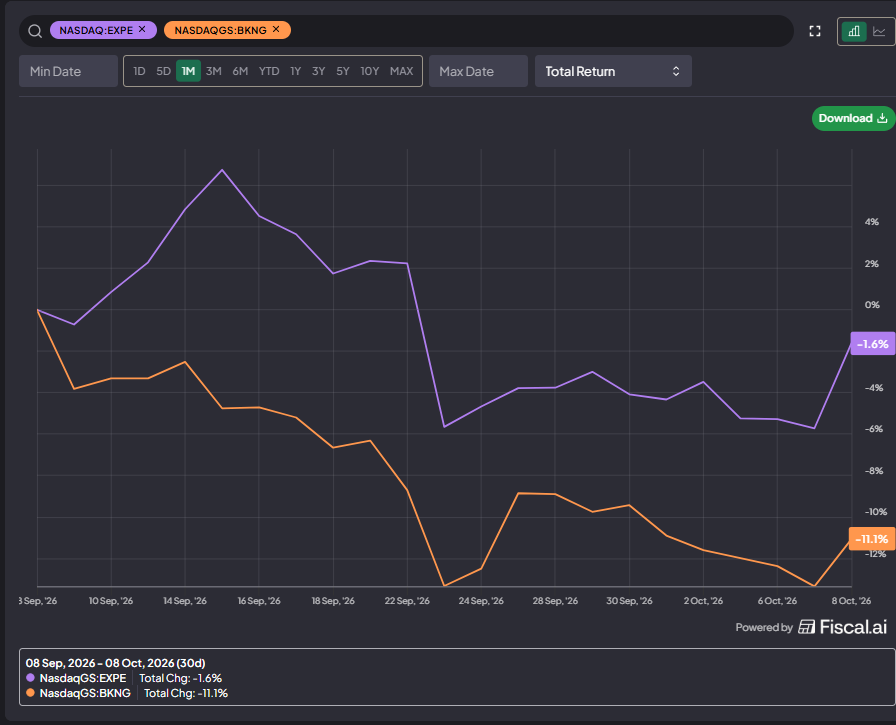
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
Alphabet pairs 17% Search growth, 82% Cloud growth and 500,000 weekly Waymo rides with a $195–205 billion AI capex plan.
AppLovin's Ads Manager targets middle-market e-commerce advertisers as Q3 guidance calls for 47% sales growth, while legal and compute-cost…
 Jack Elias 3 clicks
Legence trades at 10.4x EV/aEBITDA with a $5.7 billion backlog, as AI data center installations drive growth and expand its maintenance…
GoDaddy’s Airo bookings run-rate rose from $10 million to $50 million in one quarter, but legacy Applications & Commerce declines still…
 Fernanda Galvez Jalil 2 clicks
Mohnish Pabrai’s 69 quarterly filings are rebuilt into a never-sell portfolio, including Horsehead, Berkshire, Alphabet, Ferrari and…
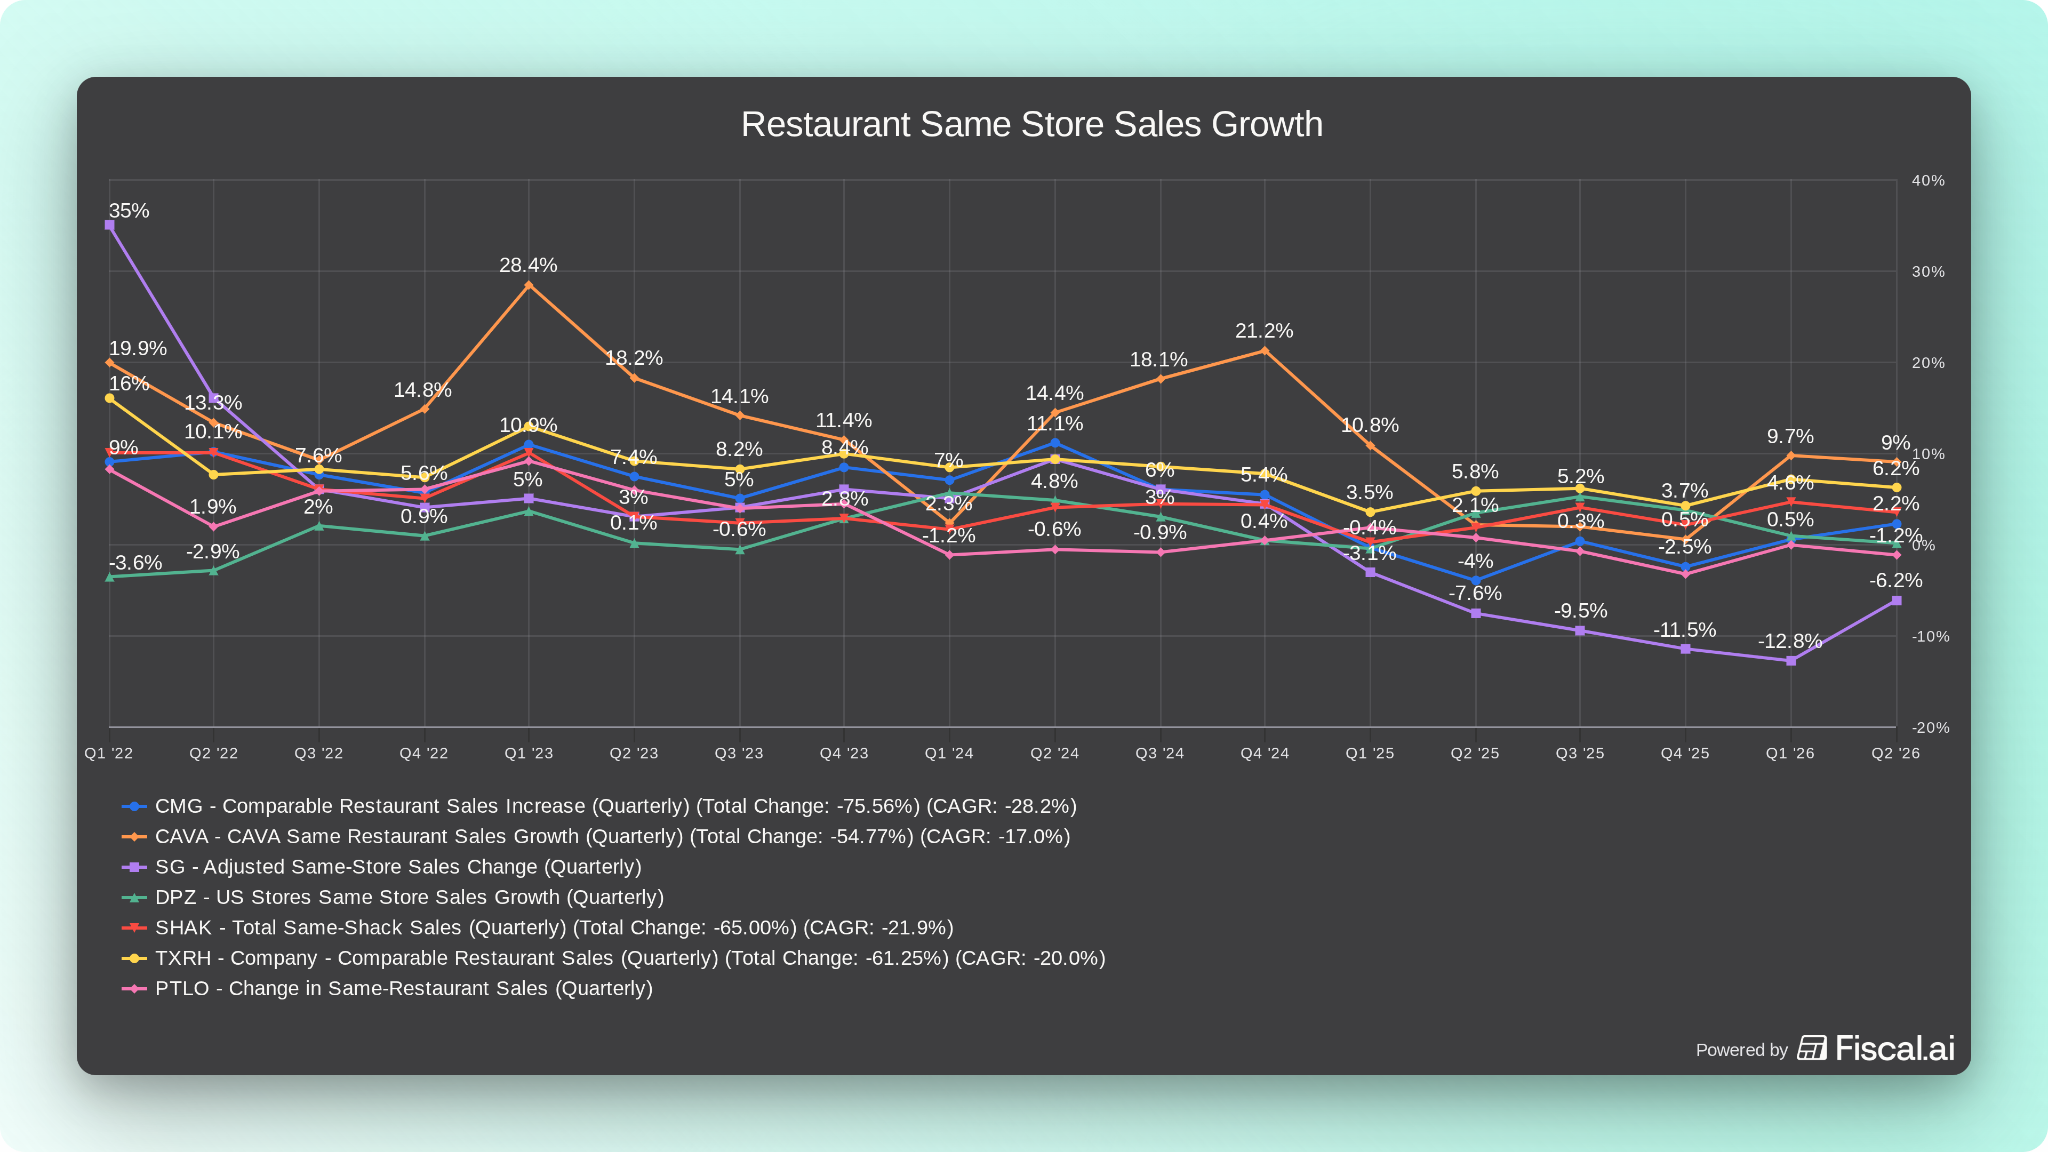
Cava’s $3 million AUVs, 25.1% restaurant margins and sector-leading same-store sales support its expansion case as awareness rose from 40%…
Robinhood’s AI agents, 24/7 equity trading and 10:1 crypto perpetual futures encourage higher retail trading velocity, leverage and…
Lowe’s trades at 15x earnings after a 23% decline, with weak housing and high rates pressuring growth while inventory discipline supports…
 Seeking Profits
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Equity Eagle
 Eudaemon Research Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.