New Position (ONON): Game is On
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S. consumer weakness and China growth.
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S. consumer weakness and China growth.
A “gift” is when some person and/or organization creates a narrative misperception that creates a dislocation in an equity. Dario did it with $CORZ / $CIFR this weekend. Bloomberg News continues to do it with $OWL https://t.co/z7VfaqffDk
What price does $GFL get acquired for?
You know it’s gonna be a good day when even $AMZN is getting bought
@Fwenen $QXO vs. $XHB 🤷♂️ https://t.co/ueiuutNvlX
Intuit’s $21.4 billion software franchise faces AI-driven pricing pressure in tax and accounting, even as QuickBooks and TurboTax retain…
Uber’s valuation is framed as undervaluing ride-hailing and robotaxi growth, while record institutional ownership offsets concerns over…
 The J Thesis 3 clicks
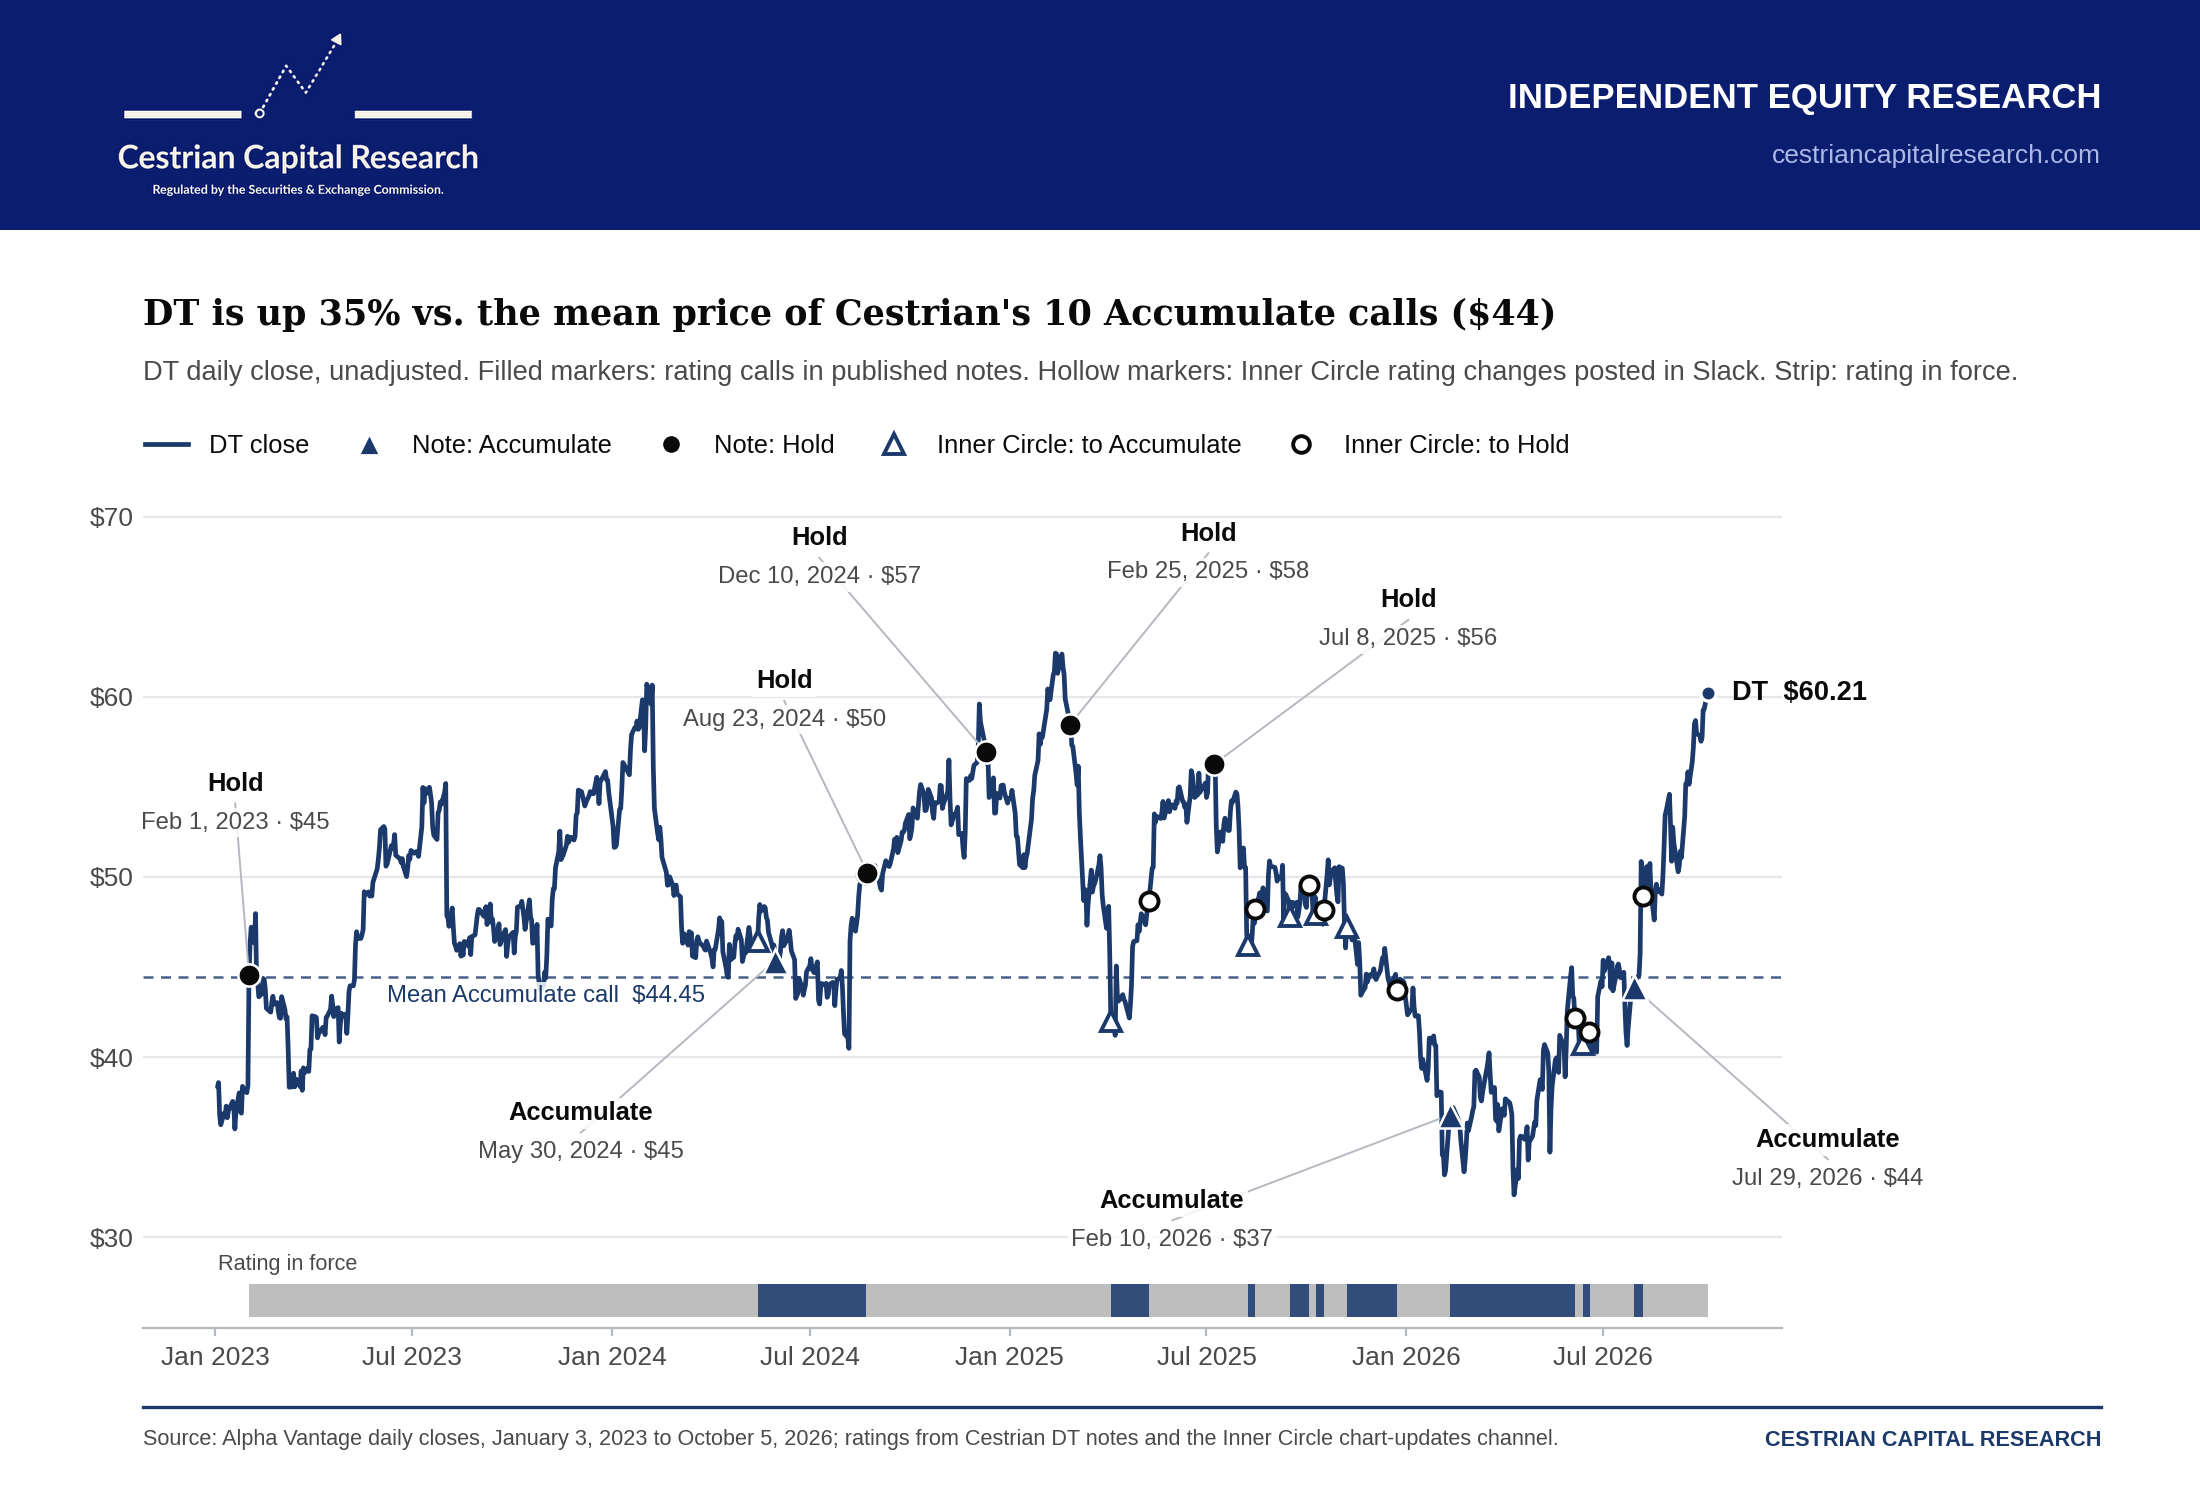
Dynatrace is rated Distribute after a 90% rally to $60.21 nears $62 resistance, while revenue and RPO growth decelerate ahead of November…
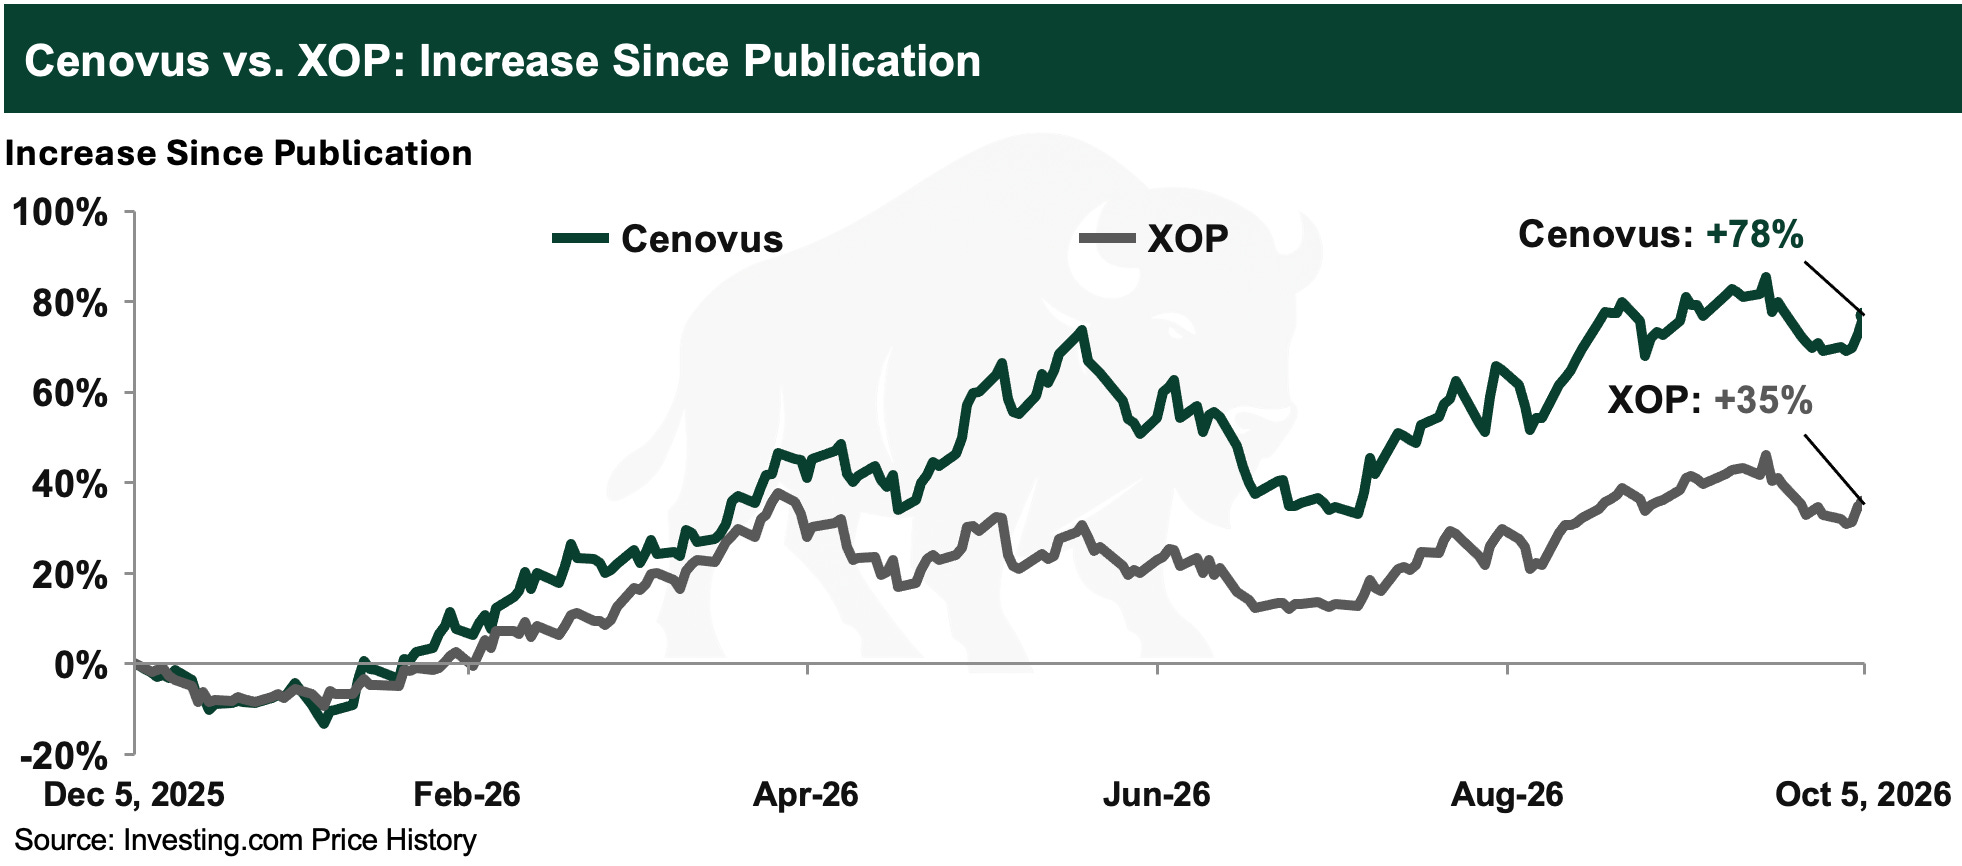
Cenovus Energy, up 78% in 10 months, is sold after agreeing to buy Athabasca Oil for $5.7 billion at a rich valuation.
Canterra Minerals increased Lundberg indicated tonnage 55% to 26.1Mt, with 226.2Kt of contained copper equivalent, supporting a Buchans…
Franco-Nevada bought 10.0 million Kenorland shares, a 12.4% stake, for C$22.2 million in a secondary transaction that issued no new shares.
GFL Environmental’s take-private bids reportedly fall within $50 to $55, with a top-of-range offer likely needed to secure shareholder…
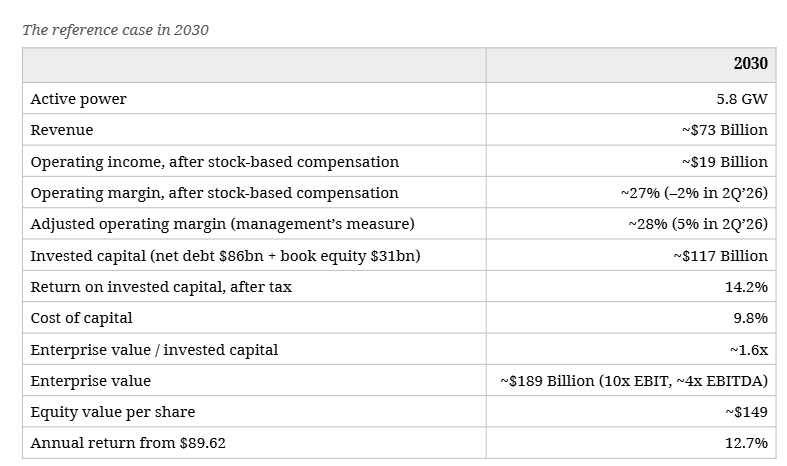
CoreWeave’s compute-selling economics face a narrowing margin of safety if new capacity closes today’s AI supply-demand gap.
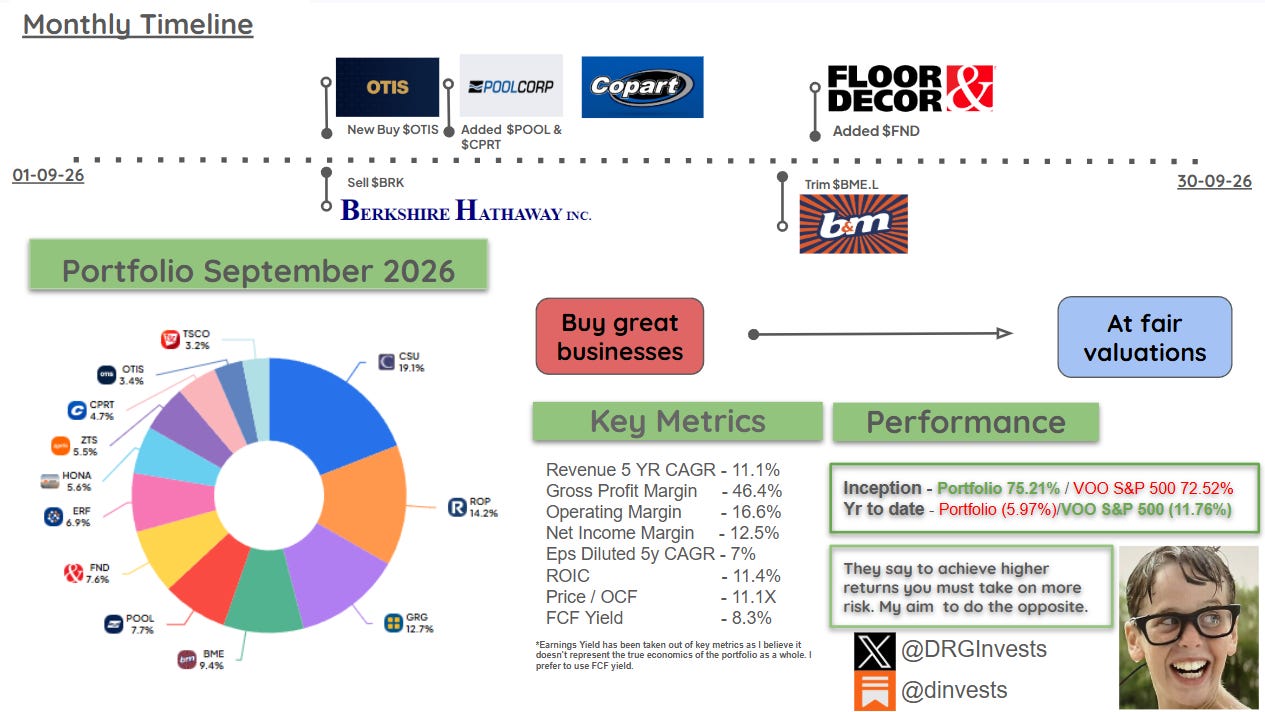
Portfolio added Otis Worldwide in the mid-$60s, increased Pool, Copart and Floor & Decor, and sold Berkshire Hathaway.
Ciena’s optical networking equipment sales to stronger telecom customers underpin a 2027 long thesis, unlike its 2000-era boom.
 Marc Gerstein 2 clicks
 IBIT · long
IShares Bitcoin Trust ETF (IBIT) is presented as a high-conviction Bitcoin position with attractive risk-reward.
Brazilian fintechs NU, INTR and PICS stand to benefit from a Bolsonaro-led runoff surprise that lowers fiscal risk premiums, rates and the…
Meta and Alphabet can fund AI with core profits, proprietary data and in-house infrastructure, giving META and GOOG pricing and…
 Cain Lee 2 clicks
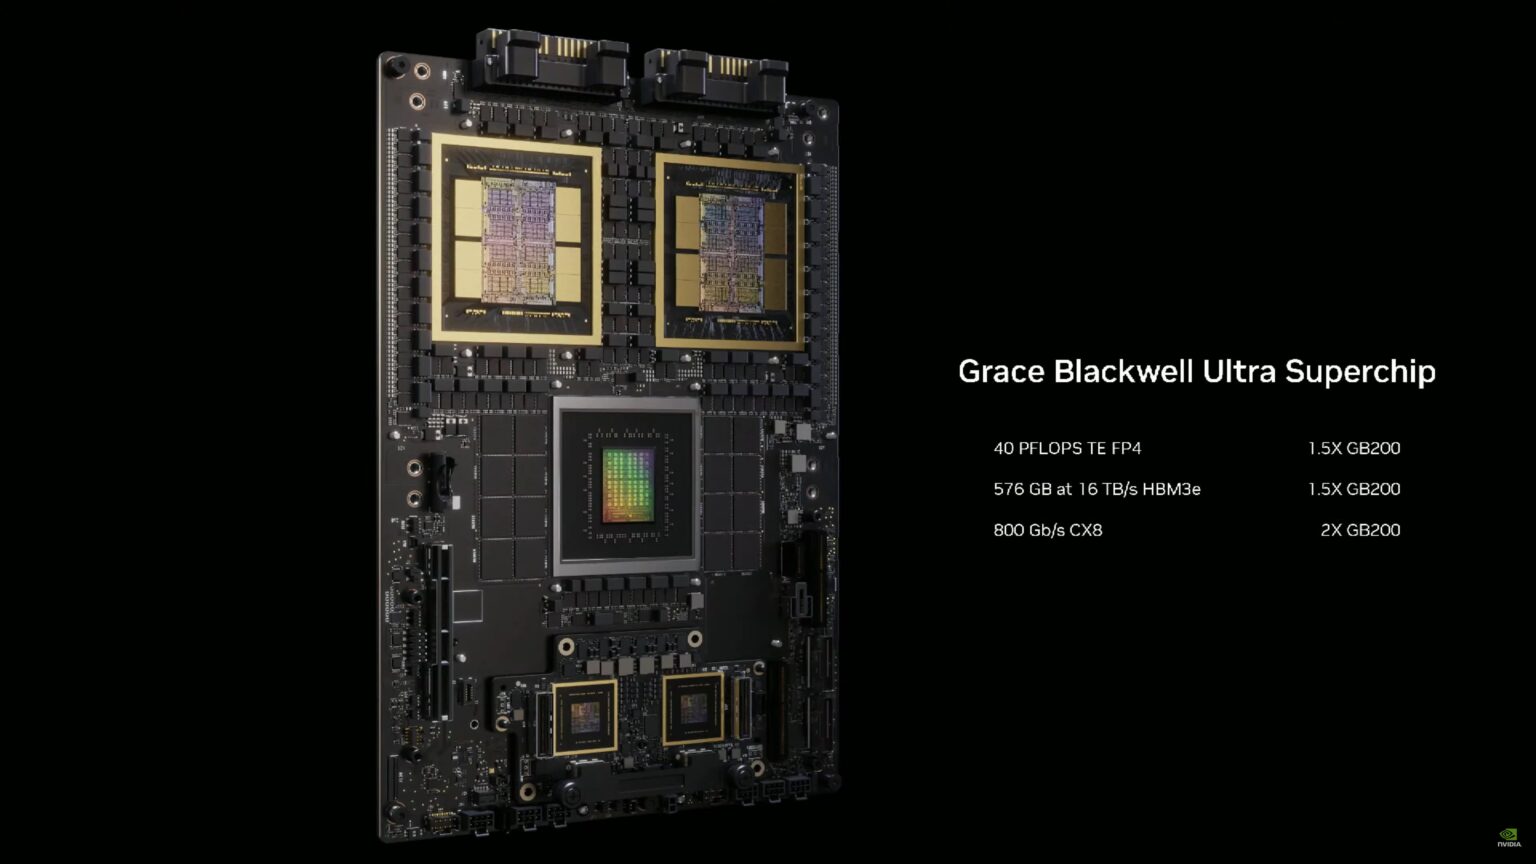
Nvidia’s Blackwell GPU rollout created an AI compute oversupply after customers preordered millions of chips amid expected shortages.
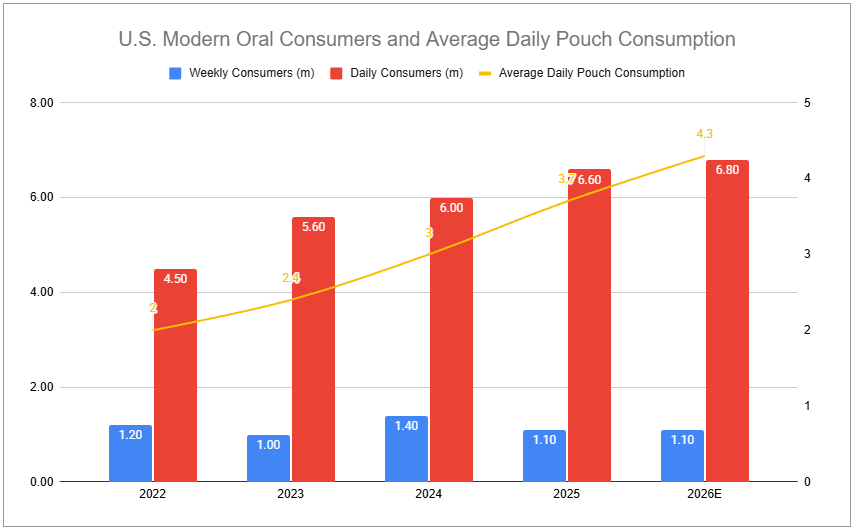
British American Tobacco’s U.S. reset revives combustibles and rebuilds its nicotine-pouch portfolio after legacy-brand writedowns and Velo…
Geely’s ZEEKR nearly doubled first-half 2026 deliveries to 178,000, while Geely bought 30% of NIO’s battery-swapping unit to reduce…
 The Asian Investor 5 clicks
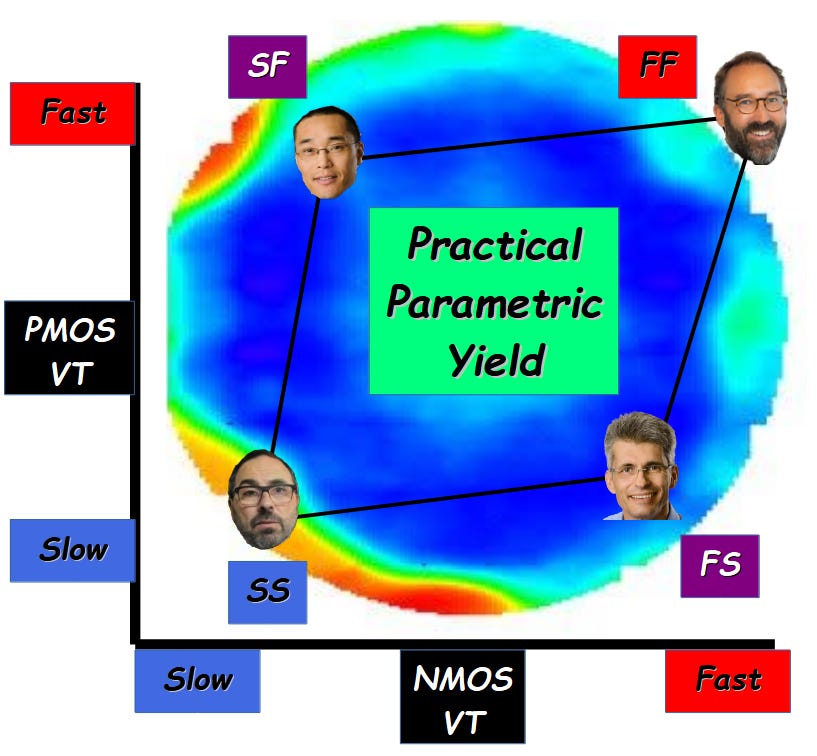
Cerebras’s WSE-3 faces parametric-yield constraints that could restrict supply, making power and clock-speed tradeoffs central to its next…
AI infrastructure’s $6.3 trillion financing gap is driving structured debt and asset-backed solutions, starting with Meta’s planned 5GW…
Walmart's FY28 consensus requires 15–18% operating-income growth above plan despite diesel costs, price investments and a non-recurring…
 Sameer Shahzad 2 clicks
Lennar is selling homes to former spinoff Millrose, whose revenue largely comes from Lennar and whose largest voting shareholder is…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst The Asian Investor
 The Bullionaire
 The Curious Analyst The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.