One of the Best Business Models in the World Just Went on Sale
AppLovin trades at 18 times EBITDA after a 57% drop, despite 84% EBITDA margins, rapid growth and a machine-learning advertising platform.
AppLovin trades at 18 times EBITDA after a 57% drop, despite 84% EBITDA margins, rapid growth and a machine-learning advertising platform.
@EricTheUmpire If you want exposure, buy $PSH.LN (or $PSHZF) which is trading at around 70% of NAV (implies $35/share for $PSUS). https://t.co/oSFLPLfnqr
I just published my Earnings Update about the Q1 2026 of Evolution $EVO $EVVTY. You can find it in the Portfolio section of the blog :) https://t.co/QXlBS93lji
@ramahluwalia how much are you investing in $acn as a % of your book?
Excelsior Cap $ECL is a good example of why I like small and micro-cap liquidations stocks. The good ones look like this. Big step-change moves and otherwise stable. https://t.co/CrSEoHnShP
how is this not the end for $wix and $gddy? https://t.co/nY1p4vAMfN
@MLedrappier @CalgaryLeveen No doubt a sale of Globalstar to Amazon or SpaceX would be great news for $NN. Especially at the valuations being cited. I am long a small position in $GSAT. This would be an incredible day for NN. Validates spectrum valuations
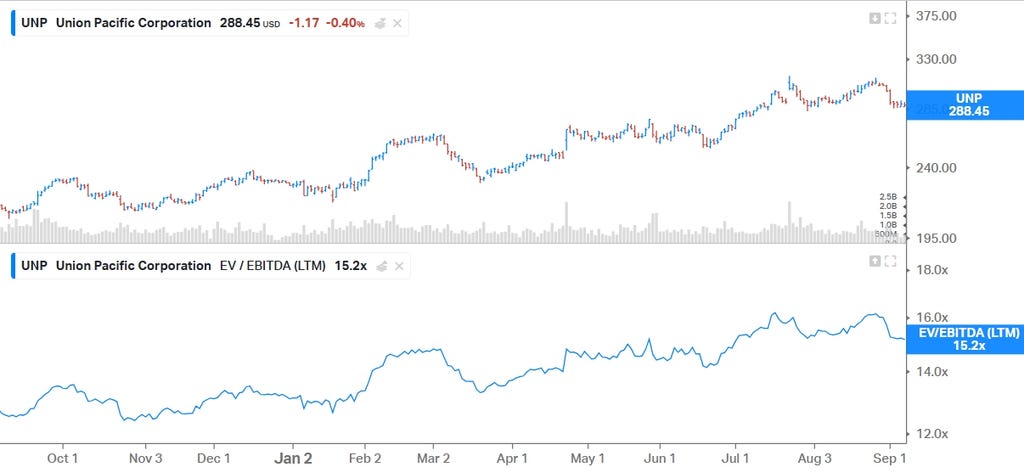
Union Pacific’s $85 billion Norfolk Southern merger pitch centers on a coast-to-coast rail network that cuts interchange delays and wins…

Dell’s Q2 revenue rose 57.7% to $47.0 billion and RPO tripled to $132 billion, but its stock trades at 32 times unlevered pretax free cash…
Lululemon’s Q2 revenue fell 4% and Americas comparable sales 12%, as markdowns, tariffs and activewear rivals pressure its premium apparel…
Ryan Tunis discusses P&C insurers, favoring Travelers over Chubb in a soft commercial market and calling AIG a near-book-value self-help…
Pinterest’s Q2 showed reaccelerating North American growth, while weaker international trends, AI-related engagement risks and elevated…
 Richard Durant 2 clicks
MBI Deep Dives will update prior company analyses through year-end, beginning with Uber, while deferring new work on Micron and S&P Global.
Lululemon’s Americas revenue fell 8% and comps dropped 12%, while a $134.5 million tariff refund masked weakening underlying margins after…
 On the Pulse 1 click
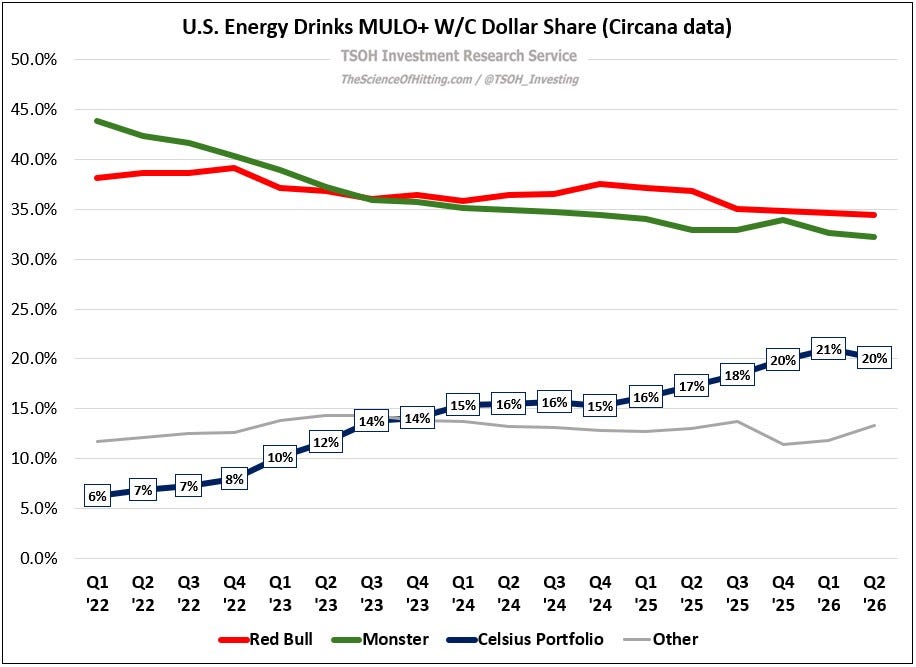
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
Check Point Software’s AI-centric cybersecurity platform could lift revenue growth to 10%, supporting a $166 intrinsic value estimate…
 Hong Chew Eu
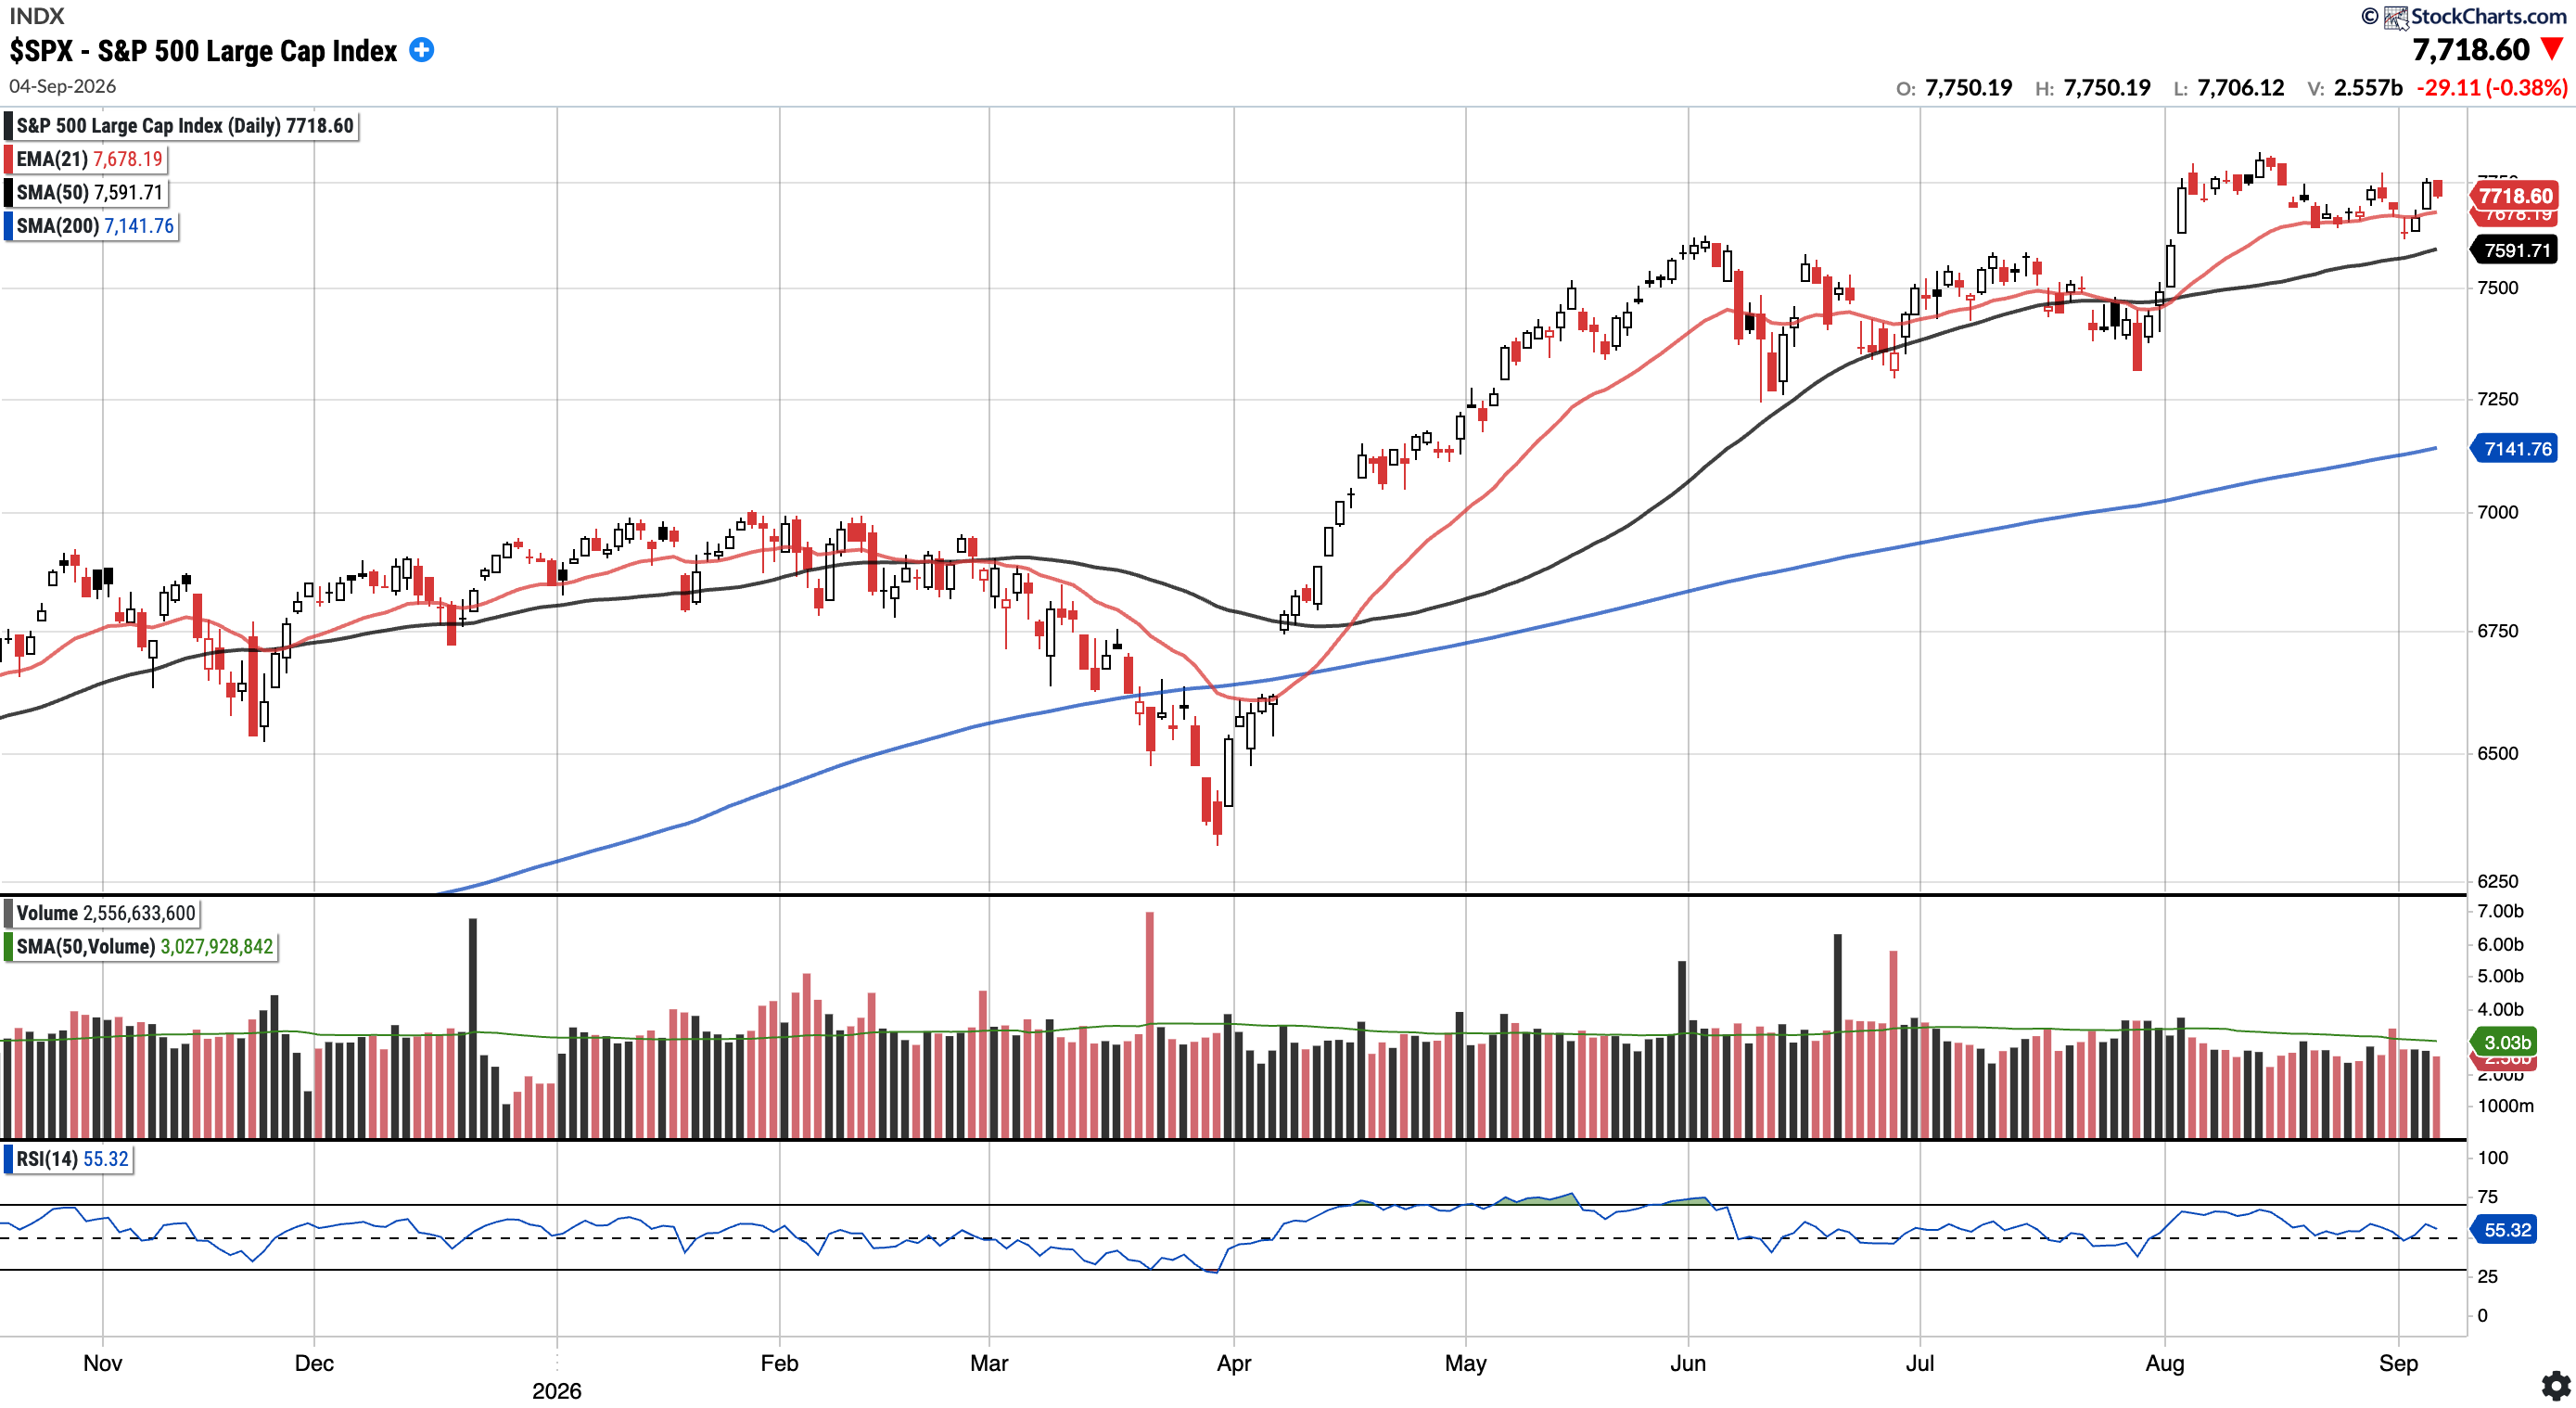
U.S. CPI and PPI headline the September 7 week as the S&P 500 holds key averages, Bitcoin faces $82,000 resistance and gold tests its…
 FTAI · long
FTAI Aviation, valued near $23 billion at roughly $226 per share, is presented as a long investment.
AppLovin is down 48% YTD after its first guidance miss, with revenue 1% below expectations and EPS 2.5% short, reviving fears of an adtech…
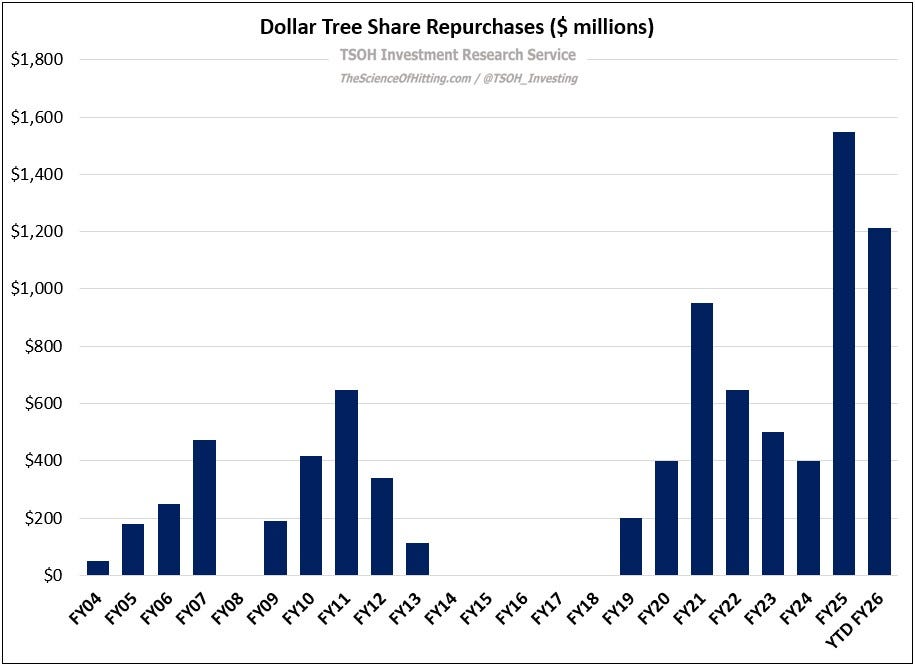
TSOH Weekly Roundup covers Costco’s $4.99 chicken supply chain, Celsius’s 20% energy-drink share, and California utilities’ wildfire…
Southwest Airlines is adding ancillary fees, assigned seating and premium products after a 6.7% Q2 adjusted operating margin, targeting up…
 Tim Dunn
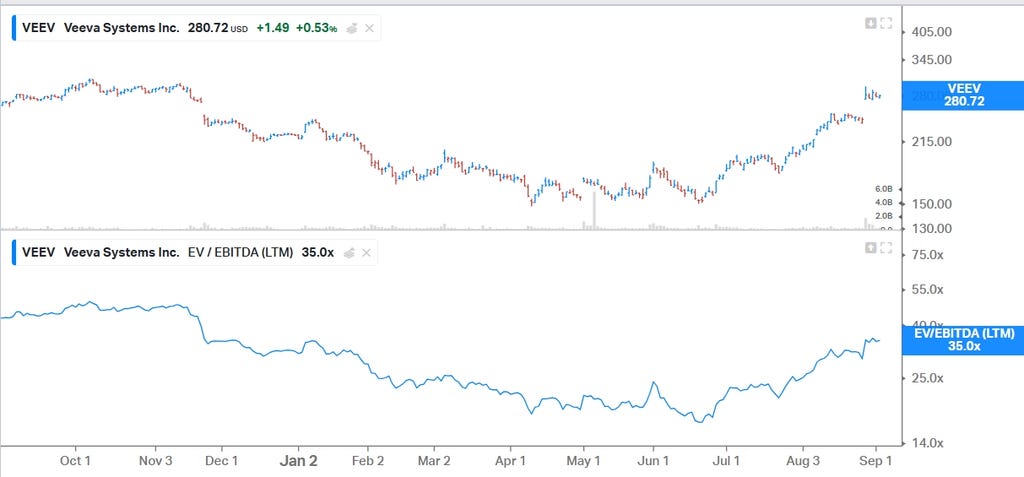
Veeva targets CRM share gains from Salesforce migration delays while Falcon agentic labor expands its reach into life-sciences safety,…
Intuit targets 9.1% FY2027 revenue growth and 23% EPS growth after Q4 revenue rose 13.7%, supported by Global Business Solutions, Credit…
 Treading Softly 5 clicks
CME perpetual-futures activity is tested against more than 240,000 CFTC data points on open interest and dealer positioning.
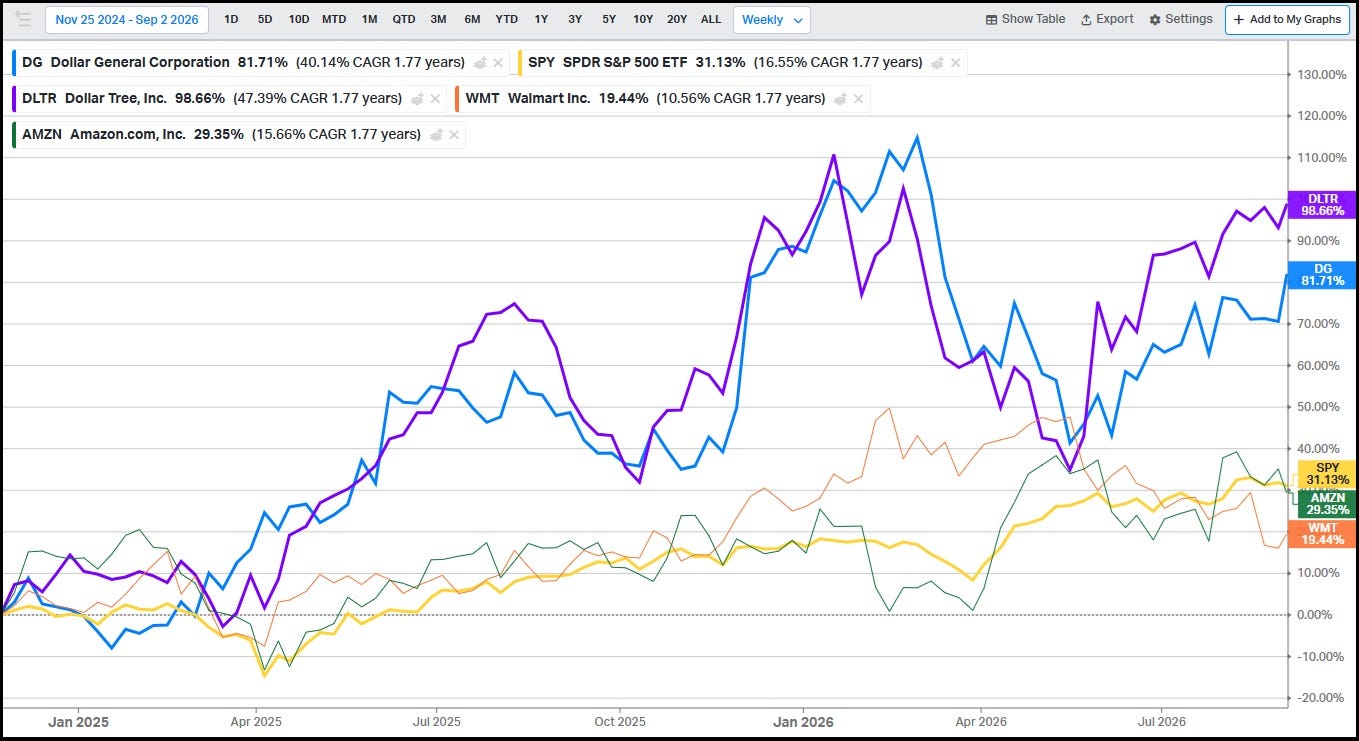
Dollar General’s Q2 FY26 comparable sales rose 3.5%, beating Walmart U.S.
Chevron committed $7 billion to expand Venezuelan output as record U.S. production and elevated oil prices lifted Q2 earnings.
 Bay Area Ideas 3 clicks
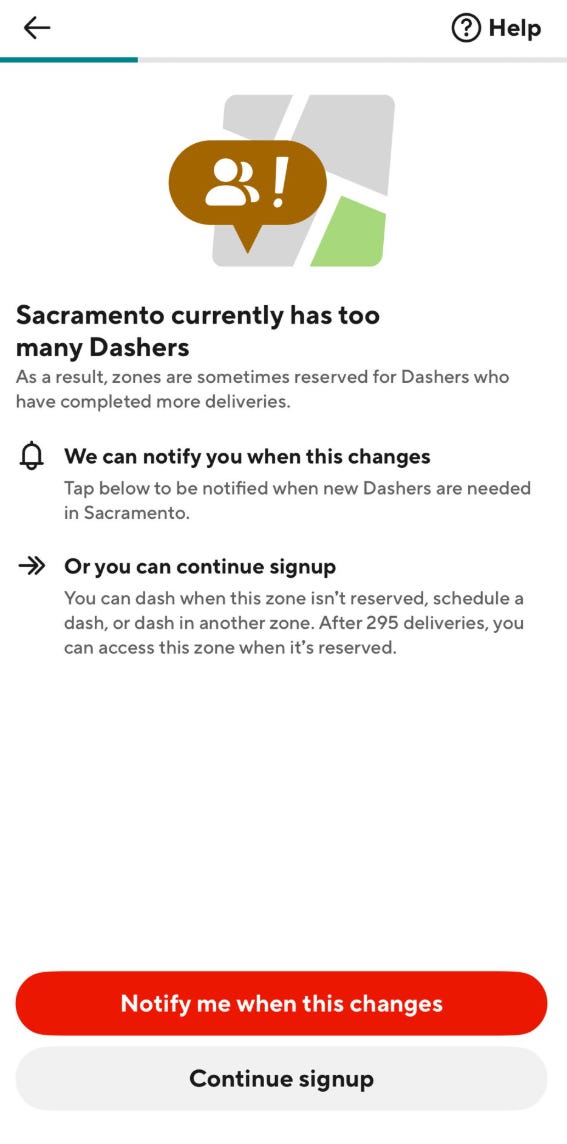
DoorDash’s delivery economics rely on customer tips and flexible labor, while rising courier costs make autonomous delivery central to…
Every publication on this site, hand-picked.
 Andres Veurink Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.