Meta’s GEM, Part 2: Finding the Scaling Law
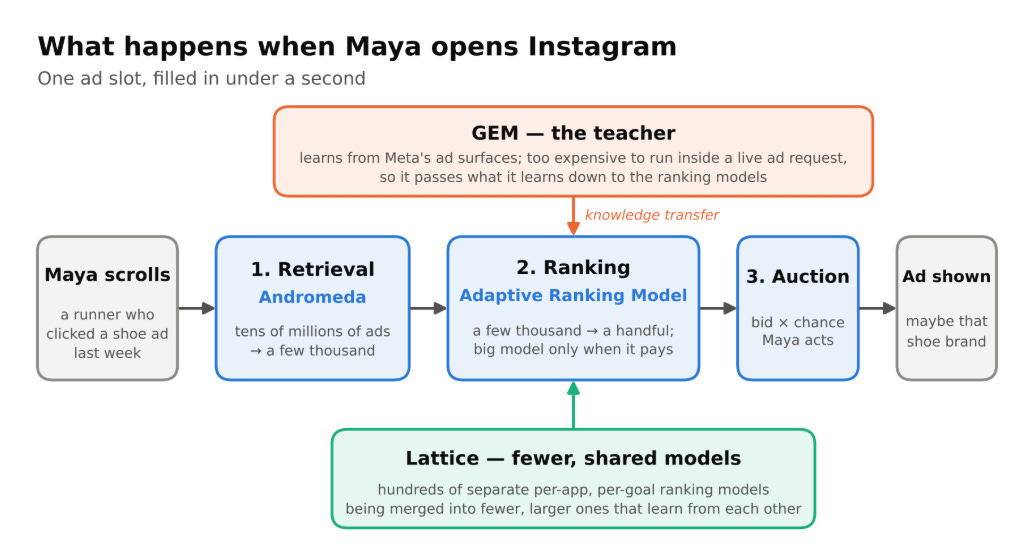
Meta’s GEM trains smaller ad-ranking models across its platforms, with Kunlun showing performance scaling predictably as compute rises.
Meta’s GEM trains smaller ad-ranking models across its platforms, with Kunlun showing performance scaling predictably as compute rises.
Remember when Avis went from $100 to $714 in just a few weeks this spring? Today it’s back at $100. What goes up, must come down. $CAR https://t.co/HsCdjshnuX
Geo Group $GEO sold its 3 Adelanto ICE facilities (2,644 beds) to DHS for $950M, about $359K per bed. The market currently values GEO at about $92K of EV per remaining owned bed, and that EV also includes the electronic monitoring and services businesses.
If you're naturally bearish like me I think it pays to push long when positioning gets washed out like it is now even if fundamentals are bad. Retail has been selling, hedge fund net leverage is low, $RSP and $QQQ have been smashed. You are going to be right 60-80% of the time,
I think we can assume that $PESI lost money in Q3, but the most important indicator for me is the backlogs. If they can show a huge increase in backlogs that should indicate that they can be cash flow positive in Q4 and beyond. Stock will go $20+ if market takes the "equity raise" risk premium out - which it should - if management can give certainty on the cash flow front. Again, I think a focus on the backlogs would be the main indicator of this.
Free Recaps of the best new stock ideas, delivered every morning.
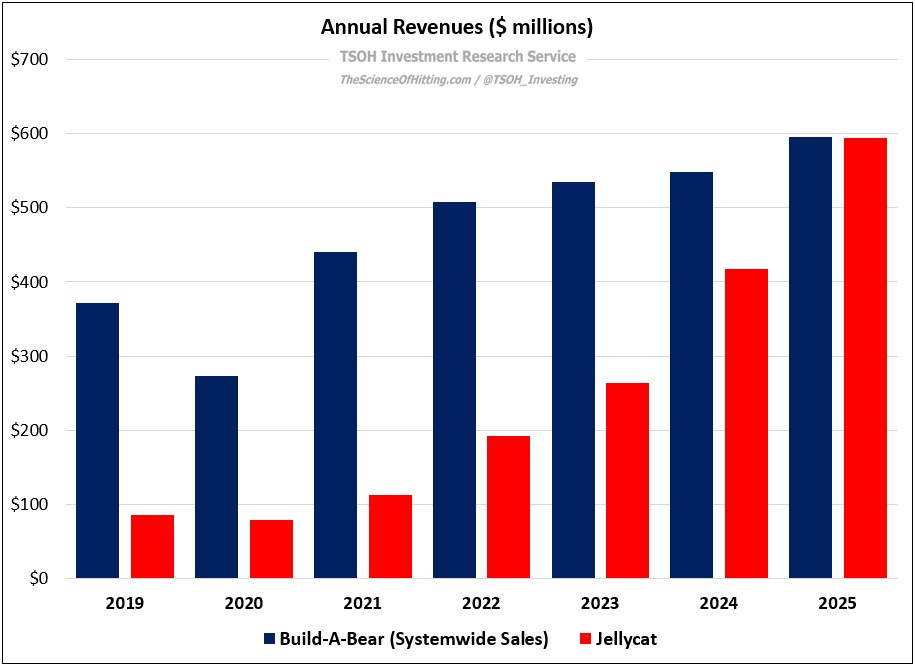
Build-A-Bear's push into prestuffed toys and broader retail distribution tests brand stretchability, but recent results warrant caution.
Lennar’s land-bank costs pressure homebuilding margins, while Flowers Foods weighs a Tastykake sale after falling branded-bread share,…
LendingTree derives roughly two-thirds of revenue from insurance and trades near 4 times expected adjusted earnings despite record revenue,…
 Michael Fitzsimmons 2 clicks
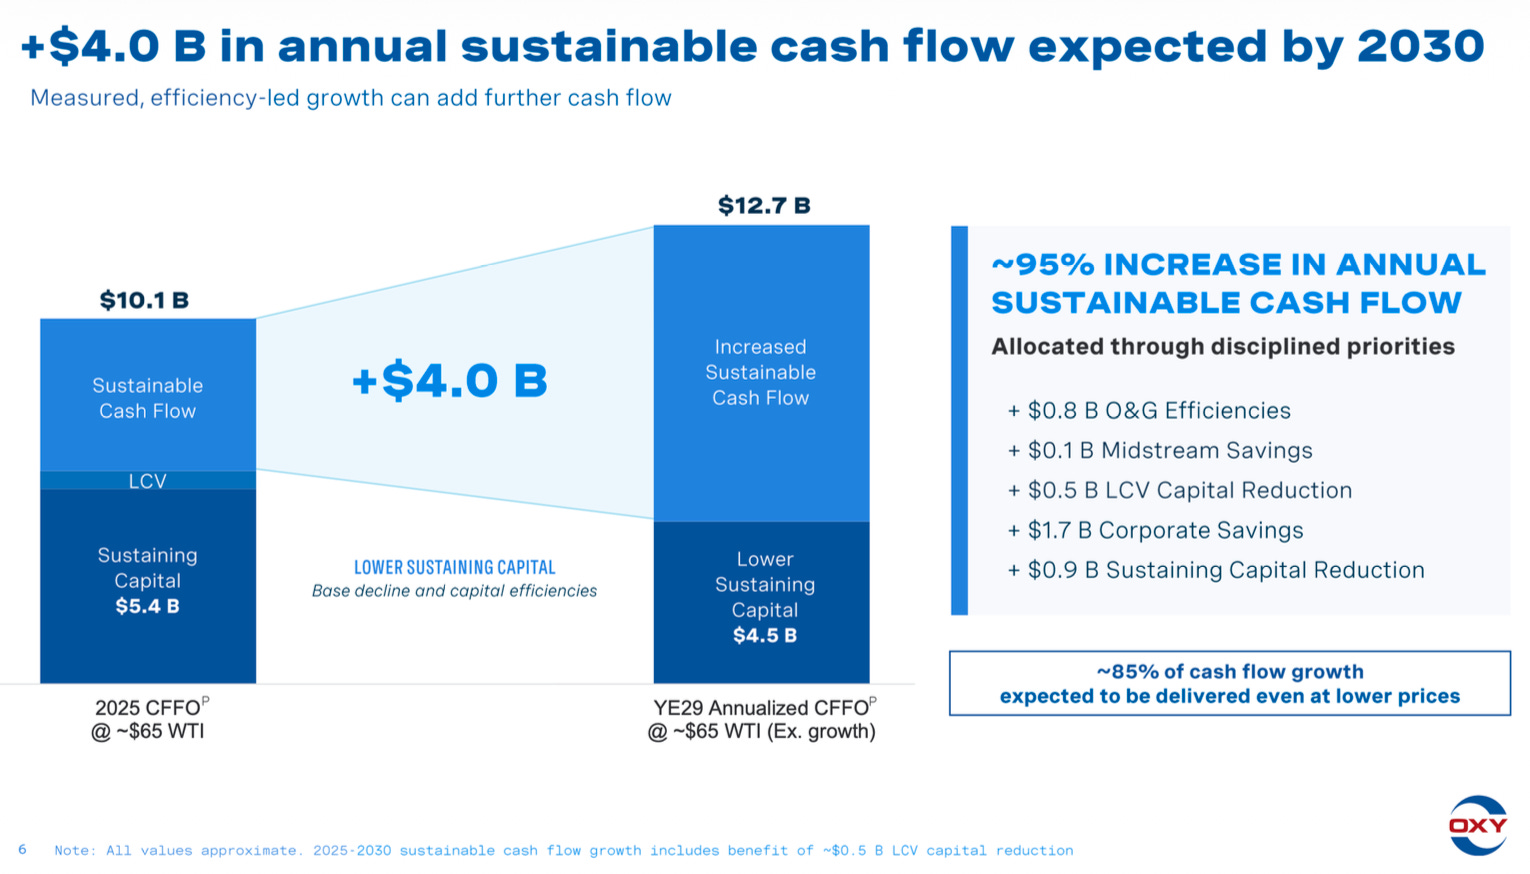
Occidental Petroleum’s debt should fall further after Q3 oil prices averaged $85 per barrel WTI and $91 Brent.
Hess Midstream, Iovance Biotherapeutics, Netlist and nine other lesser-covered stocks make this week’s Undercovered Dozen.
 The Undercovered Dozen 9 clicks
Apple’s HomeView strategy ties Siri, privacy and smart-home control to consumer trust in its vision for the home.
Digital Realty paid $120 million for Atlanta-area parcels including a former Army dump with buried carcinogens and military ordnance.
Wells Fargo’s Q3 EPS beat and $12.5 billion net interest income failed to move shares, while WFC.PZ preferreds yield 7.10%.
 Jeremy LaKosh 5 clicks
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper…
 USO · short
United States Oil Fund faces a short case tied to a long-Brent, short-WTI trade as Strait of Hormuz closure risk disrupts oil markets.
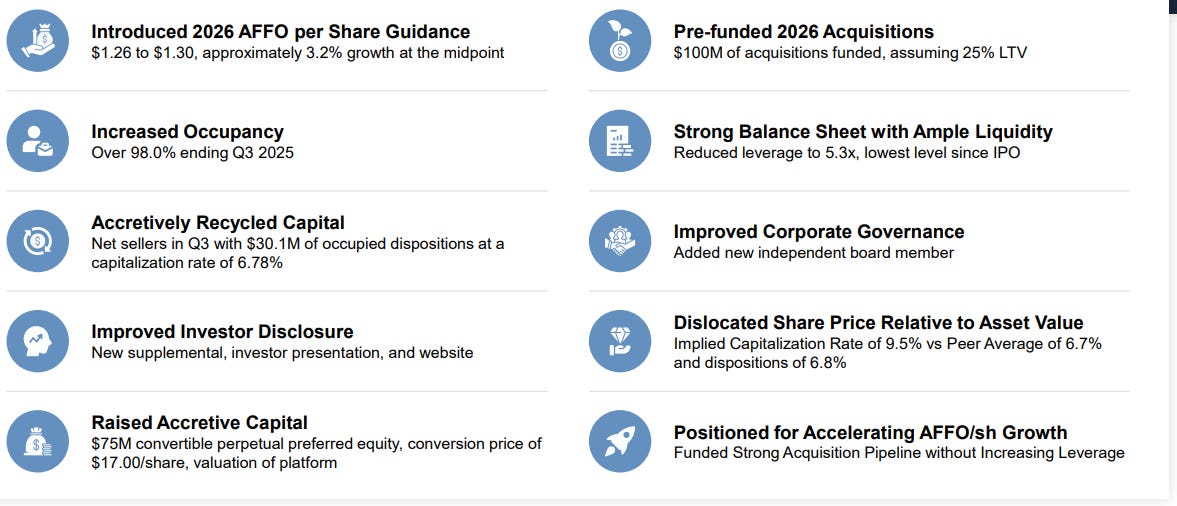
FrontView REIT remains discounted to estimated NAV after a 25% gain, while 19 asset sales at 6.8% cap rates and 98% occupancy support…
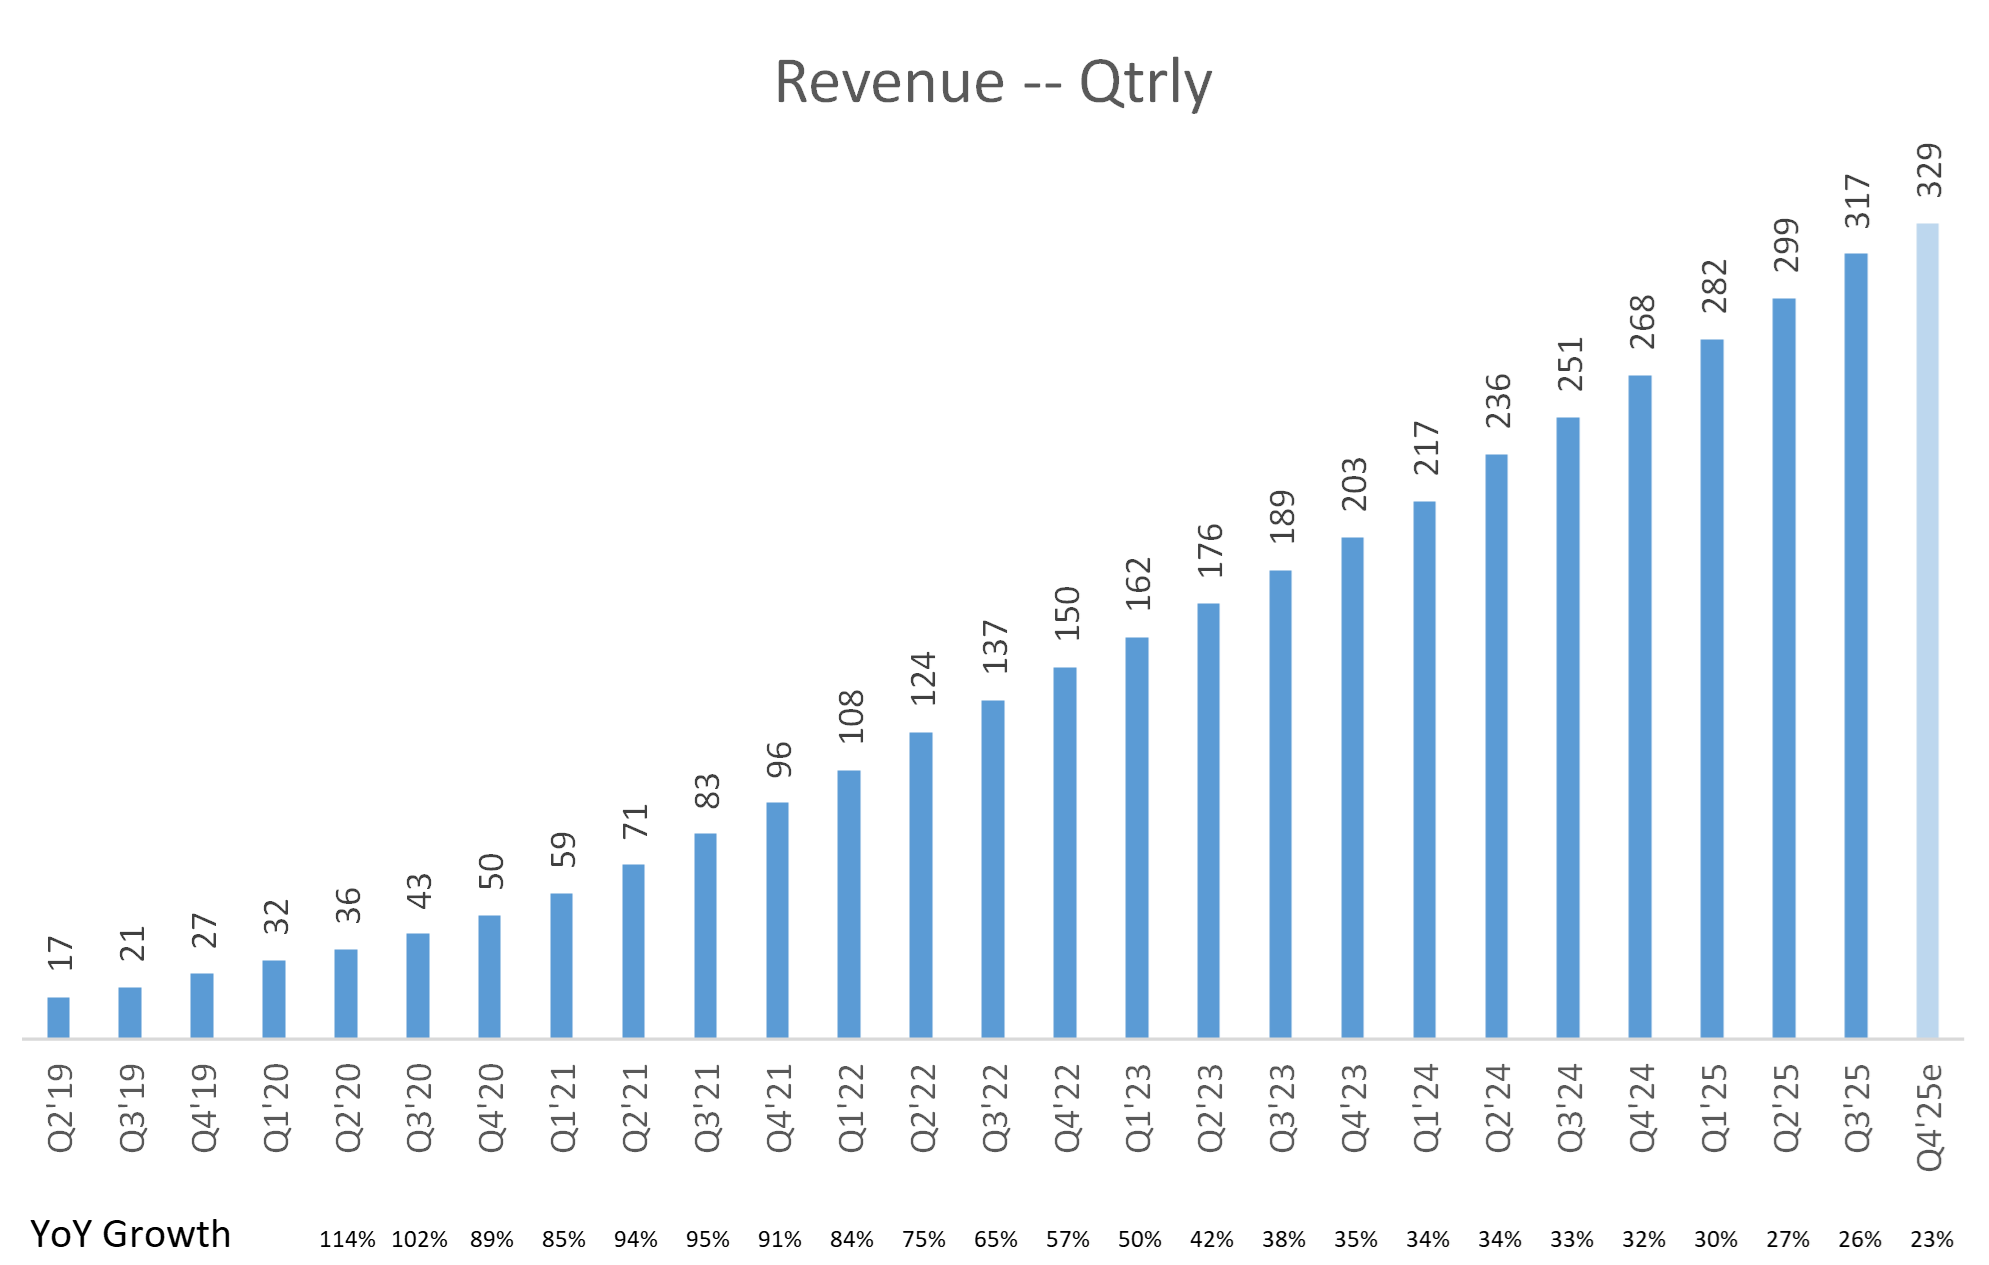
Monday.com combines work management, CRM, Dev and Service on a flexible core platform, with 90% gross margins and AI disruption risk…
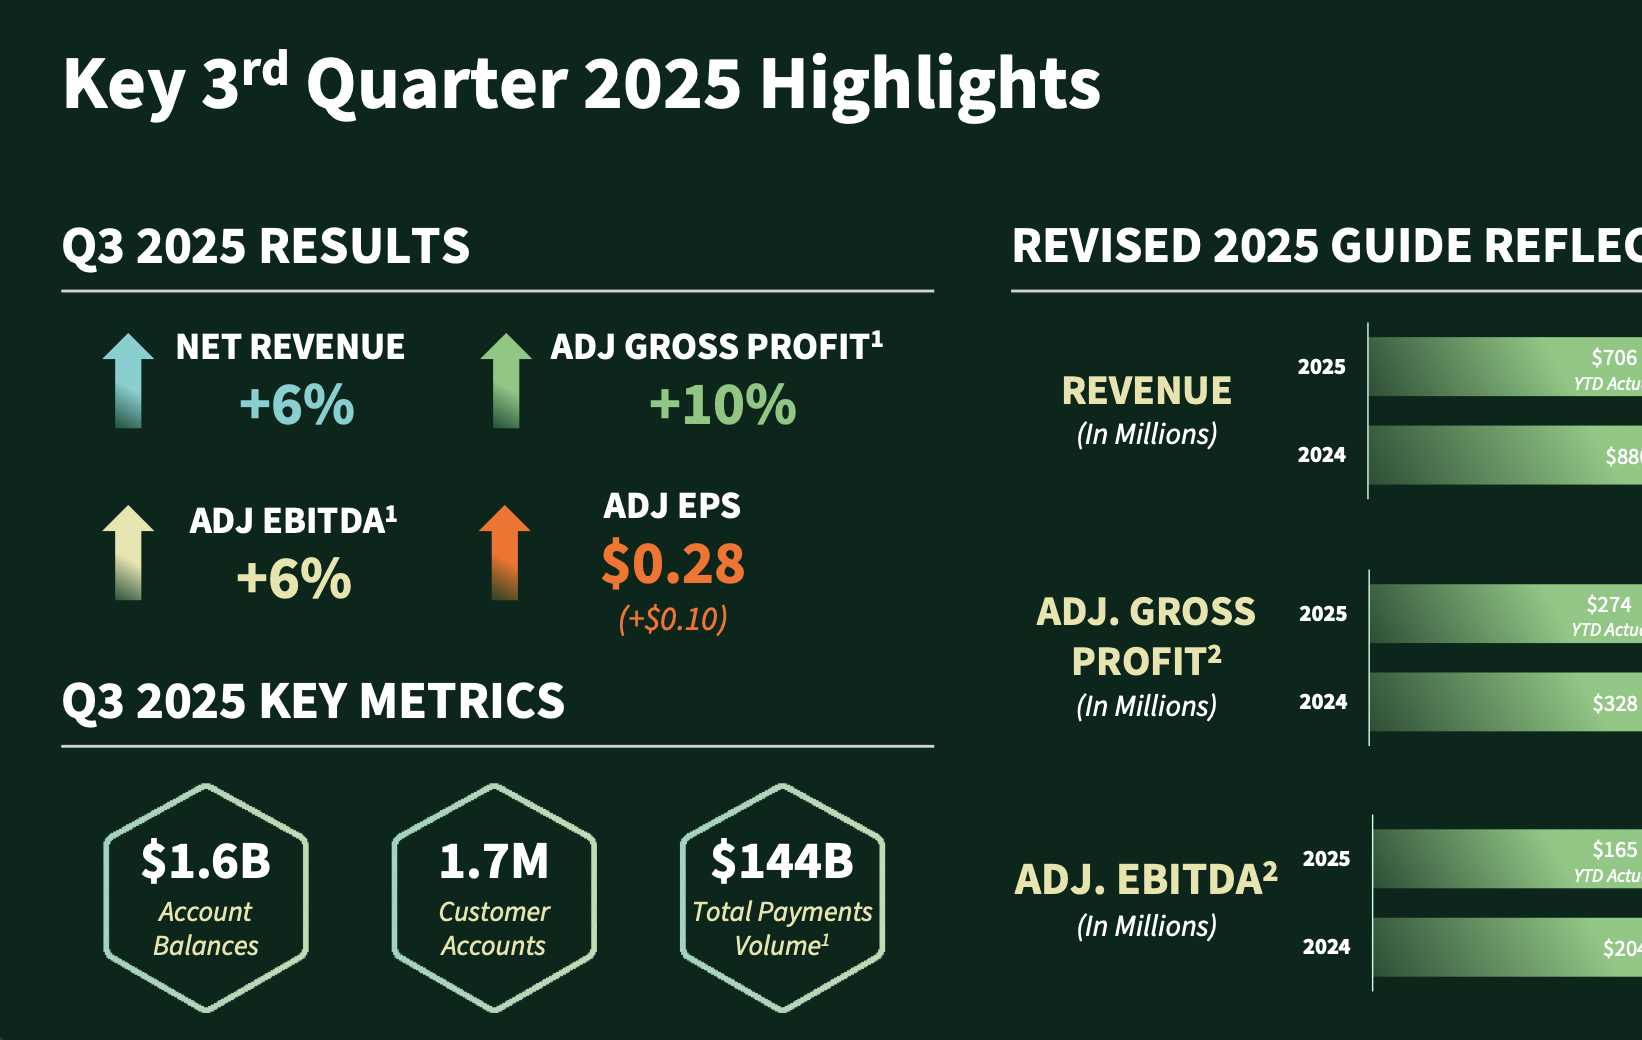
Priority Technology received an opportunistic buyout proposal, with its business better suited to remaining public absent a much higher…
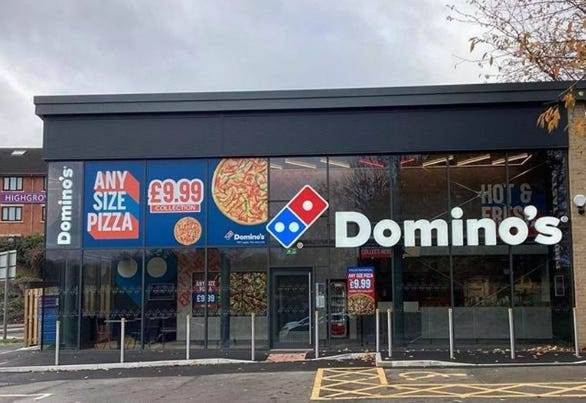
Domino’s and Greggs carry 7% and 6.7% declared UK short interest as weak consumer spending pressures volumes, with Greggs’ valuation…
Warren Buffett will stop Berkshire’s annual-report letters and retire as CEO, leaving Greg Abel to lead while continuing annual…
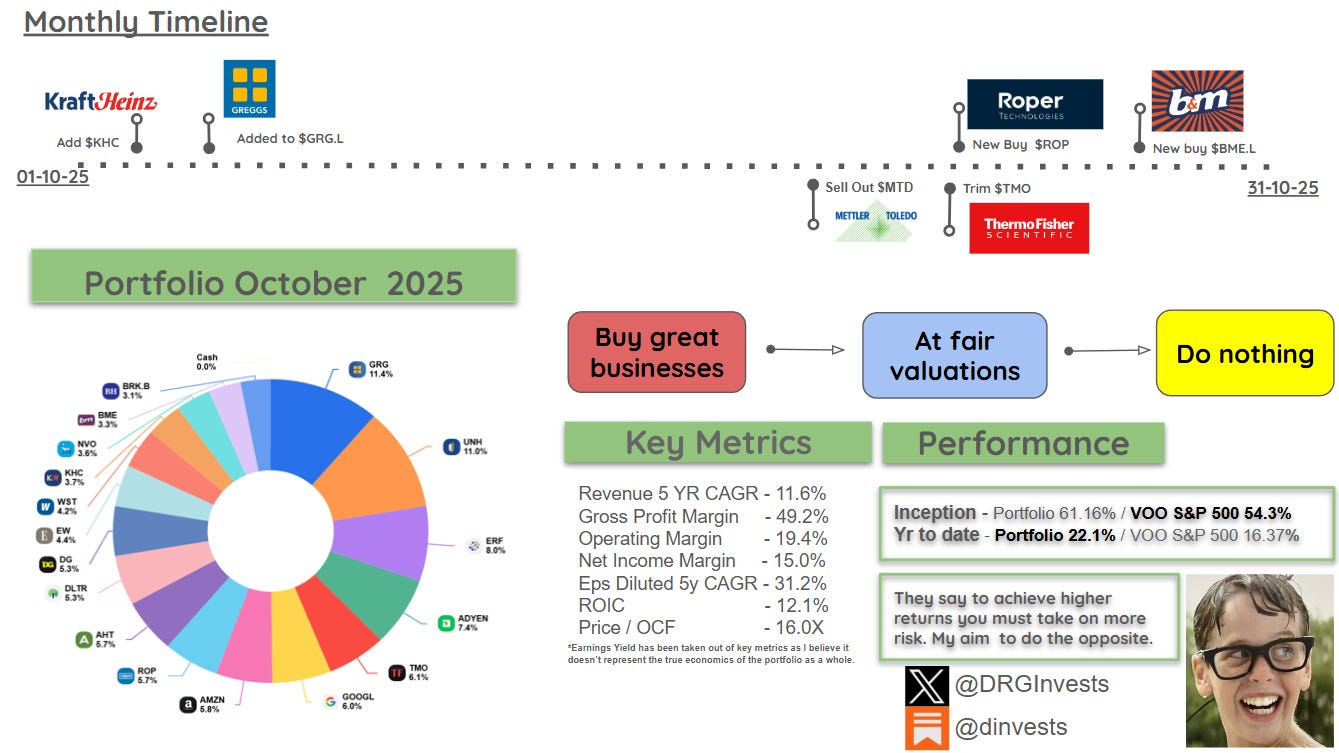
DInvests portfolio gained 6.8% in October, buying Roper Technologies and B&M while adding to Kraft Heinz and Greggs and exiting…
Data Modul AG's strategic review could lead Arrow Electronics to sell its 69% stake in the German industrial-display maker after a cyclical…
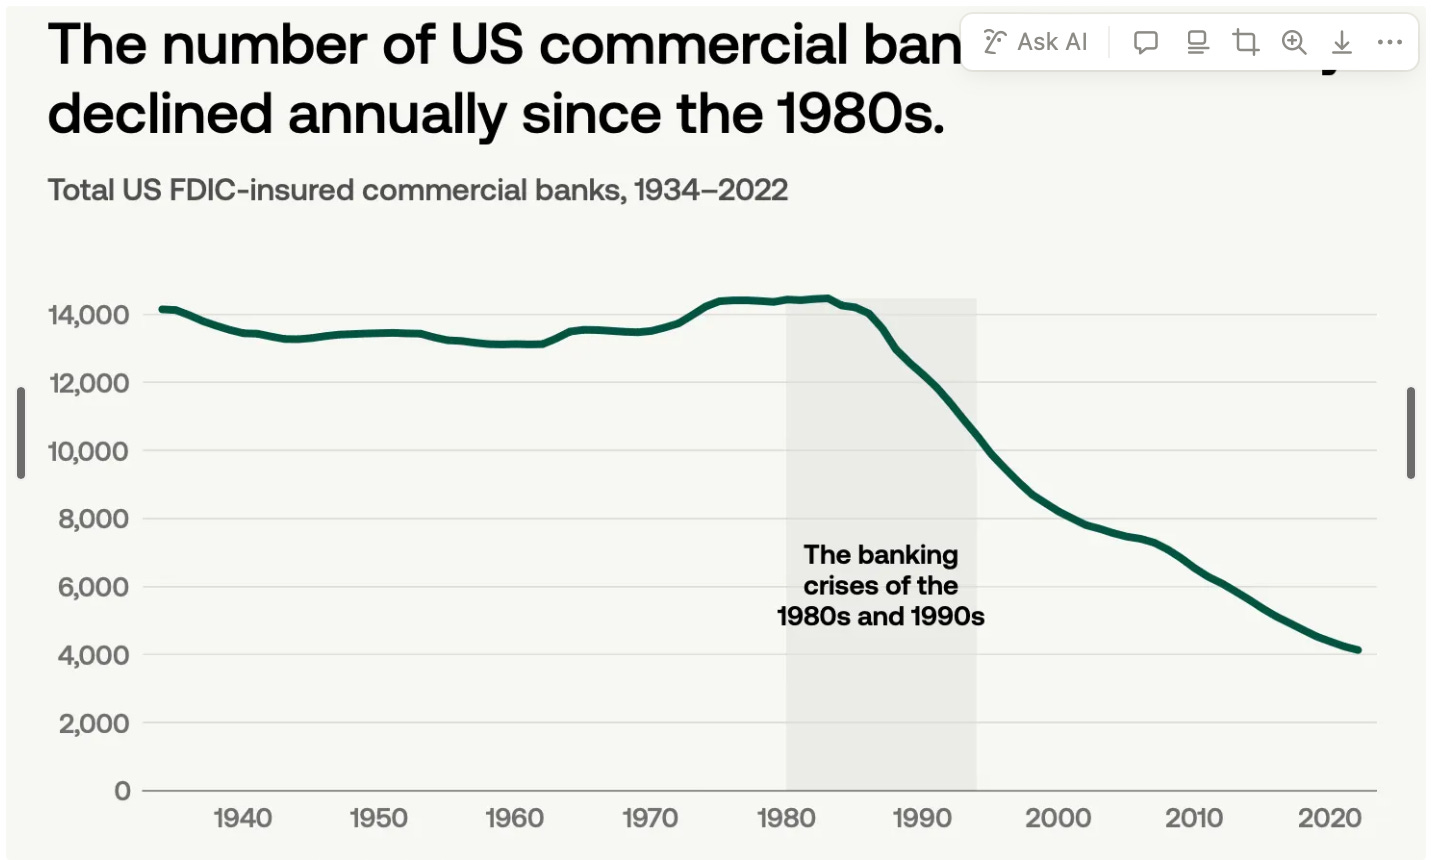
Community banks trading at 50-70% of book value can benefit from buybacks and consolidation, with recent targets MSVB and PMHG receiving…

Memory stocks are ripping while Intel lacks a near-term catalyst in an earnings-season idea roundup.
Have a source we’re missing? Send your pick
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.
Anything we’re missing?
Send us a pick