Is The Market Turning The Page?
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
You do not need to be the fastest animal on the Savanna to survive, but it helps not being the slowest: https://t.co/hVEbs3fqCa $FISV $FIS $JKHY
@finphysnerd I don't think that's short breadth unless your longs are mega caps. Short breadth would be like long $SPY short $RSP.
Free Recaps of the best new stock ideas, delivered every morning.
ASML’s patent filings point to a track-based die-to-wafer hybrid bonding tool that could challenge Besi in advanced logic packaging.
CoreWeave’s 2032 notes yield over 15%, signaling a 54% default probability as borrowing costs exceed rental yields on AI infrastructure…
 Dustin Quasney 15 clicks

AppLovin rebuilt its ad model with AXON 2.0, lifting LTM revenue to about $7 billion and margins to 77% as Unity competition threatens…
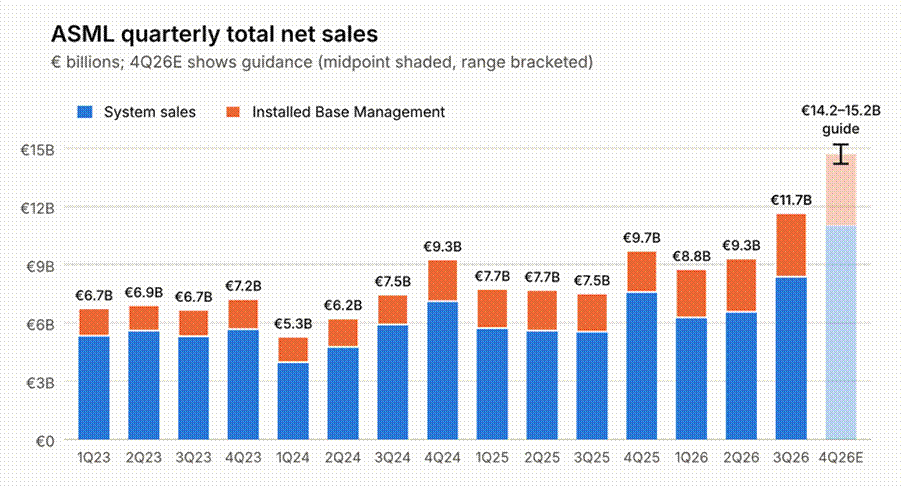
ASML reported €11.7 billion in 3Q 2026 sales, up 55%, and raised full-year guidance to €44–45 billion as AI-driven semiconductor demand…
Marvell is positioning networking, optical connectivity and server-management chips as AI data centers link GPUs, custom accelerators and…
AeroVironment's $465M LOCUST laser award and earnings beat support its 2027 growth outlook despite government budget uncertainty.
 Melissa Tucker 4 clicks
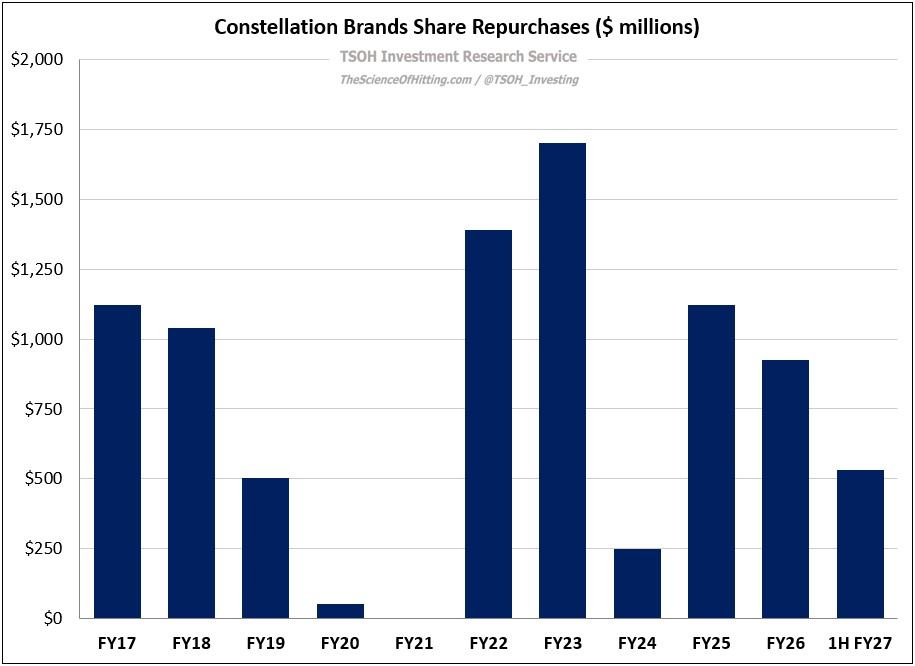
Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
Transocean’s Valaris merger clears regulators, creating a 68-rig offshore driller controlling four in 10 global drillships.
TSMC reported excellent Q3 results, guided Q4 revenue growth higher and saw its shares slip despite strong AI-driven earnings momentum.
 Fundamental Options 1 click
 MGRC · long
McGrath RentCorp's conservatively financed hard assets, pricing growth and a struggling competitor, WSC, underpin the long thesis.
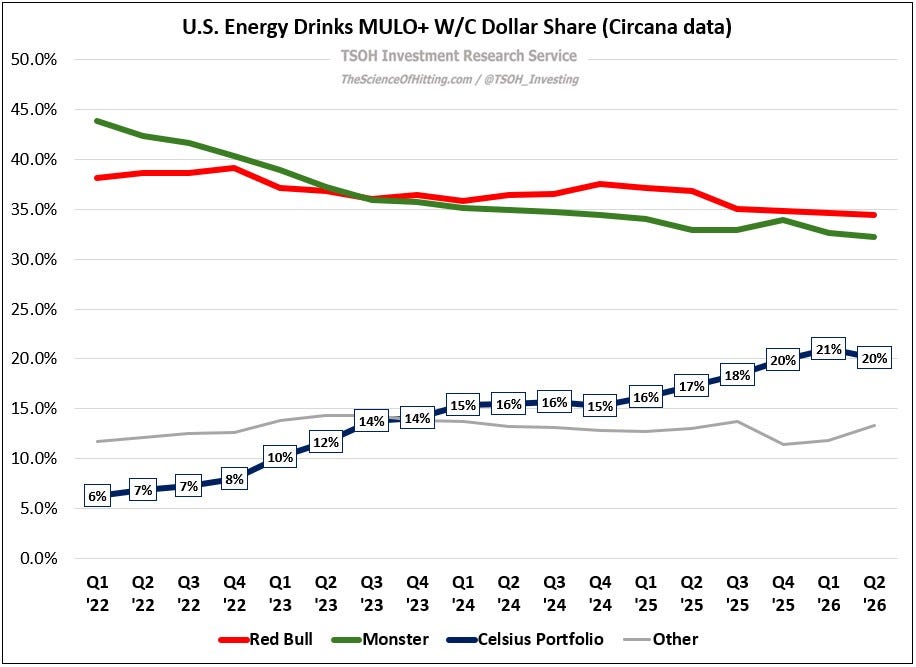
Celsius holds 20% of the U.S. energy-drink market and 40% of sugar-free sales, but its $1.65 billion Alani acquisition complicates…
On Holding $ONON combines a high-margin direct-to-consumer footwear model with replacement-driven demand, after Q2 2026 sales rose 21.6%…
Latticework’s Labor Day briefing covers Alphabet’s TPU roadmap, HAL Trust’s asset-value discount, UMG’s buybacks, and AI data-center…
Check Point Software’s AI-centric cybersecurity platform could lift revenue growth to 10%, supporting a $166 intrinsic value estimate…
 Hong Chew Eu
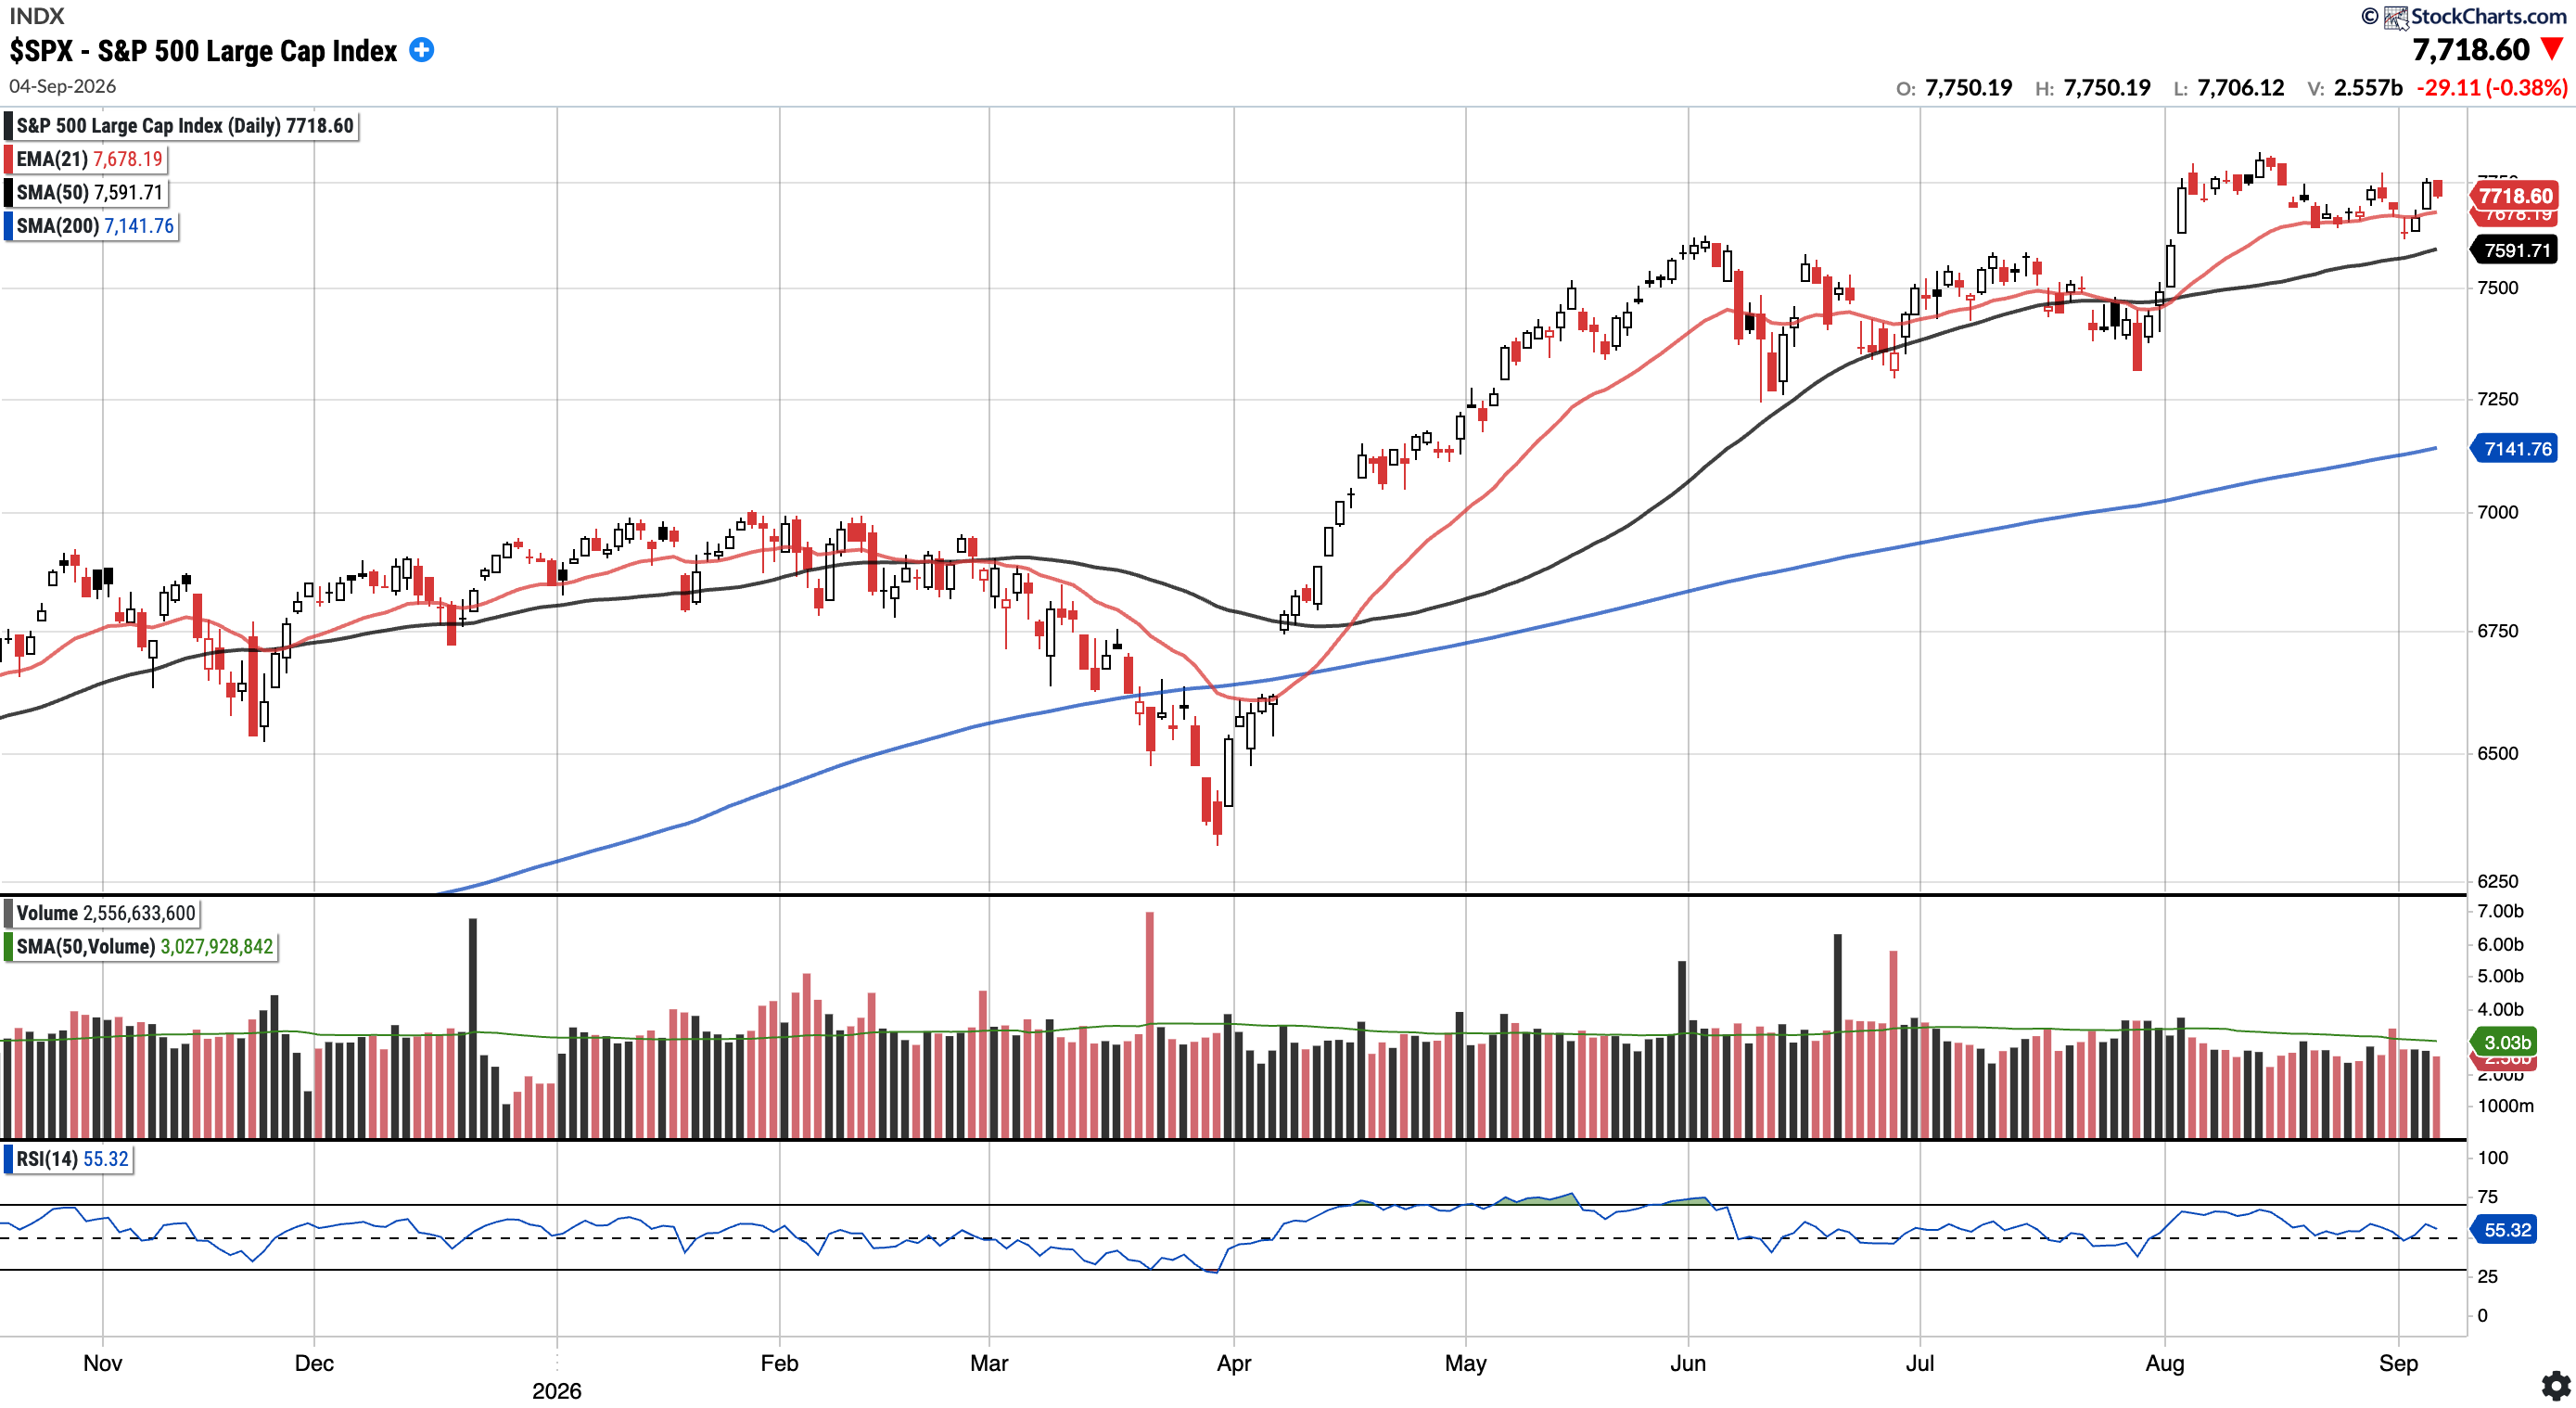
U.S. CPI and PPI headline the September 7 week as the S&P 500 holds key averages, Bitcoin faces $82,000 resistance and gold tests its…
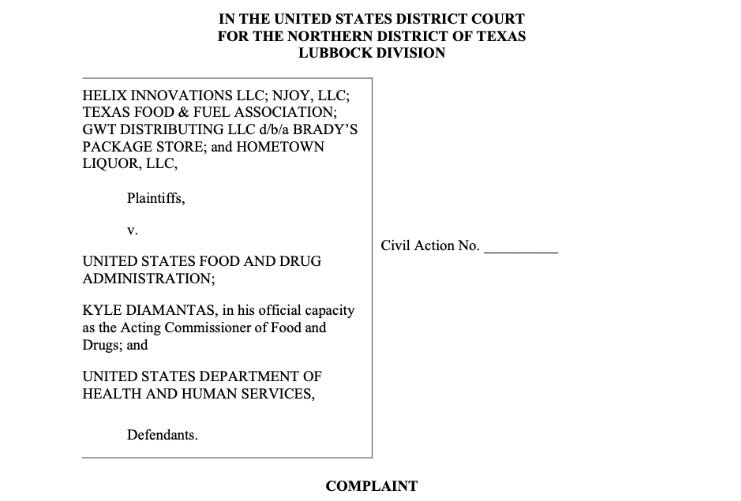
Altria's NJOY sued the FDA after launching unauthorized nicotine products, challenging e-cigarette regulation and pressing the agency to…
X-energy targets $1.8 billion in annual revenue and more than 42% gross margins by 2032 through reactor IP, project services and…
 Simple Investment Ideas 2 clicks
AppLovin is down 48% YTD after its first guidance miss, with revenue 1% below expectations and EPS 2.5% short, reviving fears of an adtech…
RBC Bearings' Q1 2027 revenue rose 19.2% and net income 48.2%, while a $2.3 billion backlog driven by aerospace and defense supports growth…
 Daniel Jones 1 click
Have a source we’re missing? Send your pick
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.
Anything we’re missing?
Send us a pick