Sonida Senior Living owns 153 senior housing properties after a March 2026 merger doubled its scale, with aging-driven demand and tight…
S Value Don't Lie 5h ago 3 clicks
Ondas reported $167.5 million in Q3 revenue but spent $562 million of cash, halved gross margin and fell below its $6 stop level.
BL Cestrian Capital Research 6h ago 3 clicks
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.
S Cannibal Stocks 7h ago 5 clicks
Sun Kwang (003100.KQ) raised grain market share from 25% to 38% as its founding family transferred 24% of the company to holding companies…
S Trade Ideas Flow 9h ago 3 clicks
Travere Therapeutics' FILSPARI has two FDA approvals and is driving revenue growth, while TVTX shares have nearly tripled since August 2025.
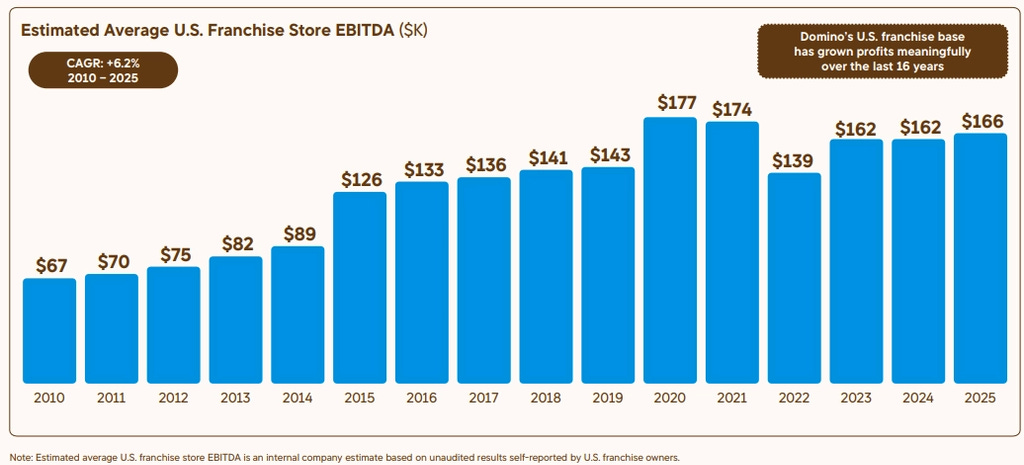
SA Out of Ignorance 9h ago 1 click Domino’s built PULSE, online ordering and Pizza Tracker into a delivery machine, driving 10% annual global retail sales growth after its…
S scuttleblurb 9h ago 3 clicks
Nubank and MercadoLibre update target prices as Brazil’s 9% real rates, weaker currency and tighter credit favor their cost advantages and…
S Jimmy's Journal 10h ago 3 clicks
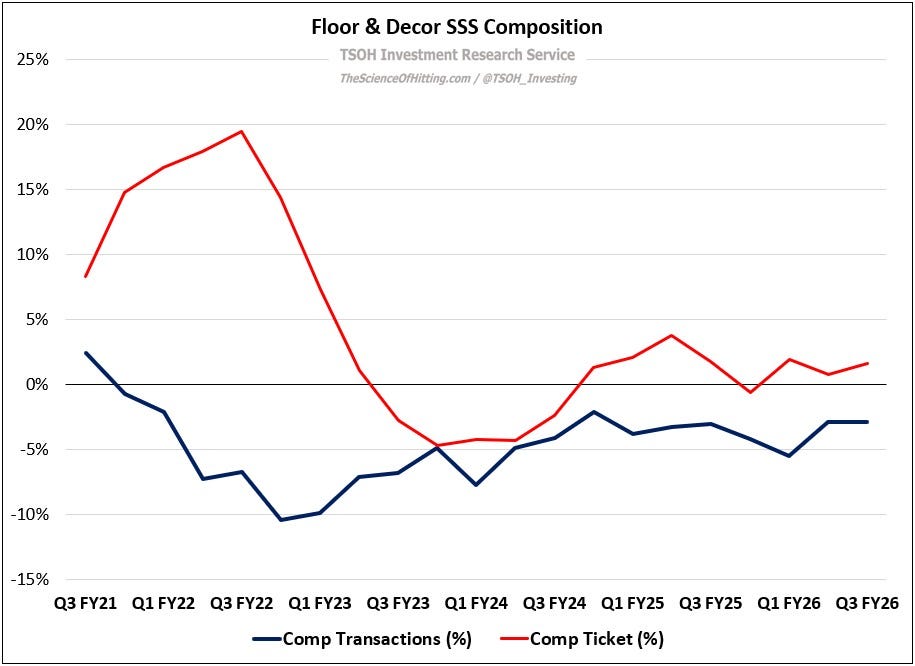
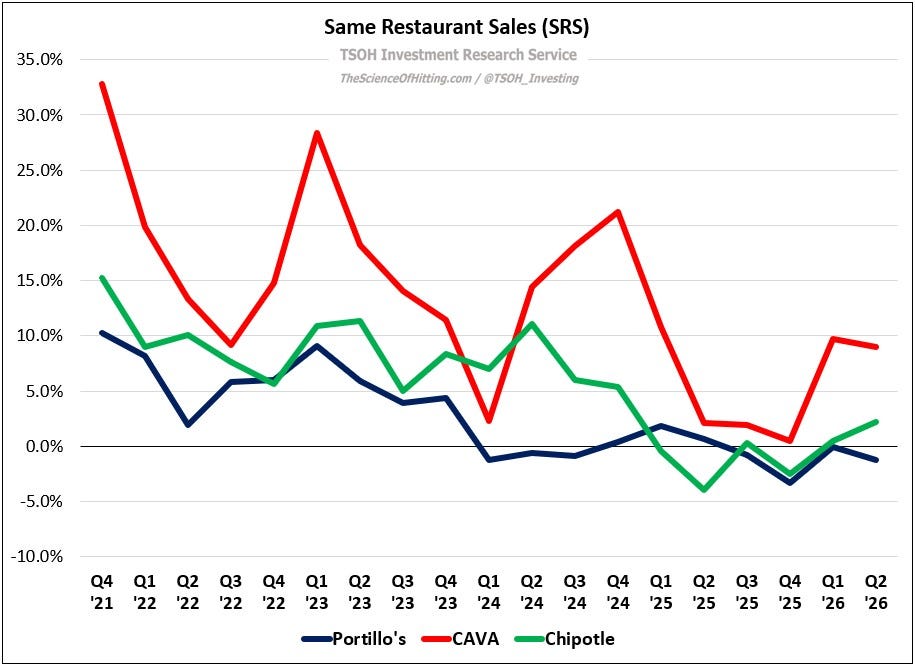
Floor & Decor has logged 20 straight quarters of comp transaction declines, with Q3 quarter-to-date same-store sales down about 3.8% as…
S TSOH Investment Research 11h ago 4 clicks
HCI Group grew Q3 revenue 13% and net income 27%, with $2 billion of invested assets driving investment income.
SA Given Mahlangu 12h ago 3 clicks TPG trades 20% below its average distributable-earnings multiple despite the fastest fee-related earnings growth among alternative…
S Capital Employed 21h ago 8 clicks
INTU · long Intuit, down 60% year to date, is the Nasdaq 100’s worst performer, ahead of declines at Workday and Adobe.
BL Value Investors Club Jun 30 2 clicks
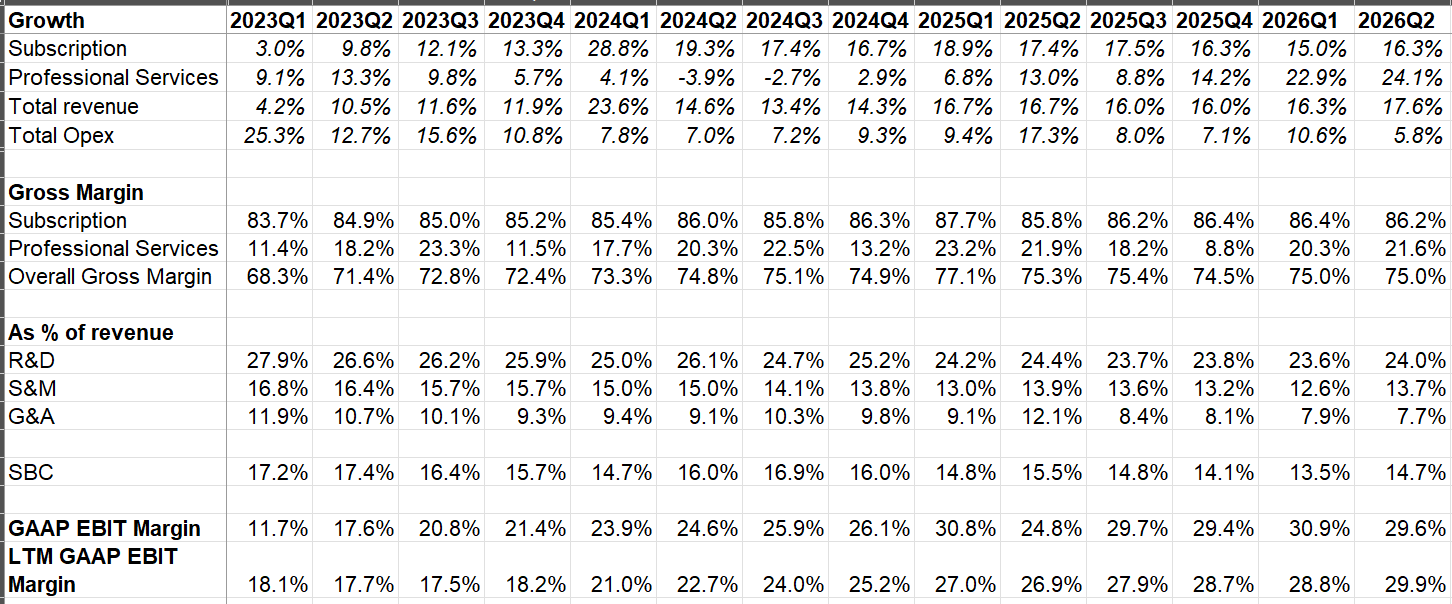
Veeva beat its $905 million revenue guide with $928 million, up 17.6%, while subscription growth accelerated and GAAP EBIT margin reached…
S MBI Deep Dives Aug 29 11 clicks
Bloom Energy’s 80x forward earnings valuation relies on concentrated megaprojects, sustained AI data-center power demand and continued…
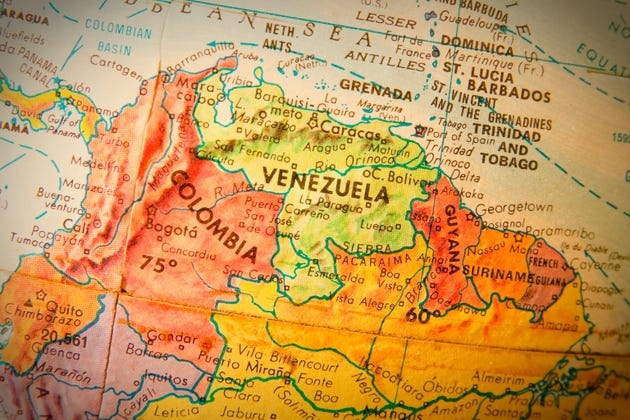
SA Valuation Rewind Aug 29 3 clicks Colombia and Venezuela are opening oil sectors to outside producers, as Venezuela offers producing blocks and Ecopetrol seeks capital for…
Salesforce's Anthropic alliance and Claudeforce launch drove a 22% post-Q2 2027 rally, while nonexclusive access and AI infrastructure…
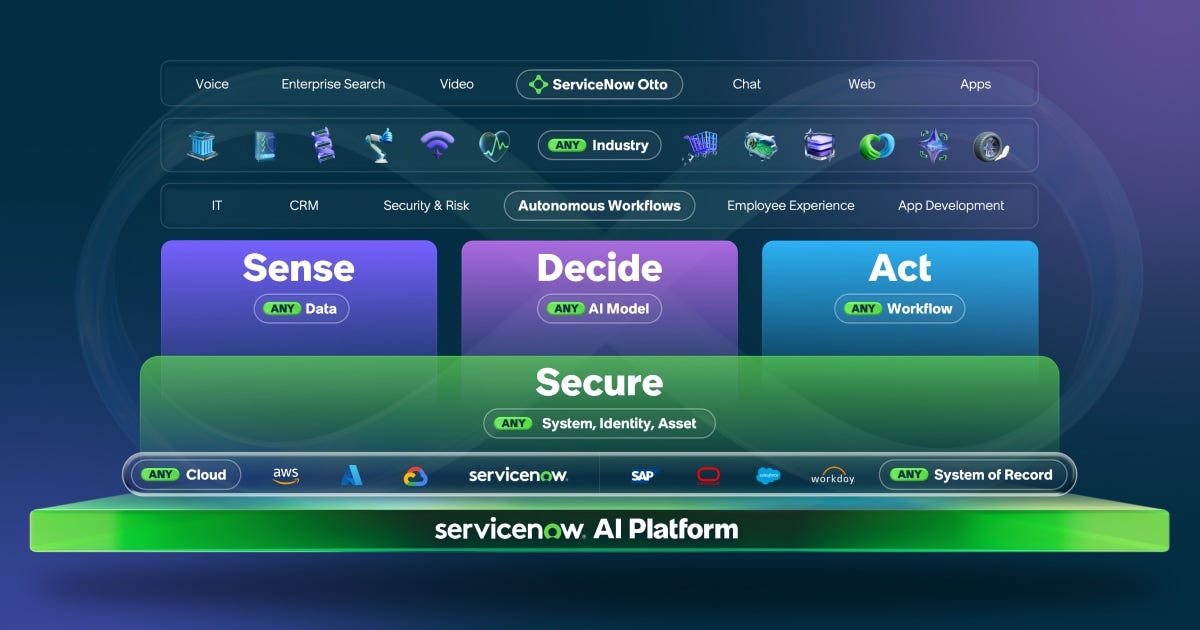
SA Elina Selianska Aug 28 4 clicks ServiceNow targets $30 billion in FY2030 revenue and a Rule of 60+ as it expands premium agentic AI offerings and consumption-based pricing.
NTG Clarity’s $18.6M of Q2 service revenue sat in contract assets, while $4.6M cash burn cut cash to $2.85M and raises liquidity concerns.
S Wolf's Substack Aug 28 8 clicks
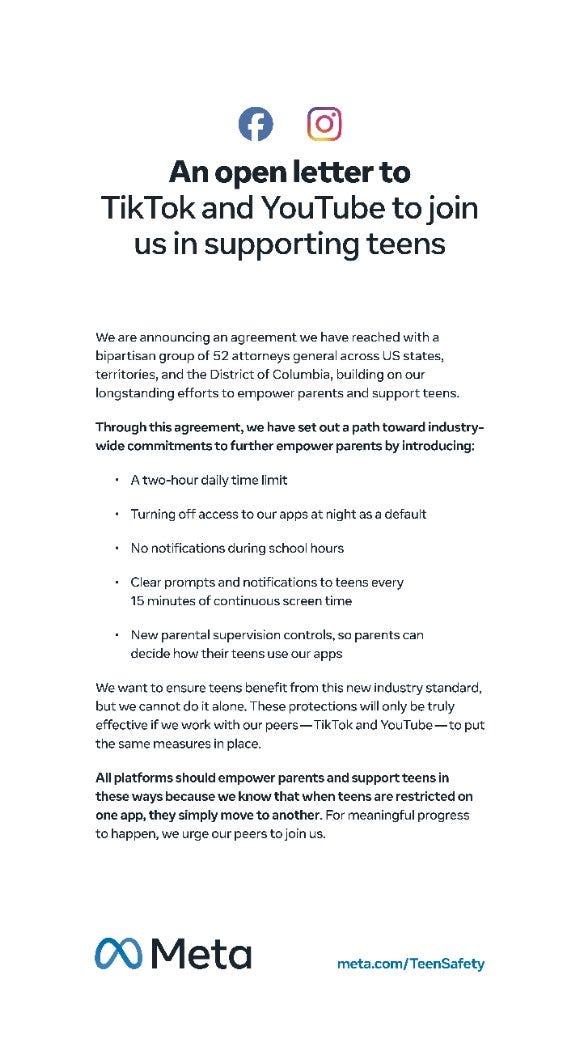
Meta’s $18 billion teen-addiction settlement makes $5.3 billion contingent on YouTube and TikTok adopting matching restrictions, while…
S MBI Deep Dives Aug 28 7 clicks
StandardAero’s exclusive engine licenses and LEAP aftermarket position underpin a projected rise in LEAP revenue from $100 million in 2025…
S Latticework by MOI Global Aug 28 1 click
TSOH Weekly Roundup tracks Dick’s Sporting Goods’ Foot Locker setback and Brown-Forman’s internal debate over a potential Pernod Ricard…
S TSOH Investment Research Aug 28