Ondas reported $167.5 million in Q3 revenue but spent $562 million of cash, halved gross margin and fell below its $6 stop level.
BL Cestrian Capital Research 7h ago 3 clicks
Offshore Radar maps 160-plus listed offshore rigs, contracts, day rates and uncontracted capacity through 2029.
S Cannibal Stocks 8h ago 5 clicks
Travere Therapeutics' FILSPARI has two FDA approvals and is driving revenue growth, while TVTX shares have nearly tripled since August 2025.
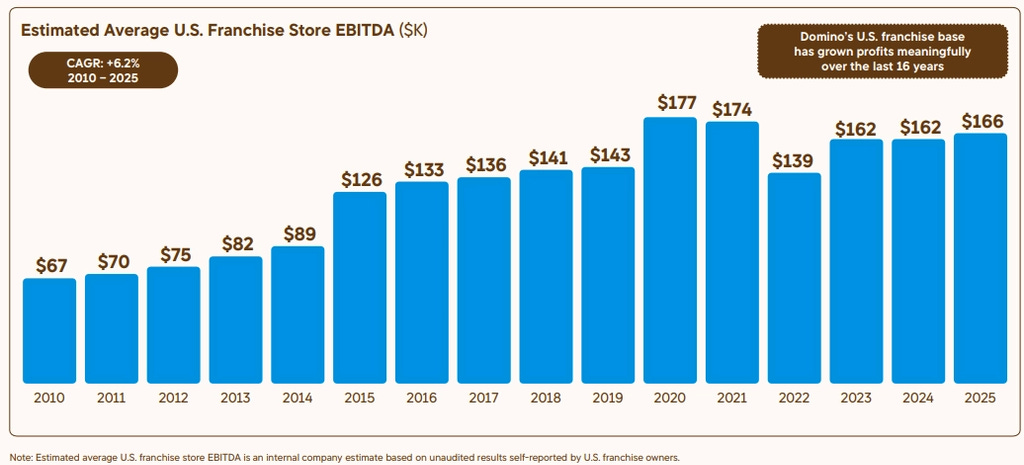
SA Out of Ignorance 9h ago 1 click Domino’s built PULSE, online ordering and Pizza Tracker into a delivery machine, driving 10% annual global retail sales growth after its…
S scuttleblurb 10h ago 3 clicks
Nubank and MercadoLibre update target prices as Brazil’s 9% real rates, weaker currency and tighter credit favor their cost advantages and…
S Jimmy's Journal 11h ago 3 clicks
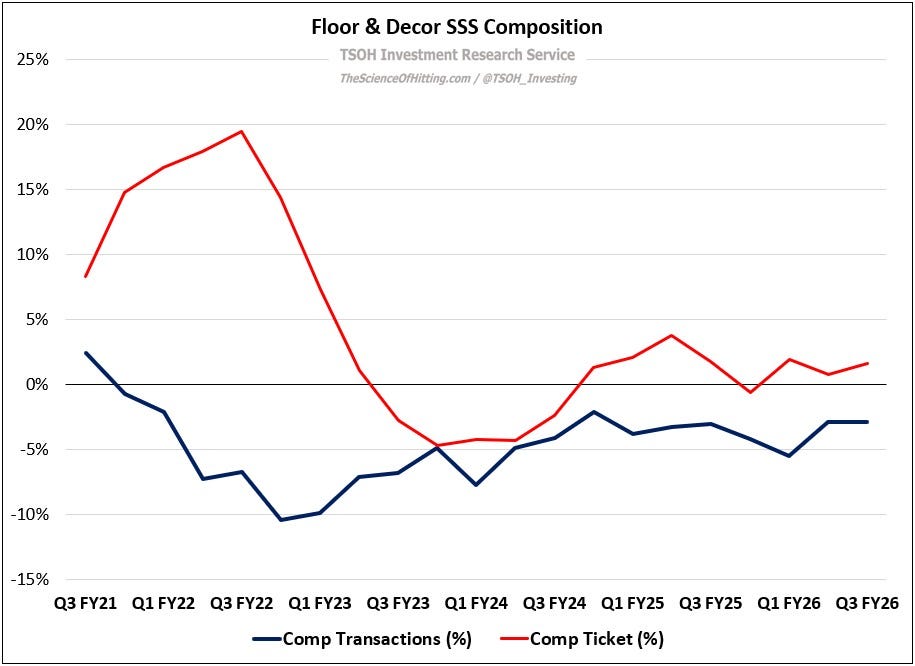
Floor & Decor has logged 20 straight quarters of comp transaction declines, with Q3 quarter-to-date same-store sales down about 3.8% as…
S TSOH Investment Research 11h ago 4 clicks
HCI Group grew Q3 revenue 13% and net income 27%, with $2 billion of invested assets driving investment income.
SA Given Mahlangu 13h ago 3 clicks TPG trades 20% below its average distributable-earnings multiple despite the fastest fee-related earnings growth among alternative…
S Capital Employed 21h ago 8 clicks
CDW CEO Chris Leahy says AI spending is entering a second wave focused on putting technology to work in everyday consumption.
BL The Technology Letter 23h ago 3 clicks
American Tower’s wireless network stayed operational during the FAA ground stop, while CoreSite lifted its 2026 data center revenue growth…
SA Brad Thomas 31h ago 3 clicks JBTM · long JBT Marel is an enduring food-equipment business with low AI risk, automation upside and favorable GLP-1 exposure.
BL Value Investors Club May 26
PayPal faces a $60.50-per-share buyout offer from Stripe and Advent, with a rejection or counteroffer above $80 viewed as more likely.
S Hidden Rock Capital's Newsletter Jul 15
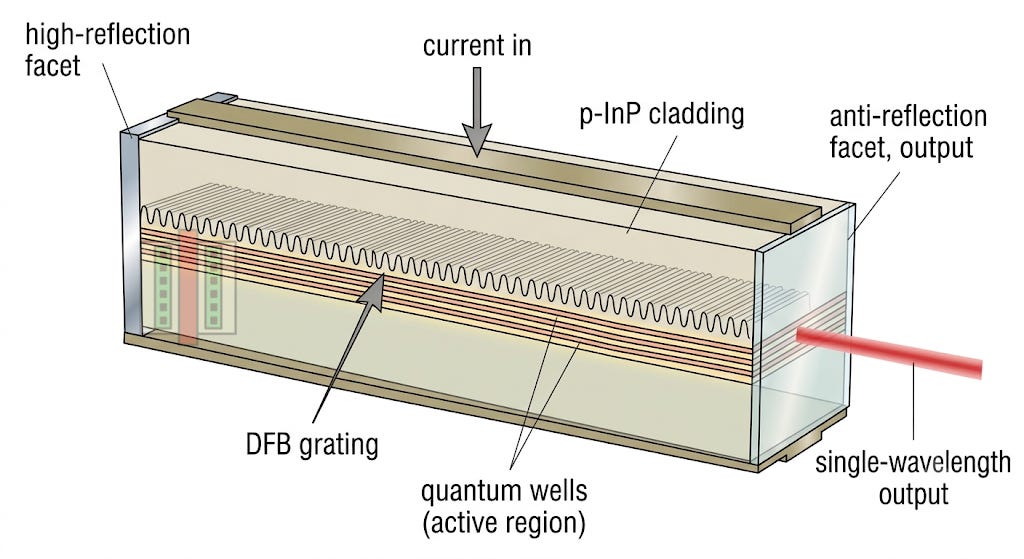
Lumentum’s InP DFB laser design for co-packaged optics traces to 2007 work and faces heat, linewidth, light-extraction and optical-damage…
S Vik's Newsletter Jul 15
Rebound Capital's July 2026 watchlist puts AeroVironment and Coinbase under review after UnitedHealth rose more than 70% from its low.
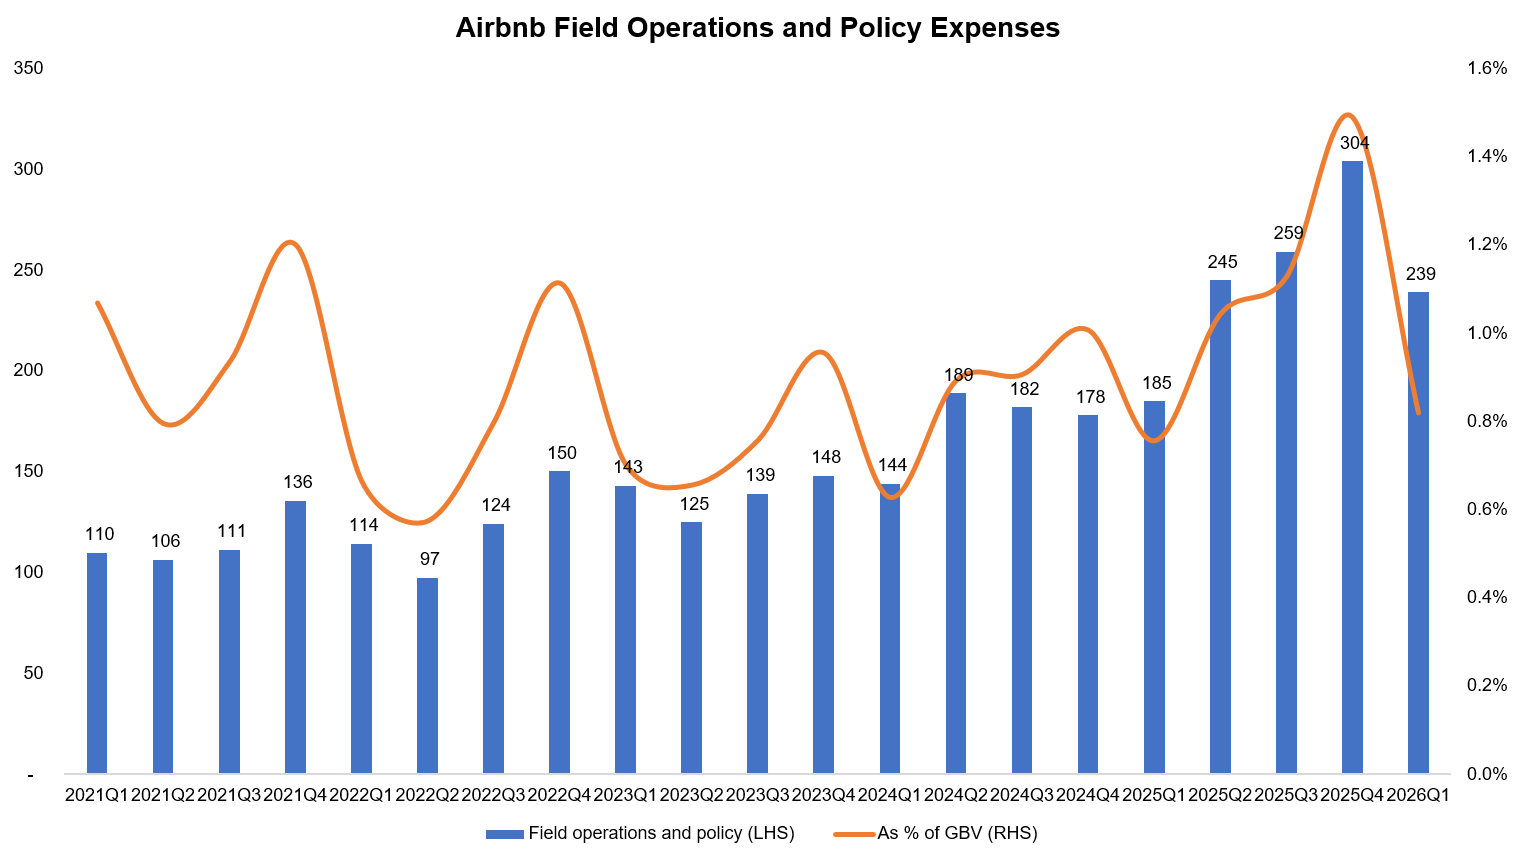
Airbnb spent 1.1% of 2025 GBV on field operations and policy as regulatory costs persisted; New York’s short-term-rental crackdown cut…
S MBI Deep Dives Jul 15 3 clicks
CBIZ activist Ryan Bunn urges ending buybacks, issuing equity and resuming bolt-on acquisitions to delever after the $2.3 billion Marcum…
YT Yet Another Value Podcast Jul 14 2 clicks
A digital market-infrastructure platform dominant in rates and expanding in credit trades at 22 times free cash flow, with 45%+ FCF margins…
S Aurelion Research Jul 14
AutoZone compounded sales, margins and store growth before Eddie Lampert’s 1997 investment, while later buybacks reduced its share count…
S The Owner's Memo Jul 14
Bloom Energy’s AI data-center fuel-cell growth plans face scrutiny over scandium supply, with Hunterbrook alleging China dependence and…
S Doomberg Jul 14 1 click
Credo Technology sells active copper cables for AI data centers, with revenue rising 126% then 206% as Amazon, Microsoft, Meta, Oracle and…