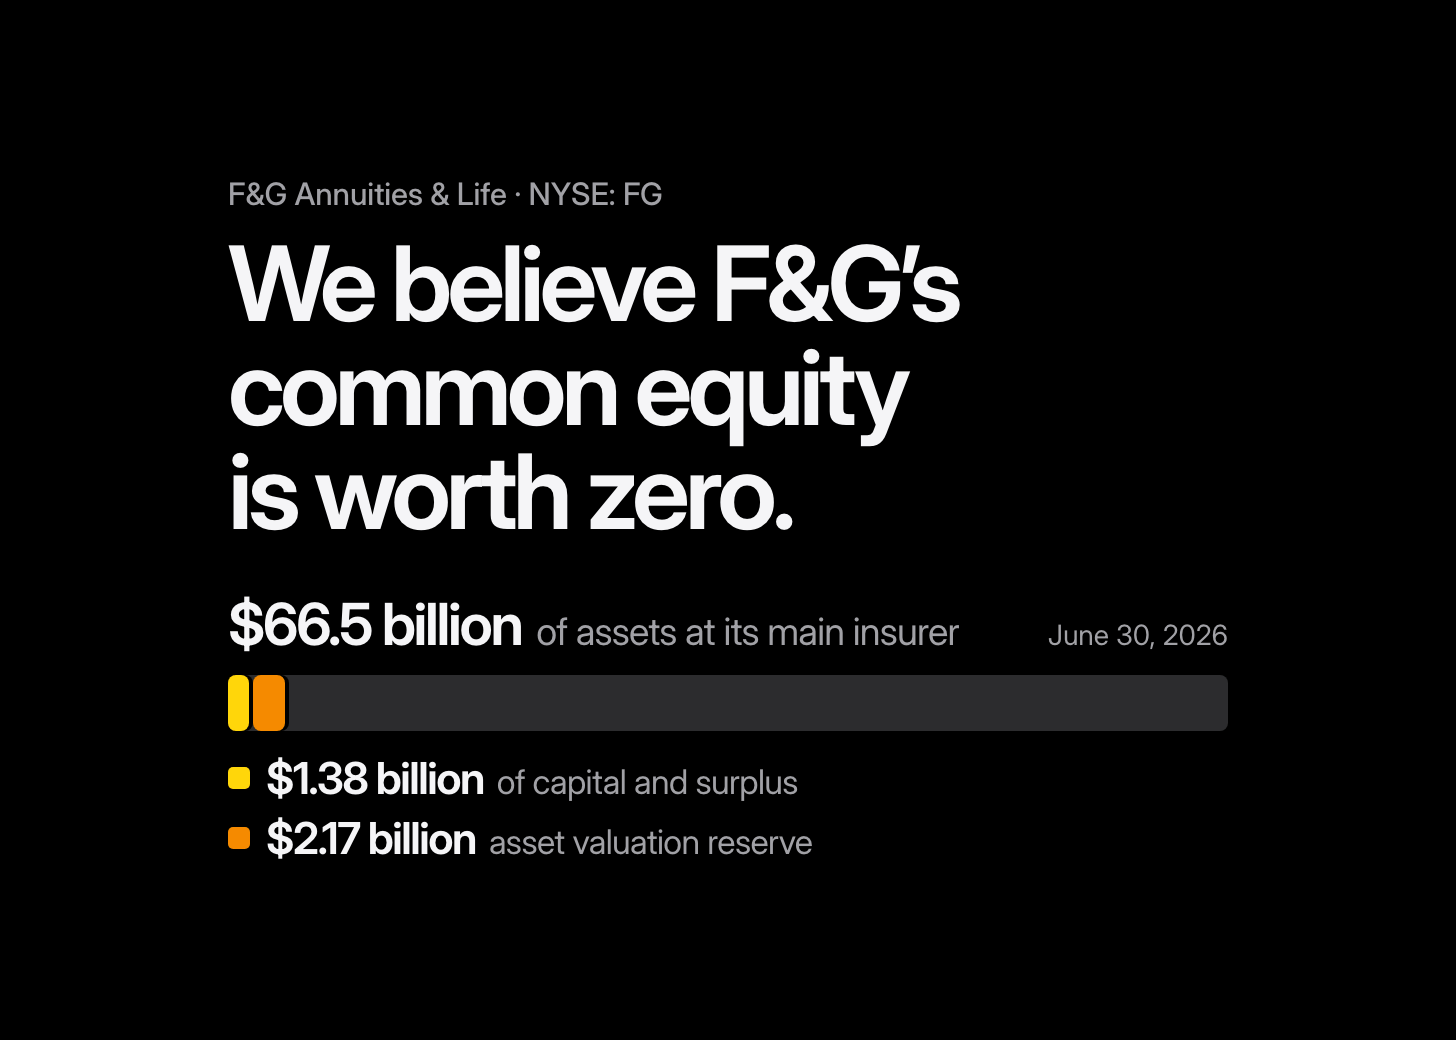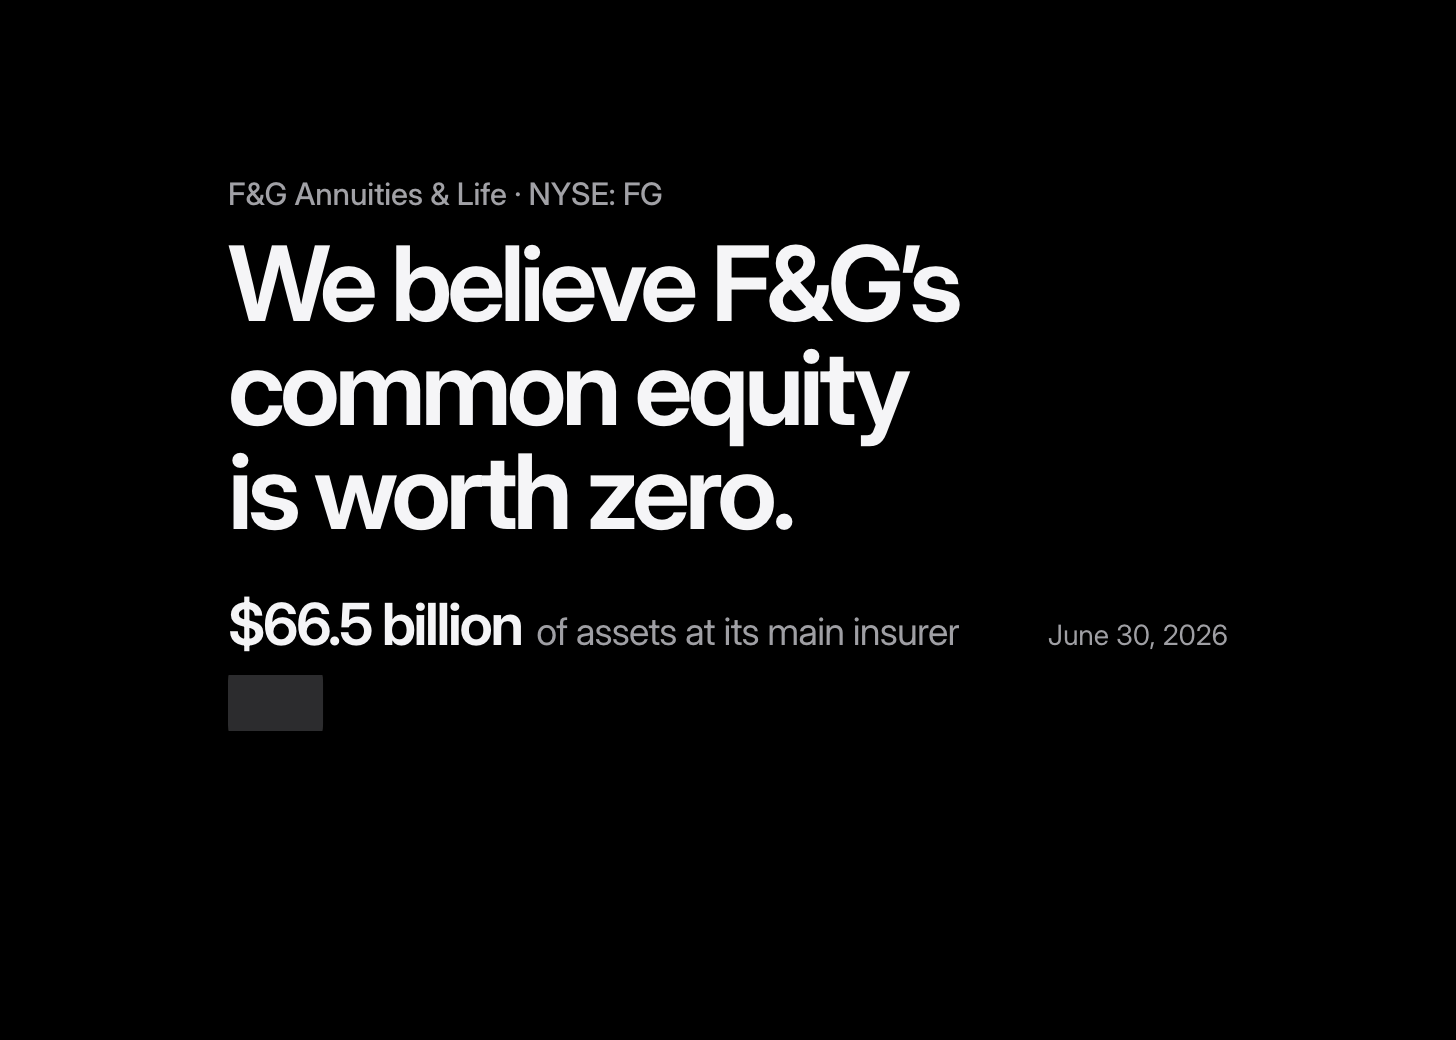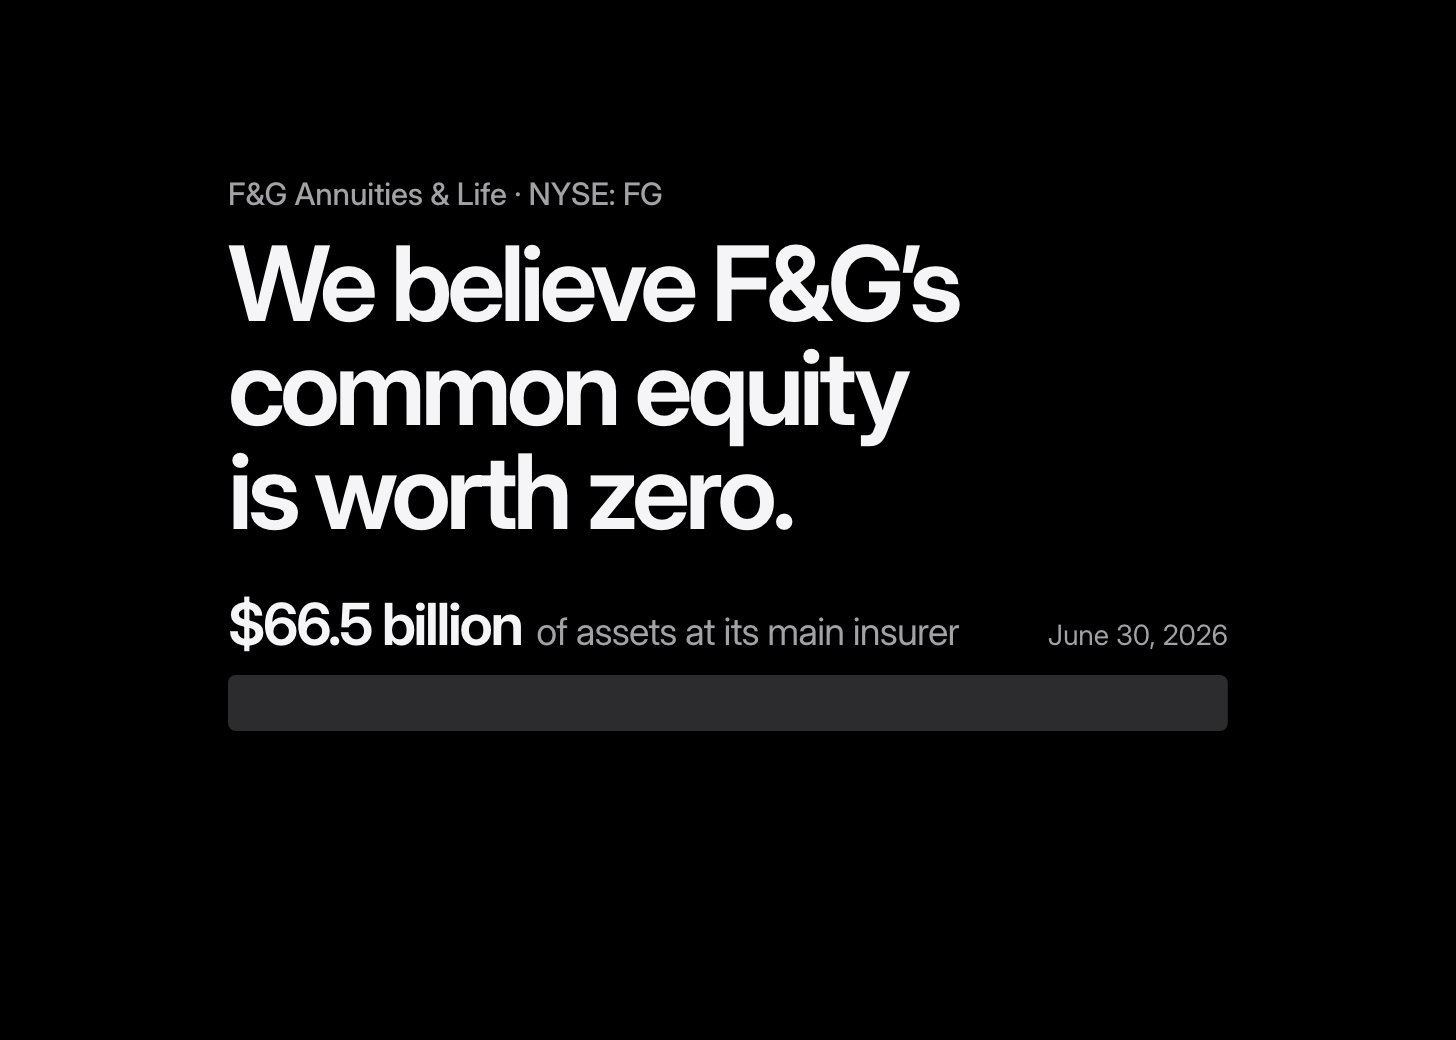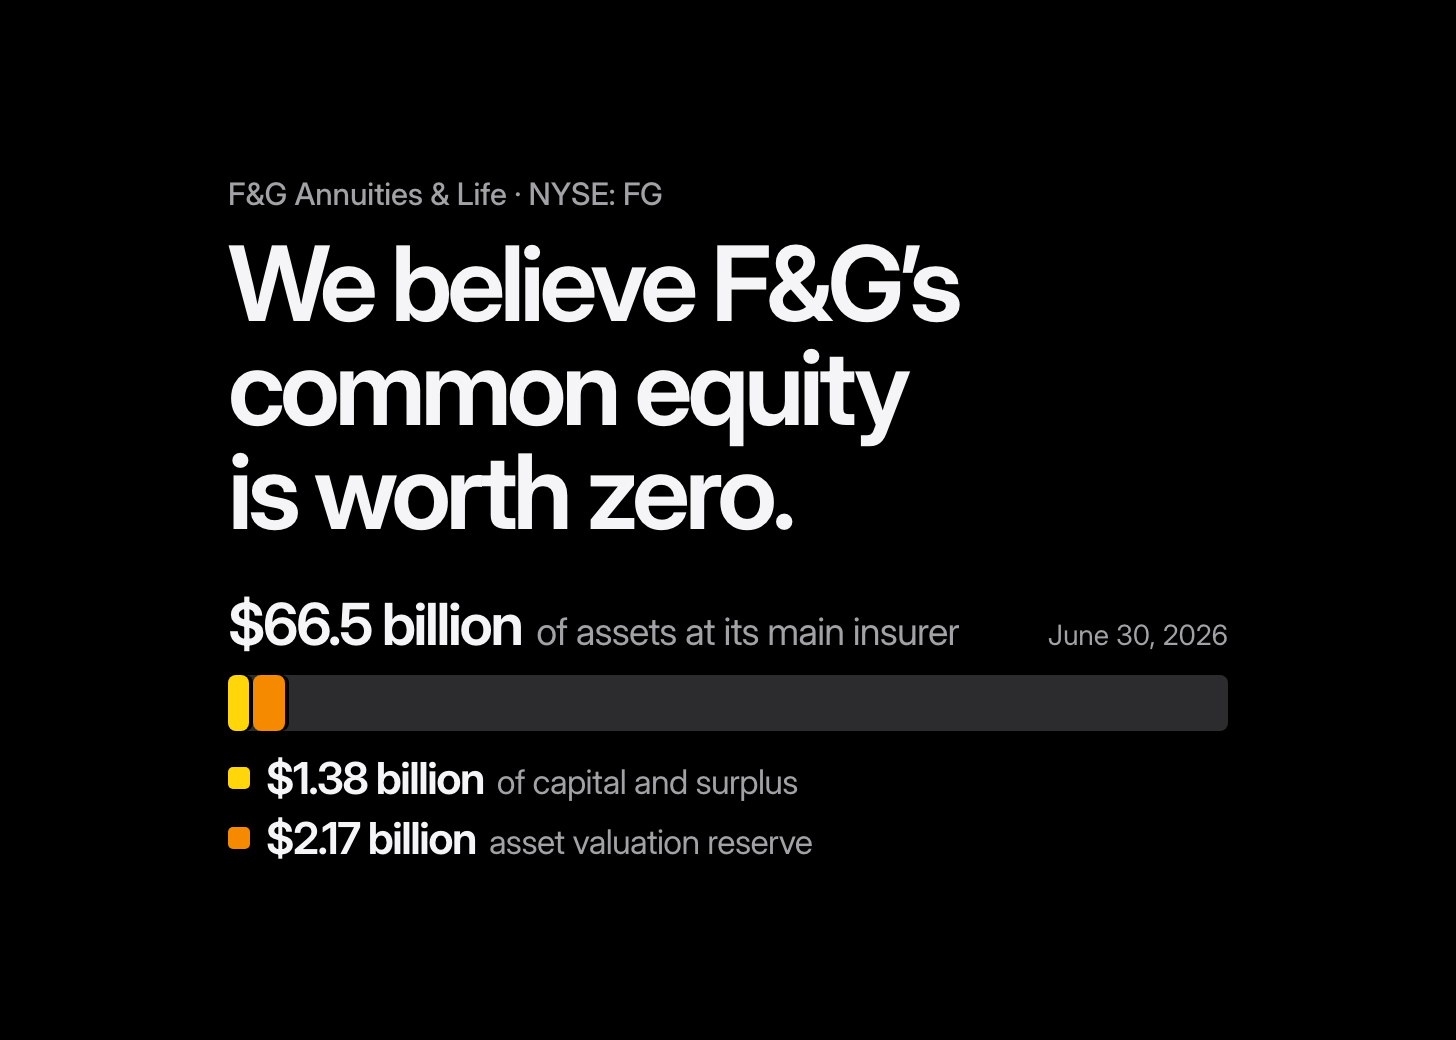SA Tech and Growth 2h ago CoreWeave targets 2 GW of active compute capacity, backed by high GPU rental rates, fast paybacks and a growing backlog despite a…
S Monte Independent Investment Research 4h ago 4 clicks
Sprouts Farmers Market is rated a buy at $50 after a 40% decline, contingent on maintaining store economics as same-store sales and margins…
SA Louis Liu, Esq 5h ago Alternative asset managers earn durable fees on committed capital, but 2026 losses followed retail-credit redemptions, lender-fraud…
S Latticework by MOI Global 6h ago 3 clicks
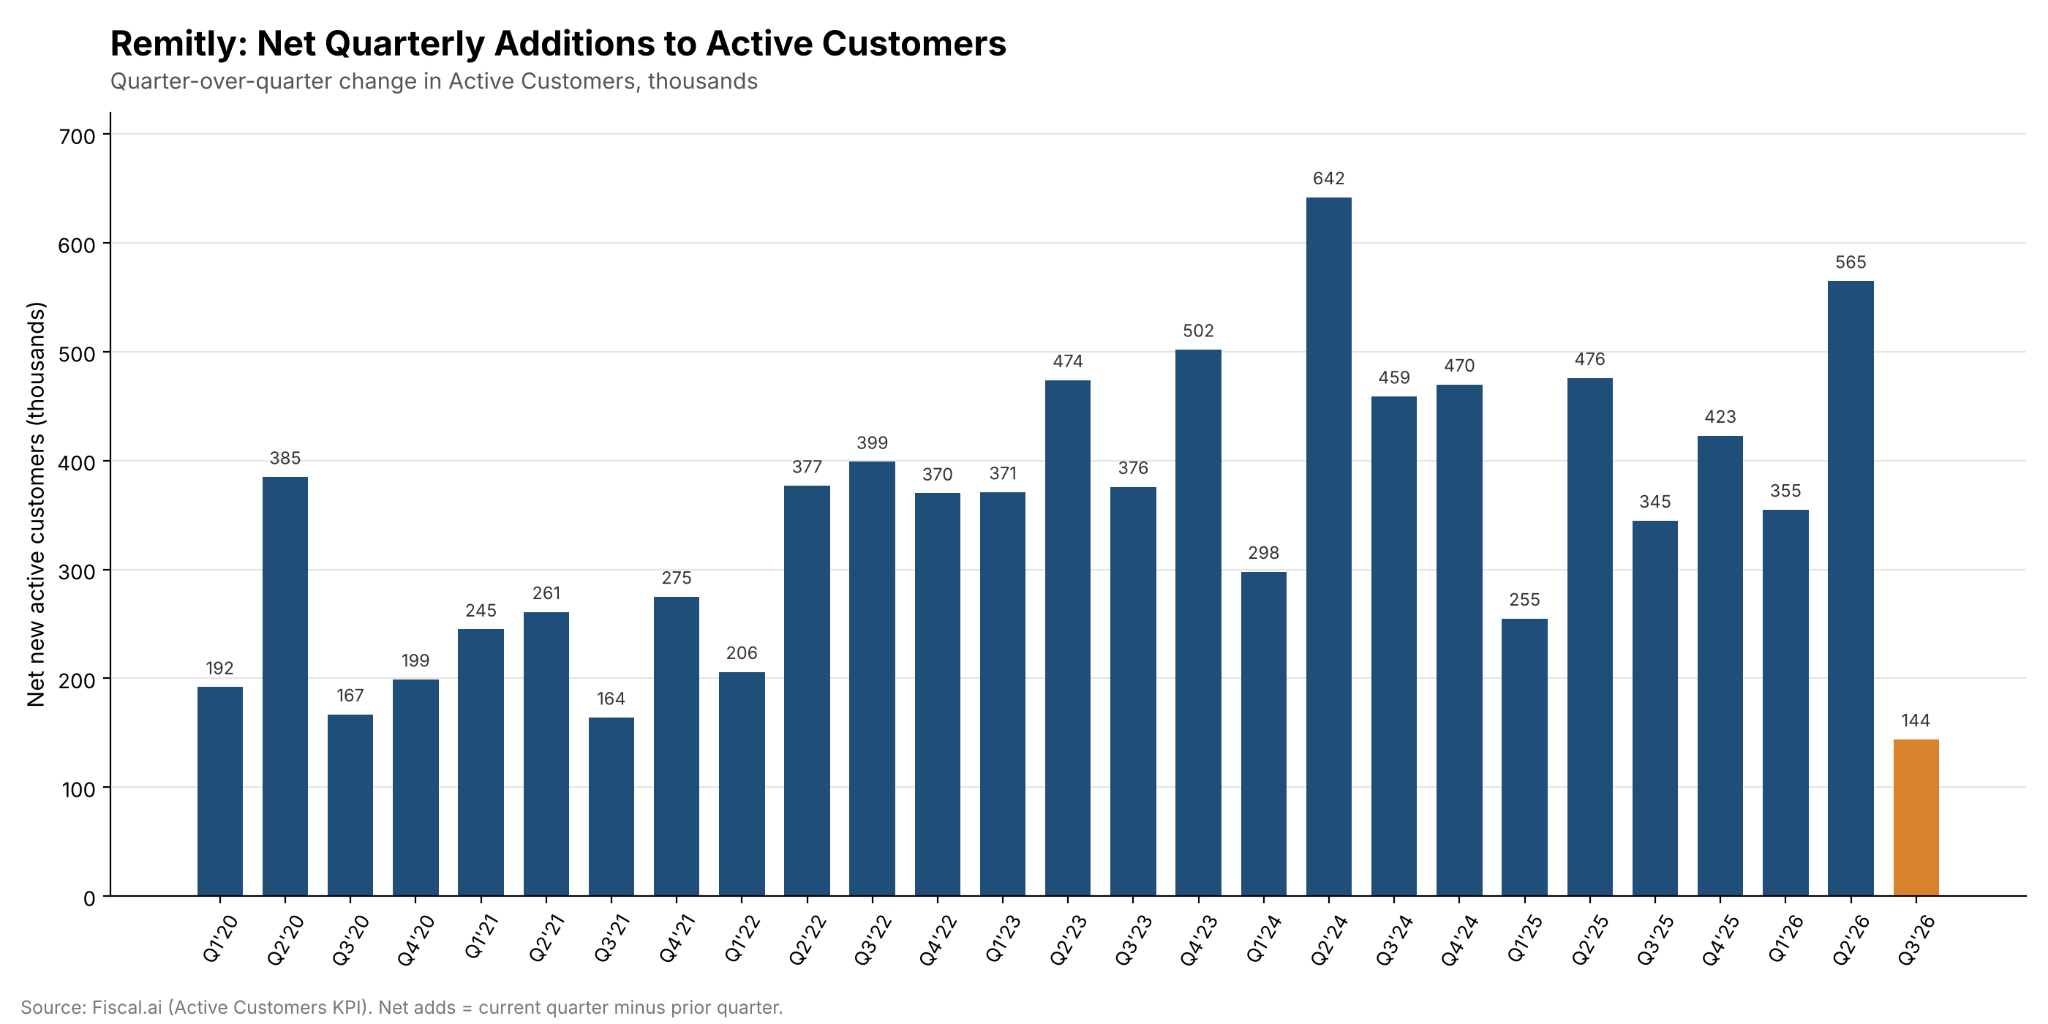
Remitly’s Q3 keeps its remittance growth thesis intact as spending cards, memberships and credit products target $1 billion in annual…
S Emerging Moats Research 8h ago 3 clicks
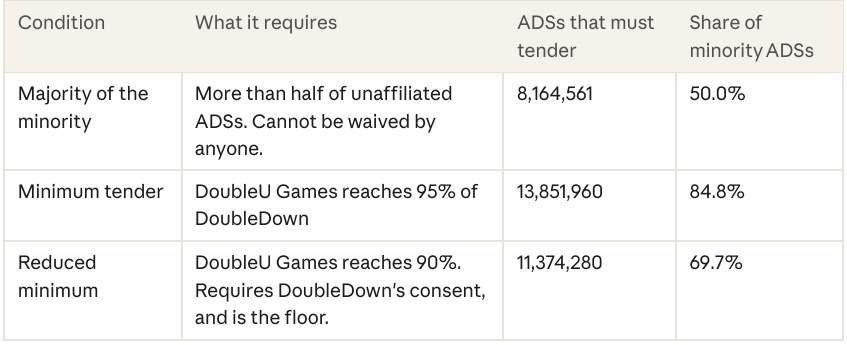
DoubleU Games raised its all-cash tender offer for DoubleDown Interactive minority holders to $16.25 per ADS from $11.25 after net cash…
S The Value Road 25h ago 4 clicks
Bloom Energy’s fuel cells offer data centers grid independence as Q3 operating income rose 518% on 138% revenue growth.
SA Ignacio Planas Gonzalez 12h ago 2 clicks QXO's Q3 sales rose 79% to $4.9 billion after TopBuild and Kodiak acquisitions, while acquisition debt lifted interest expense to $163…
S SixSigmaCapital: Navigating the Financial Markets 13h ago 2 clicks
Nvidia CEO Colette Kress signals a pullback from the financial schemes pursued under Jensen Huang.
BL The Technology Letter 16h ago 1 click
IEH Corporation posted Q2 revenue growth of 51% to $10.7 million and a record $56 million backlog, led by defense and medical demand.
BL Atrium Research - Equity Research 16h ago 1 click
GrabAGun’s $34 million Camfour acquisition cuts pro forma net cash to about $54 million as sales decline, losses widen and its buyback…
S XIX Value 18h ago 2 clicks
NVIDIA faces DOJ antitrust probes alongside inquiries into Megaspeed and Super Micro, after charges over $2.5 billion of GPUs allegedly…
S Cassandra Unchained 20h ago 4 clicks
Coursera trades at roughly $150 million enterprise value after Pale Fire Capital took 14.7%, with cash and Treasuries covering 83% of its…
S Latticework by MOI Global 23h ago 6 clicks
UniQure’s Huntington’s disease BLA has a May 1, 2027 priority-review date, with an FDA advisory committee expected in late first quarter.
S Triple S Special Situations Investing 23h ago 2 clicks
Floor & Decor cut its 2026 outlook again, with EBITDA guidance falling to $535-550 million and 2027 openings slowing to 10-15 as housing…
S MBI Deep Dives 23h ago 3 clicks
F&G’s main insurer held $66.5 billion of assets against $1.38 billion of statutory capital, while private credit, reinsurance dependence…
S Mispriced Assets 24h ago 4 clicks
AutoNation’s new CEO Mike Manley brings Jeep and Fiat Chrysler experience after the dealer chain cycled through three leaders in 30 months.
S Cannibal Stocks 25h ago 3 clicks
Quanta Services' backlog rose 63% year over year to $64 billion as shares fell 30%, with AI and power-infrastructure demand driving revenue…
S Monte Independent Investment Research 25h ago 5 clicks
A hypothetical Nvidia succession scenario names Colette Kress interim CEO and favors Arm's Rene Haas or Nvidia's Ian Buck as permanent…
S Key Context by Tae Kim 25h ago 4 clicks
Petrobras posted record 3Q26 production and earnings, but higher investment needs are shrinking dividends as a possible Lula IV government…
SA Bernard Zambonin 26h ago 8 clicks