Another Haircut with Avy the Barber
SoFi’s stock case hinges on interest rates, tangible book value and private-credit loan sales after its $1.5 billion equity offering.
SoFi’s stock case hinges on interest rates, tangible book value and private-credit loan sales after its $1.5 billion equity offering.
@AtlasShrug1 The JV with Sharon AI. Look into that. The PPA gives away 5% equity for the right for $NUAI to buy power from Vista.
Because they are bullshiting everyone. $NUAI https://t.co/FMGotqQuEr
@TarekAntaki I bought $CHTR stock today as well, Godspeed!
@EmmaStockNotes Maybe im stupid but $docu biz model just seems like a shitco to me 😬
@EdgeCGroup $chgg kick em while theyre down
Quick $BRUN 8-K update released today. P.S. Got the info and analysis done instantly via SECSift, then sent to my email! 👀 https://t.co/7L1DxtZYNH
Alphabet's EPS miss came from a SpaceX stake loss, while 24.7% revenue growth and a $561 billion Cloud backlog counter free cash flow…
 Cain Lee 1 click
Incyte reported Q3 FY26 revenue of $1.56 billion, up 14%, while a $1.23 billion Vega acquisition charge drove a $708 million operating loss.
Merck reported Q3 FY26 revenue of $18.1 billion, led by $8.6 billion in KEYTRUDA sales and 93% WINREVAIR growth, while raising and…
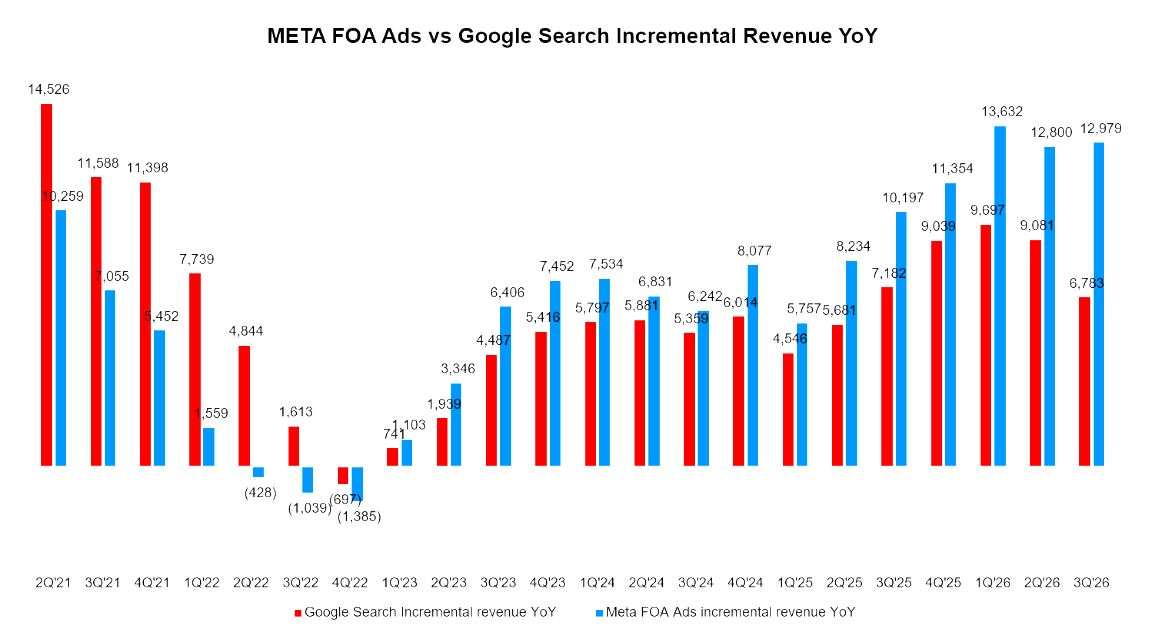
Alphabet’s Search growth slowed to 12% as Cloud revenue more than doubled, while quarterly free cash flow stayed negative amid the capex…
CoStar’s 3Q26 revenue growth slowed to 14% as bookings fell to $37 million, while cost cuts lifted EBIT margin to 8.8%.
Simran Jeet Singh recounts pricing oil through WTI’s -$37.63 collapse, then explains crypto perpetual funding arbitrage, market making and…
Carpenter Technology fell 25% after Q1 2027 despite revenue rising 9%, EPS up 34%, and commercial aerospace bookings up 25%.
GE Vernova raised guidance for a third straight quarter as Power and Electrification drove backlog growth, while Wind showed an early…
 Melissa Tucker 2 clicks
Alphabet reported $127.6 billion in revenue, up 25%, as Google Cloud doubled to $30.7 billion and 36.2% margins.
Alamos Gold targets nearly 1 Moz of annual production by decade-end as Island Gold shaft commissioning offsets recent Young-Davidson…
 Bang For The Buck 1 click
ServiceNow’s Q3 revenue rose 20.5% to $4.11 billion, while non-GAAP EPS missed consensus and fourth-quarter cRPO growth guidance slowed to…
One Stop Systems grew Q3 continuing-operations revenue 36% to $12.6 million, raised FY2026 revenue guidance to $45 million, and used $11.8…
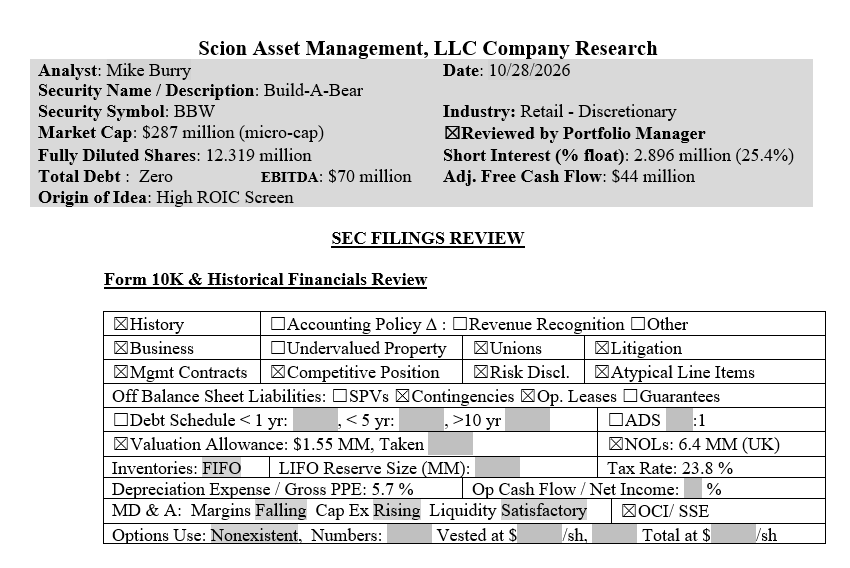
Build-A-Bear’s lease overhaul, off-mall expansion and partner-led wholesale growth reshaped a debt-free retailer with $80 million EBITDA,…
Google’s AI search could improve ad economics, while Amazon protects its retail ad funnel from shopping agents and specialty insurers face…
Alphabet’s $200B 2026 capex and weaker AI-search monetization contrast with Microsoft’s accelerating Copilot and Azure momentum; the review…
Mattel, Winnebago and PayPal lead 37 special situations spanning activist campaigns, buybacks, M&A and strategic alternatives.
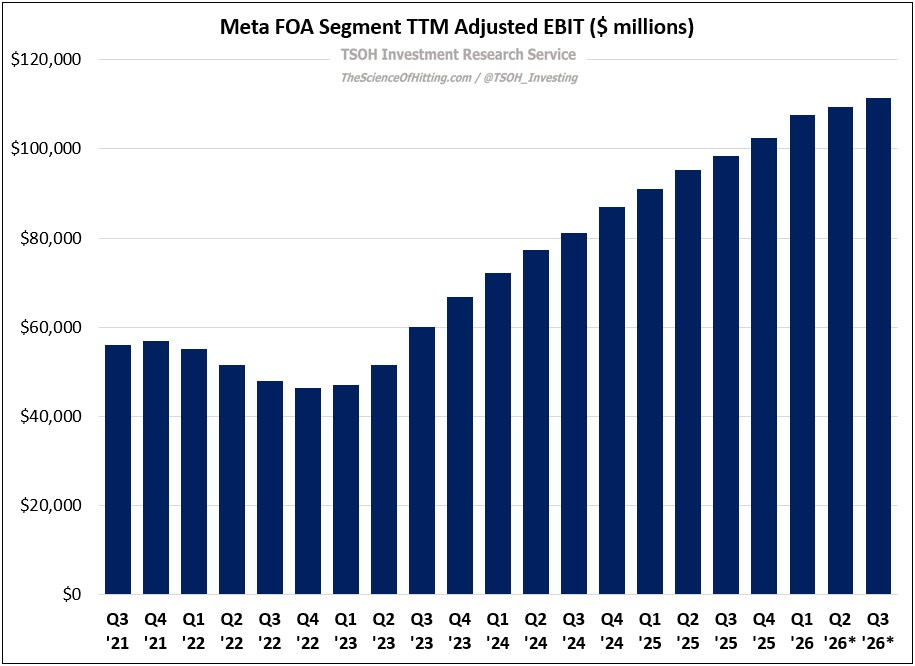
Meta's non-cancelable commitments reached $455 billion as FY26 capex approaches $140 billion, driving expense growth and 700-basis-point…
Duos Technologies, DUOT, has shifted to modular edge data center pods, with Q2 revenue up 30% to $6.18 million and FY27 revenue guided…
 Shareholders Unite 2 clicks
Amphenol and other copper-connectivity suppliers benefit as copper remains essential inside AI racks, where low-voltage, high-current power…
Undercovered Dozen profiles 12 lesser-covered stocks, including i-80 Gold, Hercules Capital’s 11.5% yield and sector-specific catalysts at…
 The Undercovered Dozen 3 clicks
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.