Tower Semiconductor Deep Dive
Tower Semiconductor’s low-loss photonics chips halve lasers in 1.6T optical modules, supporting a $680 million annualized photonics run rate and customer wafer prepayments through 2027.
Tower Semiconductor’s low-loss photonics chips halve lasers in 1.6T optical modules, supporting a $680 million annualized photonics run rate and customer wafer prepayments through 2027.
$AAPL has outperformed SOX by around 40% since June https://t.co/6G1LMCerLs
@ReturnsJourney I bought some $JD recently. You can generally make some money buying China at long-term support and selling into rallies. But it's hard to permanently rerate until CCP is gone.
@alexandr_wang @finkd FYI, the market is speaking and saying they don’t want you guys to issue “hundreds of billions” of stock for Muse $META business results were fantastic. Just overshadowed by fear of dilution.
Bernstein with the research report title of the week: CoreWeave ($CRWV): Core-We’ve got bills to pay.
@amitisinvesting Yeah $AMD is a great example you gave. It even got the popular nickname “Advanced Money Destroyer” for awhile… Then it had that massive rally to a $1T valuation, but lot of people didn’t give it time to play out.
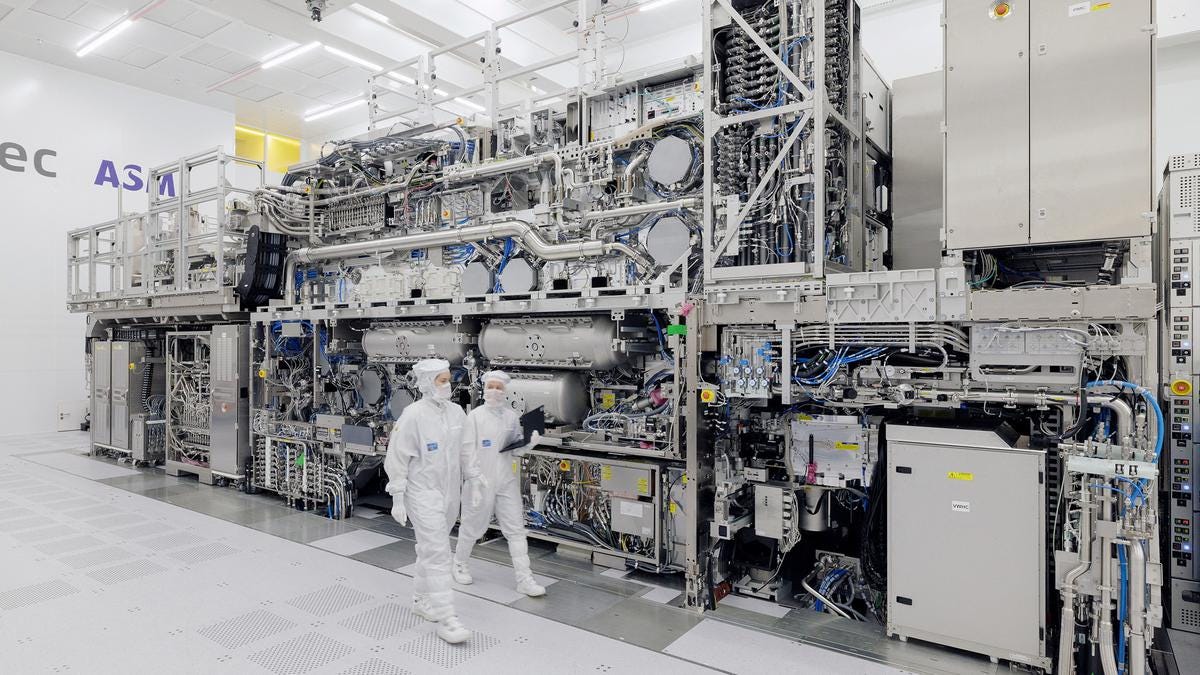
ASML’s €230 million EUV machines underpin advanced AI chip production, with demand booked through 2028 after nearly $9 billion and two…
Netflix pairs international engagement, free cash flow and buybacks with plans for double-digit revenue growth, margin expansion and larger…
 Juxtaposed Ideas 6 clicks
Petrobras’s Morpho-1 well revived hopes that Brazil’s Equatorial Margin can become a major new oil frontier after hydrocarbons were…
 Dhierin Bechai 2 clicks
CoreWeave’s rising debt yields and fading confidence in AI data-center economics frame a weekly review of Meta, Tesla, SpaceX, Netflix,…
CoreWeave's financial statements point to a business model familiar to the authors after a closer review of the AI infrastructure company.
 Star Investments 7 clicks
Bloom Energy’s Q3 FY26 revenue rose 138% to $1.24 billion as datacenter power orders lifted operating margin to 18%; capex drove $181…
Philip Morris reported Q3 growth across heated tobacco, combustibles and e-vapor in Europe while gaining U.S. nicotine-pouch share.
Amazon’s Trainium3 adds native PyTorch training support, targeting CUDA-trained researchers with standard APIs, eager mode and…
 TCEHY · long
Tencent, valued near $500 billion, is a long idea built on its Chinese gaming, social-network and advertising franchises.
Alphabet's Gemini 4 Argon aims to undercut rival AI models using proprietary TPUs, while Android, Siri and Google Cloud distribution…
 Dustin Quasney 2 clicks
CoreWeave’s $35 billion to $39 billion 2026 spending plan relies on debt as unsecured yields reach 15%, making its GPU cloud expansion a…
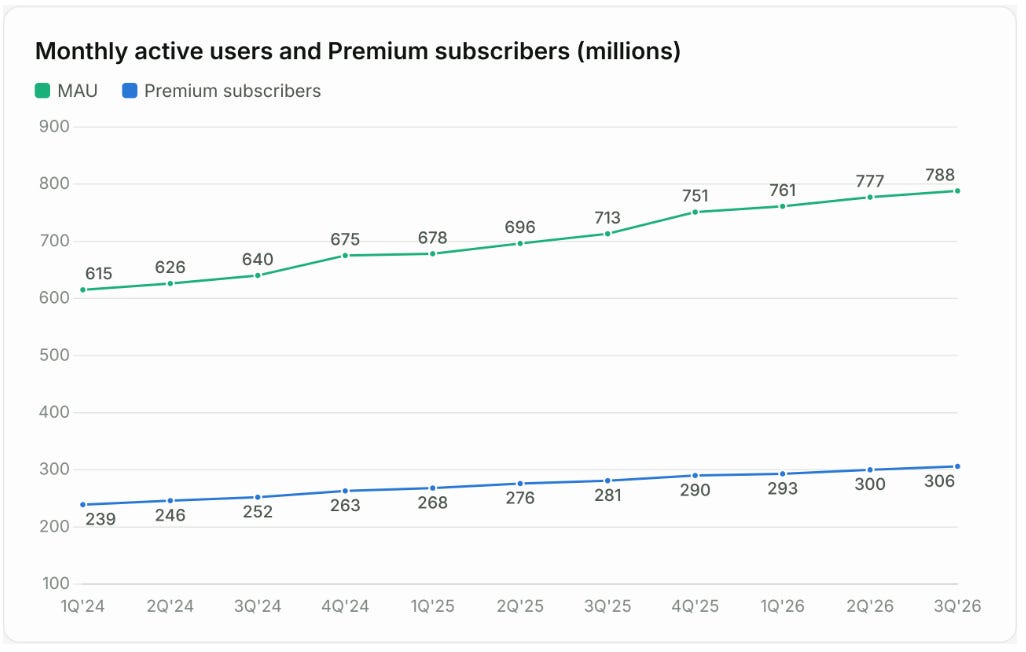
Spotify's third-quarter results met or exceeded guidance, with 306 million Premium subscribers and €672 million operating income, while…
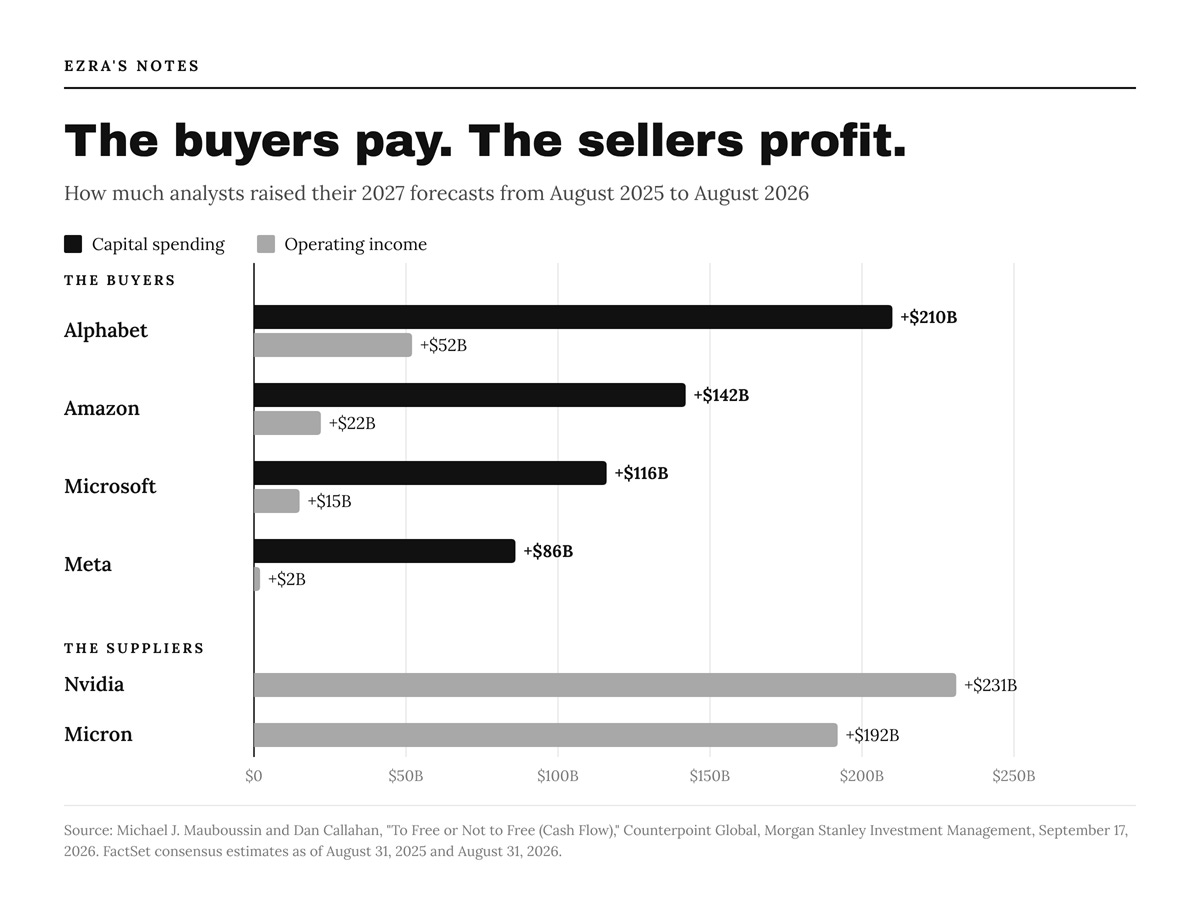
Alphabet, Amazon, Meta and Microsoft plan nearly $800 billion of AI infrastructure spending, testing whether incremental returns can stay…
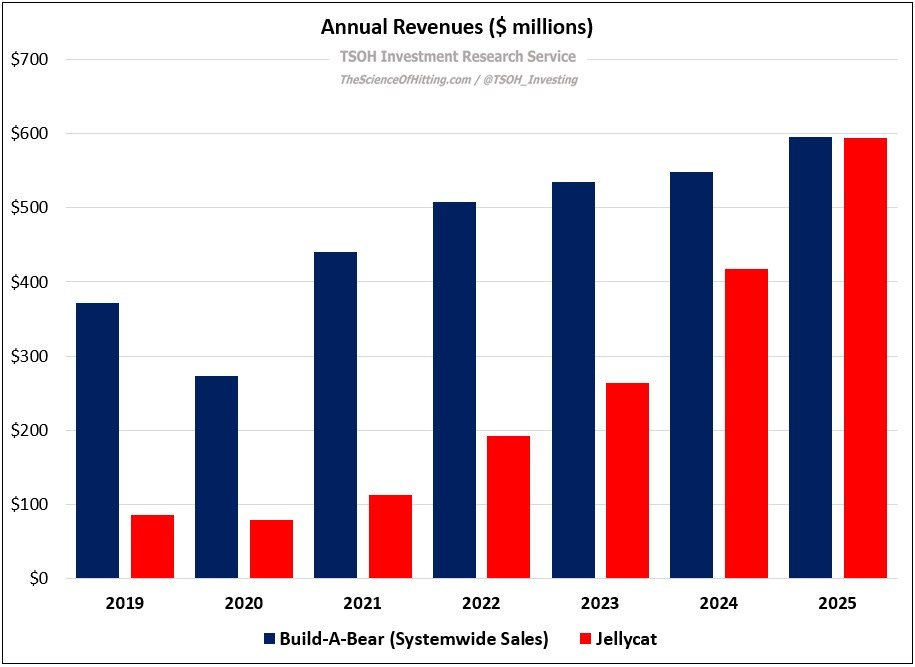
TSOH Weekly Roundup covers Ally’s improving credit and capital returns, Pepsi’s weak beverage brands, and Match Group’s plan to revive…
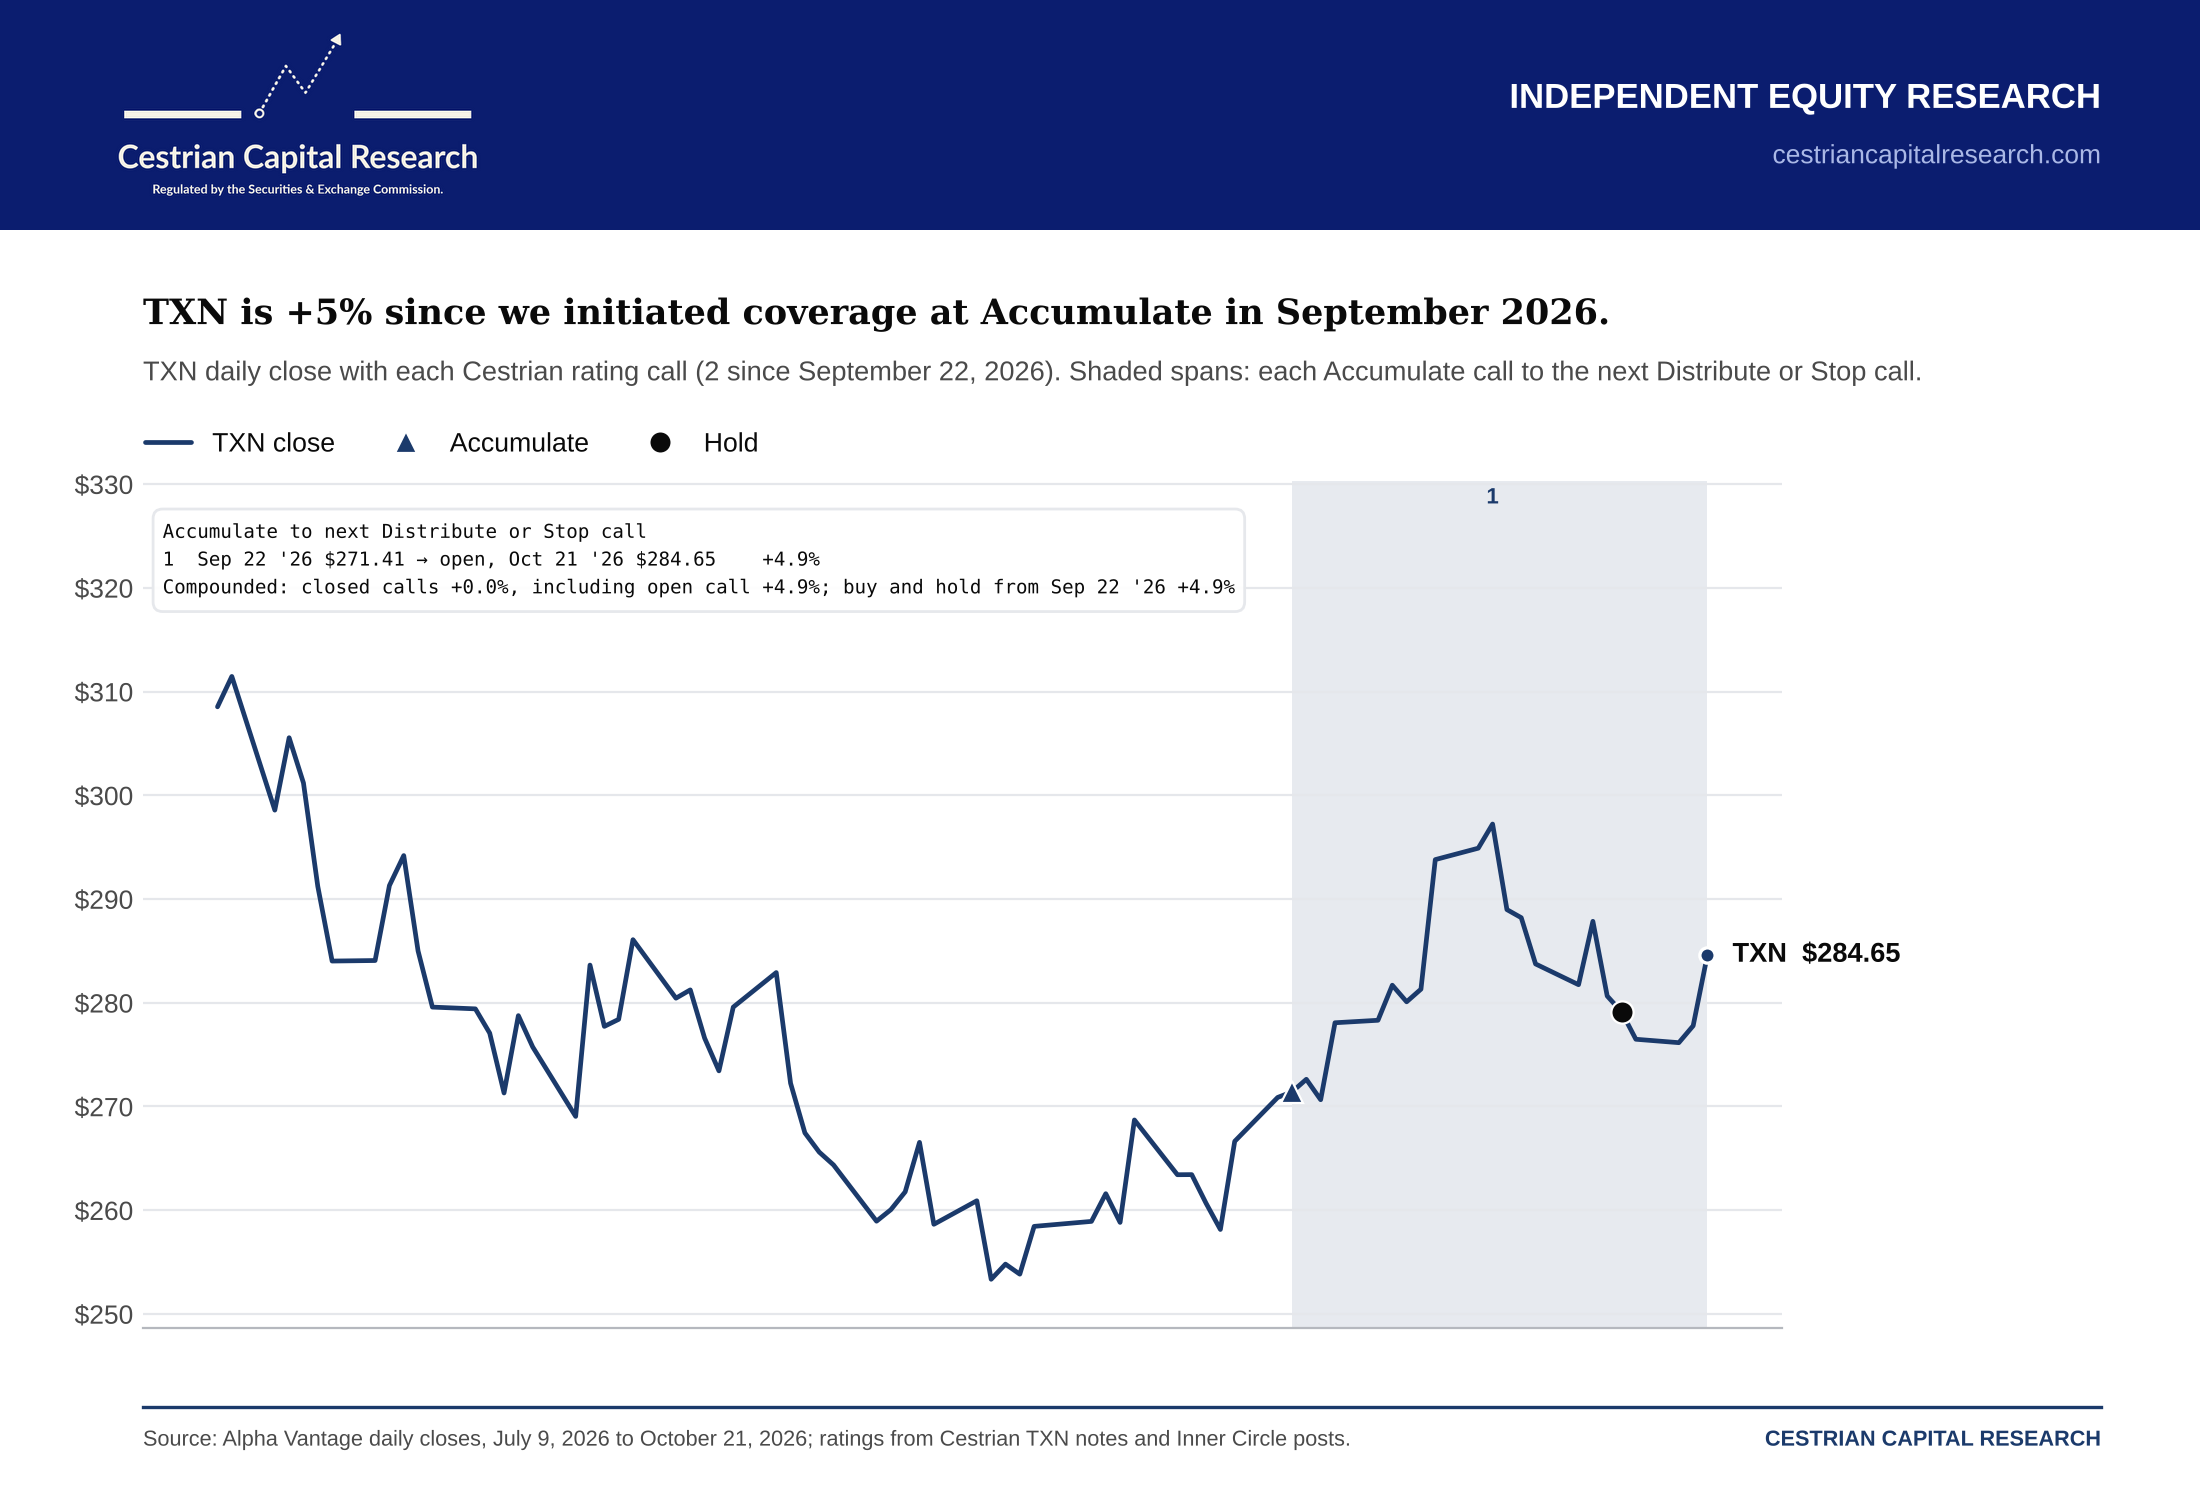
Texas Instruments reported Q3 revenue of $6.06 billion, up 28%, with 47% operating margin and Q4 guidance above seasonal norms; Cestrian…
ERock’s modular microgrids bridge data-center power gaps years before grid interconnects, with Meta and Anthropic projects filling capacity…
Medpace authorized $1 billion of buybacks through 2028 after Q3 revenue rose 8.5% to $716 million; service revenue grew roughly 12% as…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Dane Bowler
 David Zanoni
 Deep Value Investing Dhierin Bechai
 Dilantha De Silva Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Ryan Canady
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.