October 2026 Random Ramblings
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI premiums for Oura and home builders.
October 2026 market commentary covers SOLS’s cancelled merger, a hypothetical Starbucks-Chipotle deal, Russell 2000 weakness and AI premiums for Oura and home builders.
$META’s platform engagement is incredibly robust and healthy with a deep product pipeline. The business is fine. I understand the capex debate, and clearly the biz is today more capital intensive, but I’m sure Zuck will make the right decisions in the end. Weakness is likely a buying opportunity.
OpenAI’s CFO Sarah Friar also on a media tour spreading the good cheer… bullish $ORCL https://t.co/oymK8c7nVc
Sam Altman sounded a lot more at ease about his revenue ramp and was even bullish about his compute commitments (even saying they may have been too conservative) in this podcast. Given that he has been relatively quiet on the podcast circuit over the past year, I view this as a positive tell on OpenAI/$ORCL. https://t.co/yezInyb9XB
$MSFT is showing us how to have your AI cake and eat it too. Zuck should take notes
...."but we might not take the offer bc we have all these reasons to use the compute internally even though we missed ad revs" (basically) $meta https://t.co/ozJ63qcFIL
ASML’s €11.7 billion quarter benefited from €3.3 billion in installed-base sales and operating leverage, while the MATCH Act threatens…
Visa’s network economics support long-term compounding, but a 1.7–1.8 forward PEG and risks to high-margin payment revenues limit near-term…
 C Jessen 36 clicks
Applied Materials leads wafer-fab deposition and ranks third in etch, positioning it for tougher 3D chip manufacturing as investors weigh a…
First Tracks Biotherapeutics’ ANB033 posted stronger Phase 1b celiac efficacy than Teva’s IL-15 inhibitor, with $168 million funding…
 Equity Eagle 8 clicks
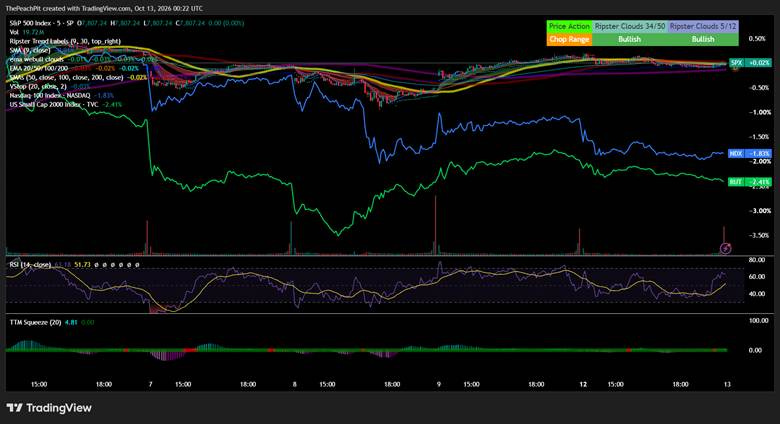
Howmet Aerospace is framed as a beneficiary of turbine and aircraft-engine demand, while J.B.
Lennar cut build times to 116 days and adopted an asset-light land model, while gross margin fell to 15.8% from 27.5% as land costs rose.
Lennar grew from a Miami builder into one of America’s two largest homebuilders, controlling land largely through options and land banks…
Lennar’s second audio program examines the homebuilder’s business for professional investors and housing analysts.
ASML reported Q3 sales of €11.7 billion, up 55% year over year, and guided Q4 sales to €14.2 billion to €15.2 billion amid capacity…
Eaton’s backlog, data-center, grid and aerospace demand, plus a 450–500 bp H2 2026 Electrical Americas margin recovery, support the growth…
 Value Capital Research 9 clicks
Asian insider buying rose 19% to US$2.4 billion across 930 September transactions, led by Grab CEO Anthony Tan’s US$30 million purchase…
 WDC · long
Western Digital, a hard-disk manufacturer, is pitched as a long after significant share-price moves deter investors.
ASML’s strong quarterly results failed to prevent a selloff, as AI investors focused on scarcity fears facing chip-equipment makers…
Apple HomeView raises questions about demand for expensive Apple devices built around subpar AI.
Corning’s NVIDIA-backed 10x fiber expansion, enterprise connector demand and carrier capacity plans frame its optical communications…
Apple is leaning on partner integration for the smart home, while Amazon faces strategic choices around AI agents.
Nvidia’s investor meeting features CFO Colette Kress and IR and Strategic Finance VP Toshiya Hari.
AMD CEO Lisa Su says demand for AI inference and CPUs continues to rise as computing capacity becomes more valuable.
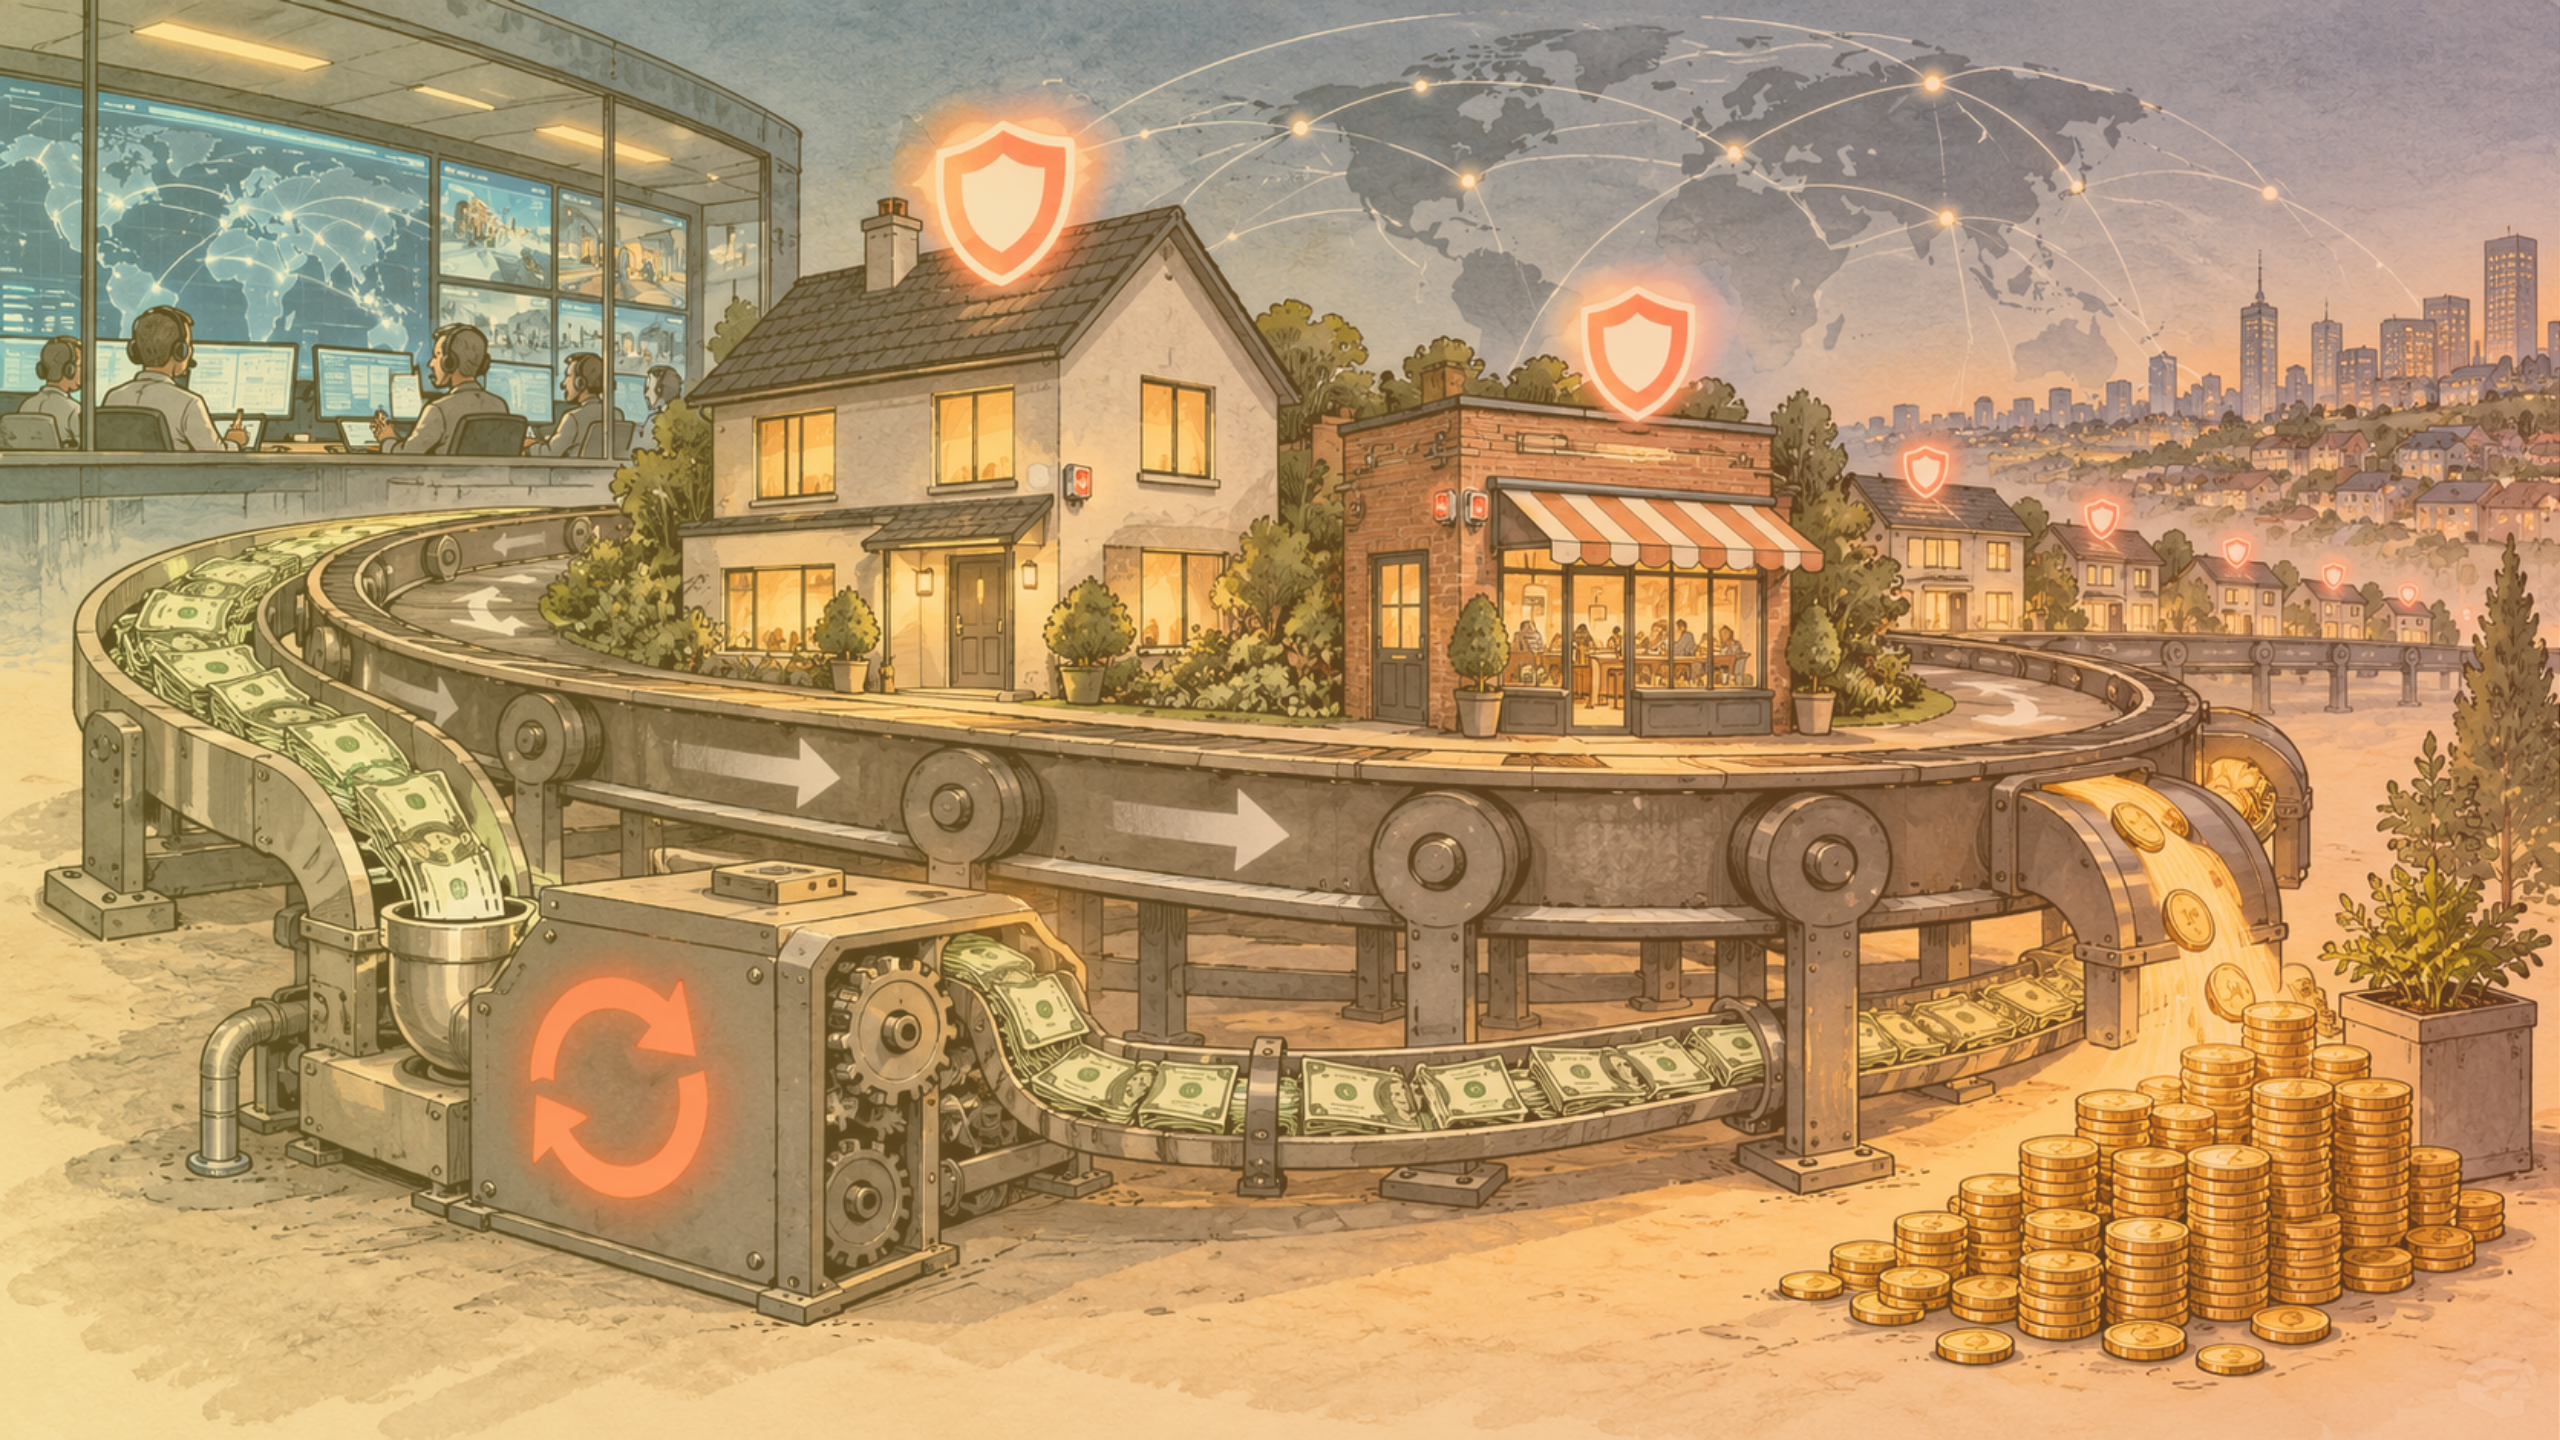
Verisure’s 6.38 million monitored-alarm subscribers generate 90% recurring revenue, while its disclosed acquisition costs and 6%-8% churn…
Everpure and DigitalOcean face rising expectations as their stock prices shape Monday’s views.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.