Expert Call | Corning
Corning’s NVIDIA-backed 10x fiber expansion, enterprise connector demand and carrier capacity plans frame its optical communications outlook through 2030.
Corning’s NVIDIA-backed 10x fiber expansion, enterprise connector demand and carrier capacity plans frame its optical communications outlook through 2030.
Seems like as good a week as any for $META to raise $50B or so in equity
@FedexSTi $NU back to the price it was three weeks ago.
@DavidWeinetayg @TidefallCapital Debt covenants matter. It won't however be the first or last company to buy itself back into ch11. I mean look at last quarter's buy backs in $FICO.
Looks like we got 13.5 million shares trading of $GME tonight. Not sure what’s going on. Besides the heavy insider buys. https://t.co/cU9aBeRwRR
$ONON so in vogue, it made it to the WSJ The Sneaker Taking Over America Was Inspired by iPhones and a Vacuum Cleaner https://t.co/rNjjRCEEnb
@At50w50882 @310Value @ctfn_news All of their existing debt is portable… this was by design and both mgmt / IR call this out regularly. Only need to raise the new debt….dovigi haters are always gonna hate. That’s why it needs to go private $GFL
AMD CEO Lisa Su says demand for AI inference and CPUs continues to rise as computing capacity becomes more valuable.
Verisure’s 6.38 million monitored-alarm subscribers generate 90% recurring revenue, while its disclosed acquisition costs and 6%-8% churn…
 Adam Schadt 4 clicks
Everpure and DigitalOcean face rising expectations as their stock prices shape Monday’s views.
Vicor uses ITC exclusion-order cases to license power-module patents, with published royalty multipliers rising from 1.0x before filing to…
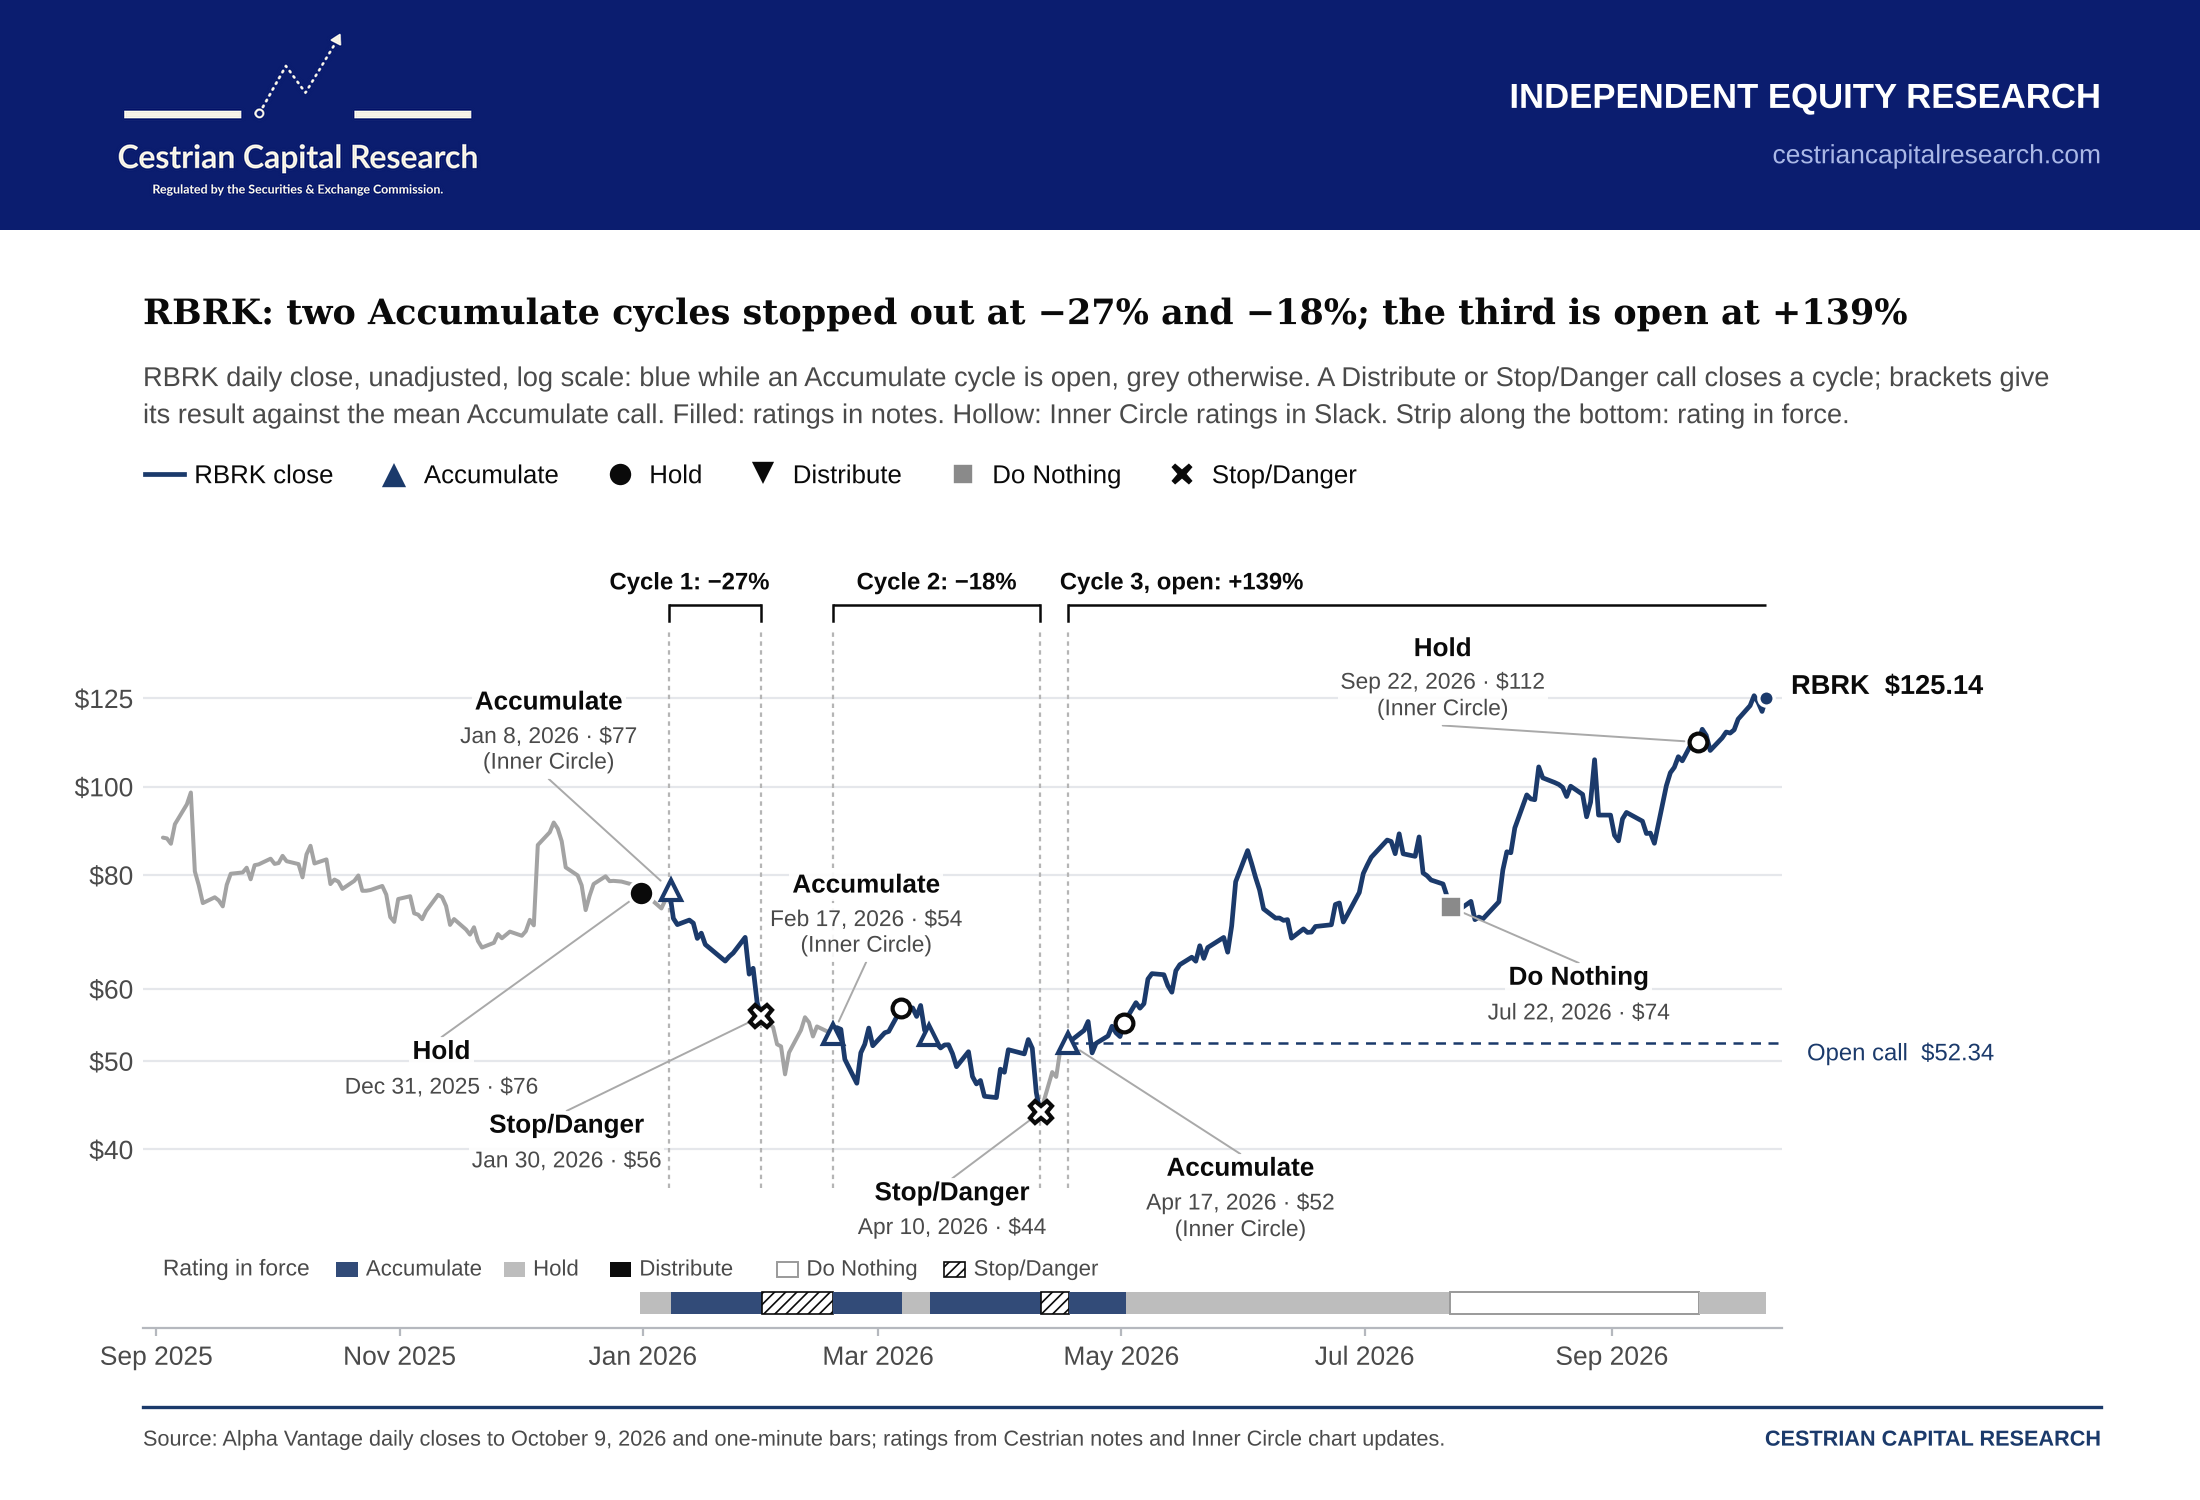
Rubrik posted 38% Q2 revenue growth to $427.3 million, but Cloud ARR growth slowed to 39% and its enterprise value reached 15.7 times…
Nebius’s 1 GW annual active-capacity target from 2027 is realistic, according to a former product manager, with greenfield data centers…

Charles Lemonides argues the 18-year bull market has not reached its late-stage liftoff, pairing value-oriented semiconductor longs with…
Dell booked $131.7B of AI server orders in four quarters and held a $95B backlog as enterprise AI demand accelerates.
Meta’s Muse automated website fixes and design changes for a solo publisher, illustrating how $20-per-month AI agents can reduce…
 AMADF · long
Amadeus IT Group turns long after shares fell more than 20% since a November short call.
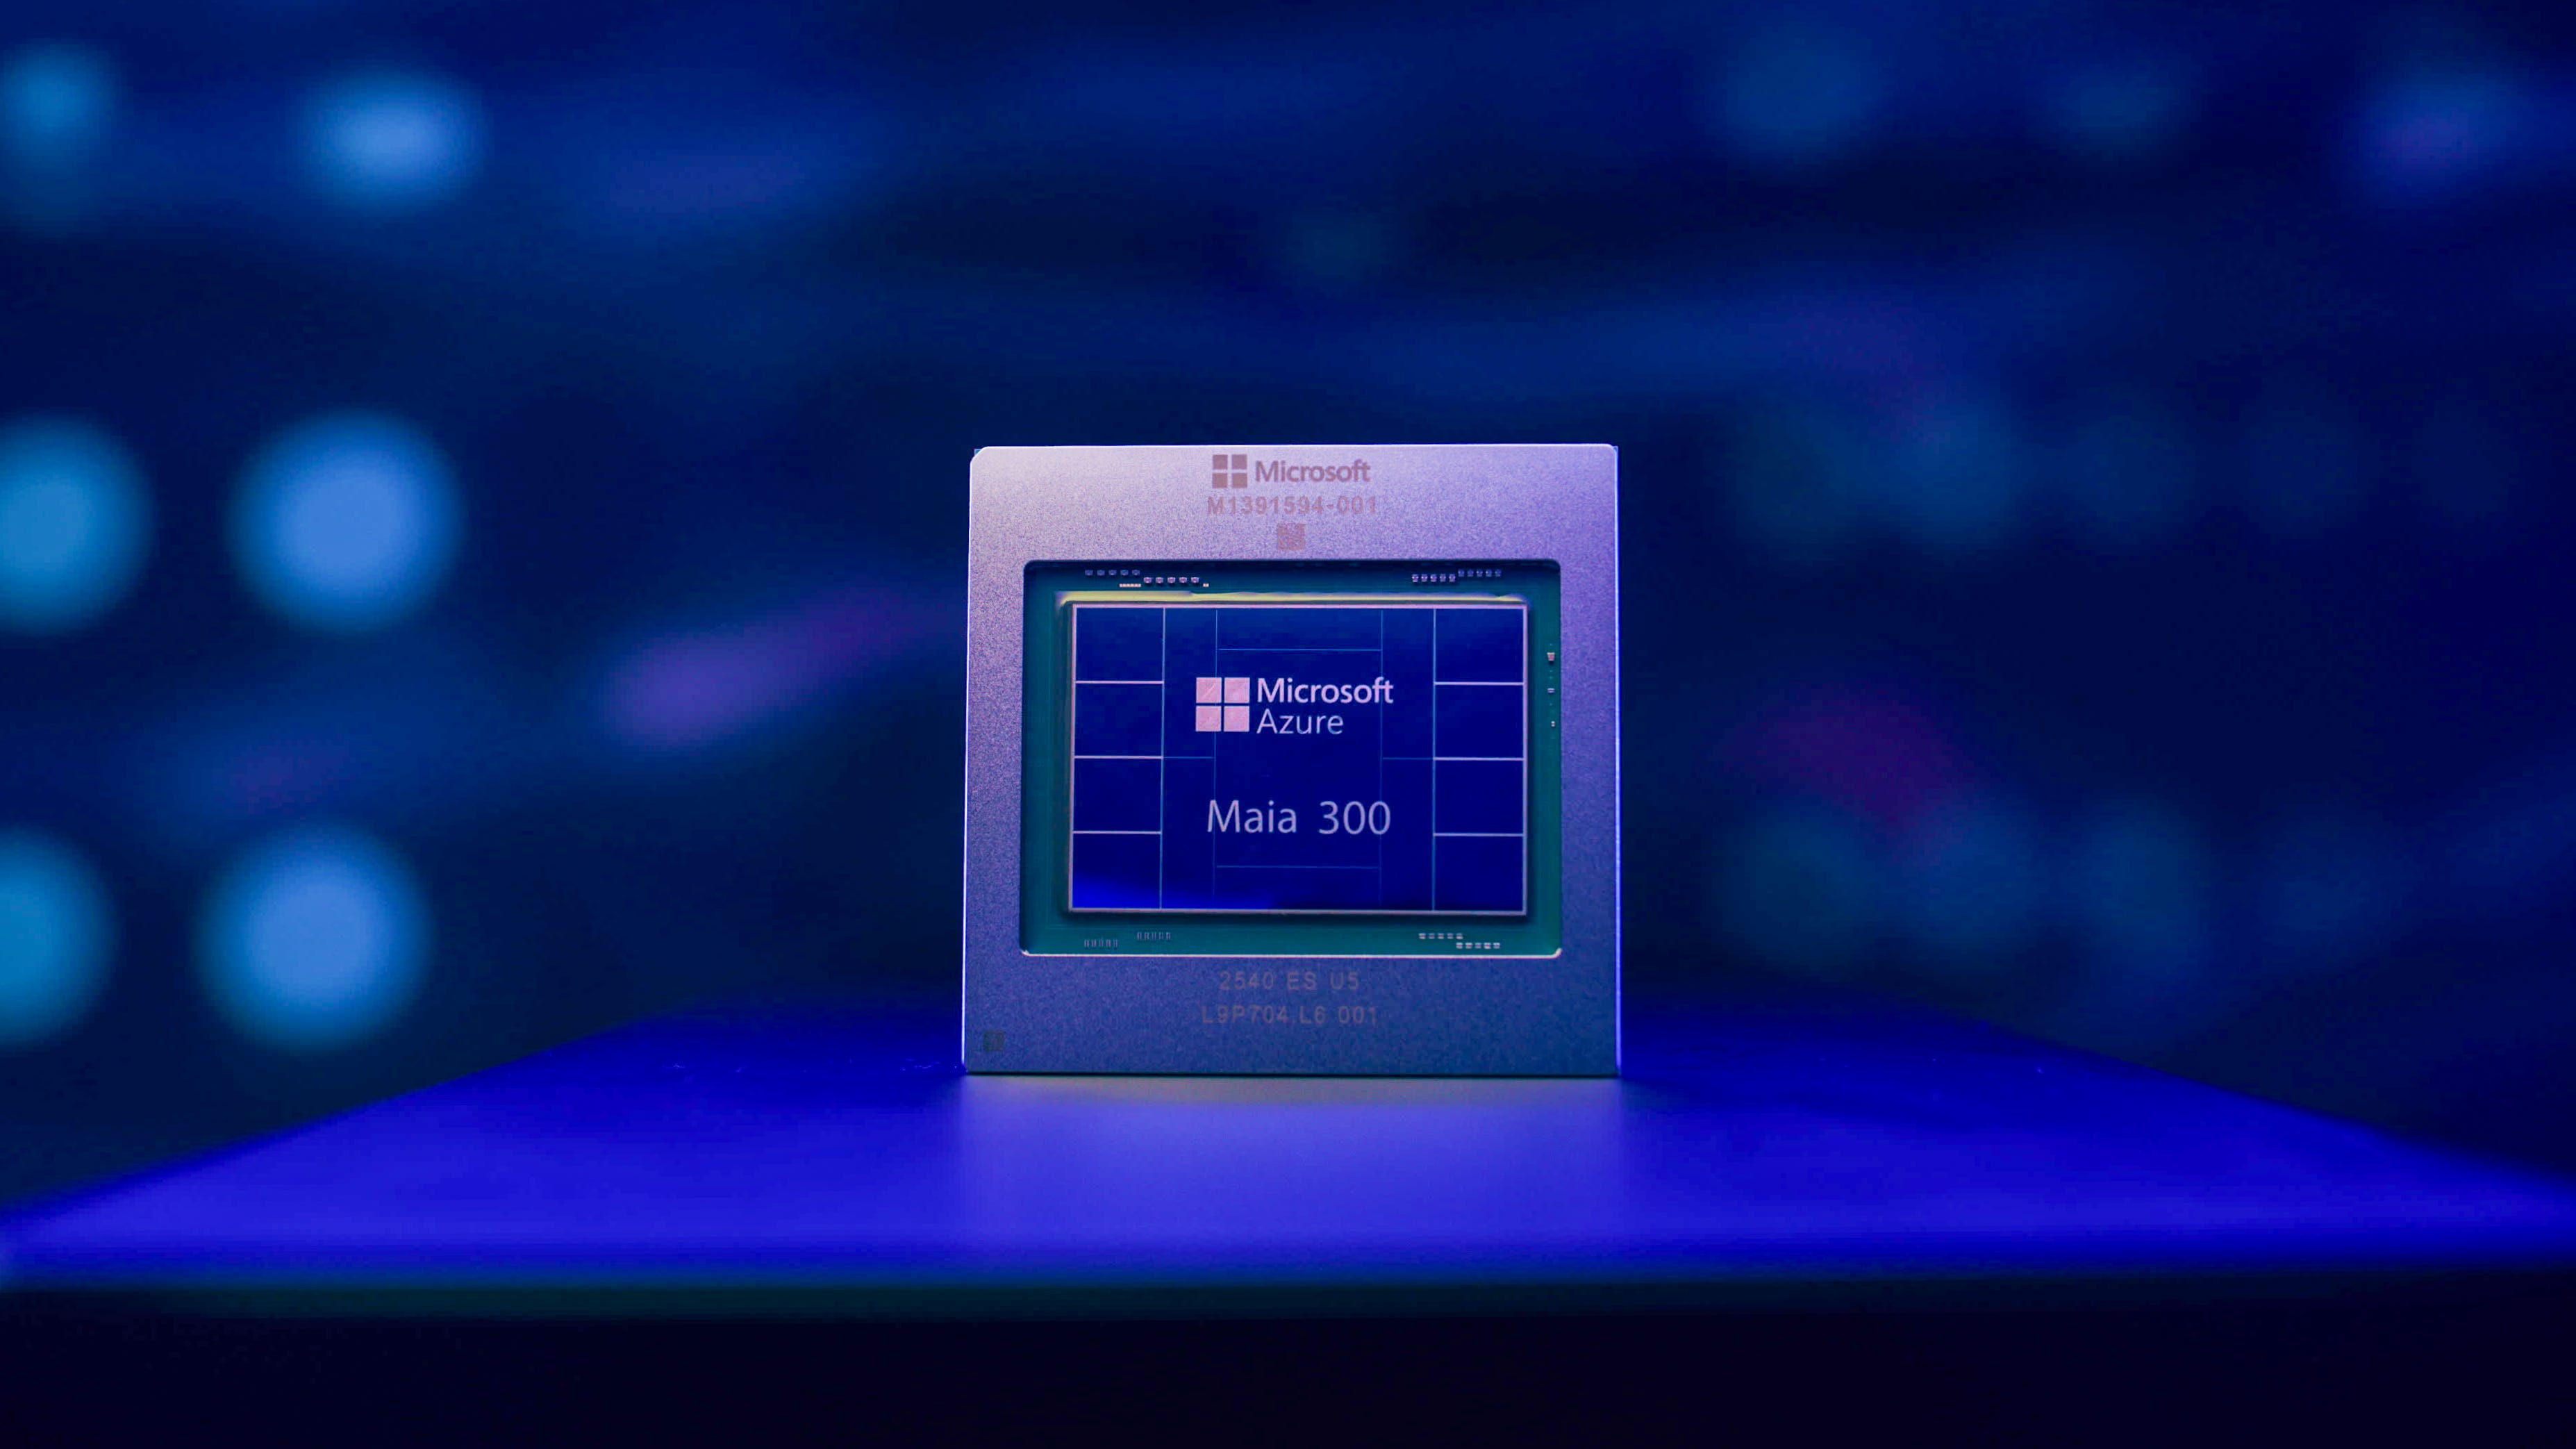
Microsoft plans multi-gigawatt Azure Maia 300 deployments starting next year, targeting 40% more tokens per megawatt than leading GPU…
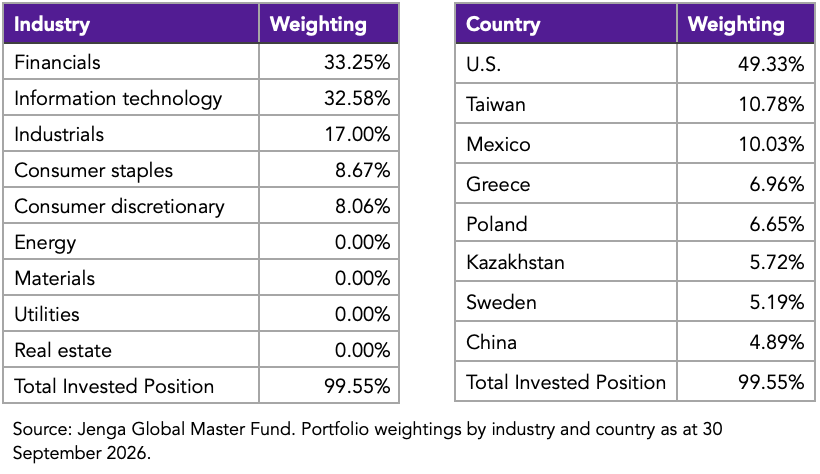
Jenga Global Master Fund returned 8.10% in Q3 2026, added Adobe and Mexican airports, and later initiated S&P Global.
Howmet Aerospace posted 24% Q2 revenue growth and 46% adjusted EPS growth, but HWM trades about 87% above a $120.69 DCF fair-value estimate.
 Alexander I. Velasquez 2 clicks
Liquidia’s Yutrepia sales reached $170.4 million in Q2 2026, while a patent ruling threatens its PH-ILD label but leaves PAH sales and a…
Magna International’s gross margin reached 14.7% and operating margin 5.6%, supporting double-digit earnings growth alongside EV investment…
 David Zanoni 1 click
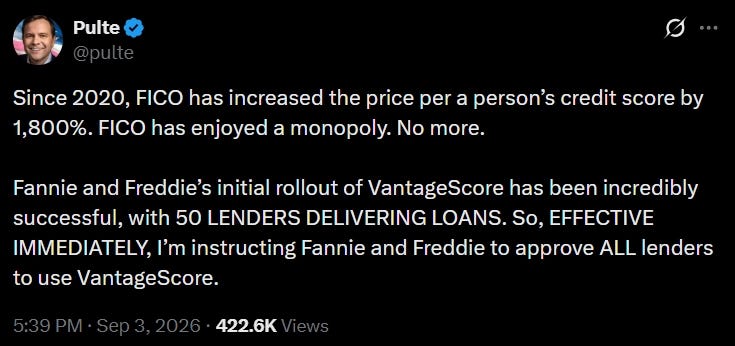
FICO’s mortgage credit-score monopoly sits at the center of a GSE-dominated U.S.
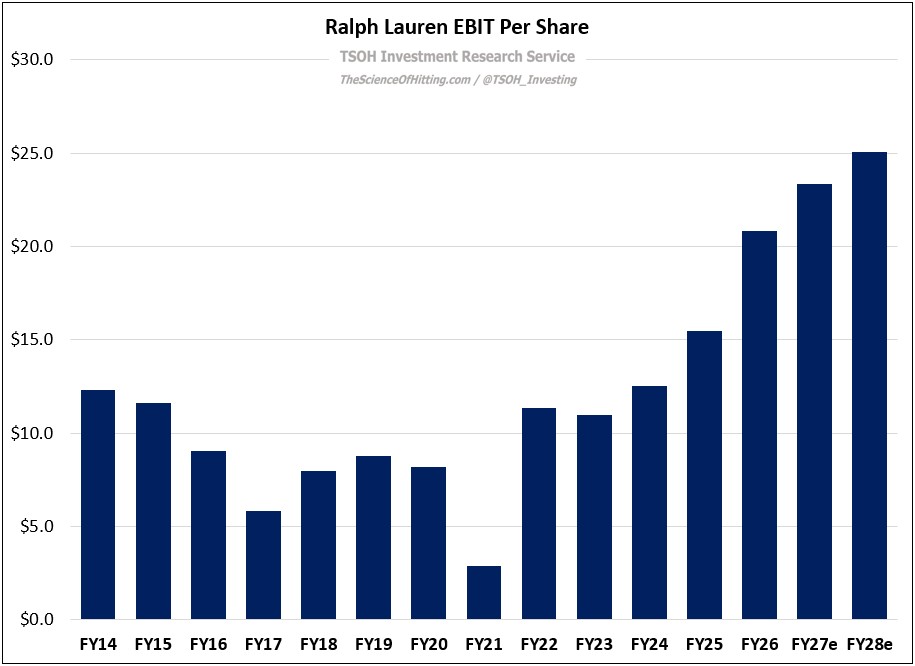
Ralph Lauren’s 2017 CEO change put Patrice Louvet in charge of reversing nine quarters of same-store sales declines and restoring the…
Marvell’s Q2 revenue rose 37% to $2.74 billion, with data centers contributing 79%, while FY1/27 guidance targets roughly $12 billion in…
Dassault Aviation leads a 53-pitch roundup with a €45 billion order book against €7.4 billion of sales and a 26.6% Thales stake.
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.