Advanced Micro Devices (NASDAQ: AMD) Stock Rating: Hold Into Q3 FY12/26 Earnings
AMD is rated Hold ahead of Q3 FY2026 earnings after Q2 revenue rose 50% to $11.5 billion, led by 107% Data Center growth.
AMD is rated Hold ahead of Q3 FY2026 earnings after Q2 revenue rose 50% to $11.5 billion, led by 107% Data Center growth.
GameStop $GME is doing the classic “pitch a tent” chart https://t.co/V41u9jWU8r
If I wanted to buy a traditional telco like $VZ $T or $TMUS I'd probably post something like this to crush terminal value for a year or 2 then move in https://t.co/lxEl3f1IBL https://t.co/HEYcNFl7Uq
Isn’t this super bullish $CRDO because it means $LITE can’t supply a lot of the demand with optical, thus AECs likely see a larger demand in cases where they work? https://t.co/9gR7NQ2erE
Continue reading here for why lower HPDU costs mean less revenue but more profit for $BWXT: https://t.co/bPIYua98gd
I think $SFM trades at 11x earnings (a discount to $KR mind you) solely because Michael Burry had to buy the stock. Dude curses anything he touches Technicals look awful but it's still a great cheap growing business buying back a lot of shares. I think if you buy here and look away for a year or two it does very well, even if Burry stays long (broken clock)
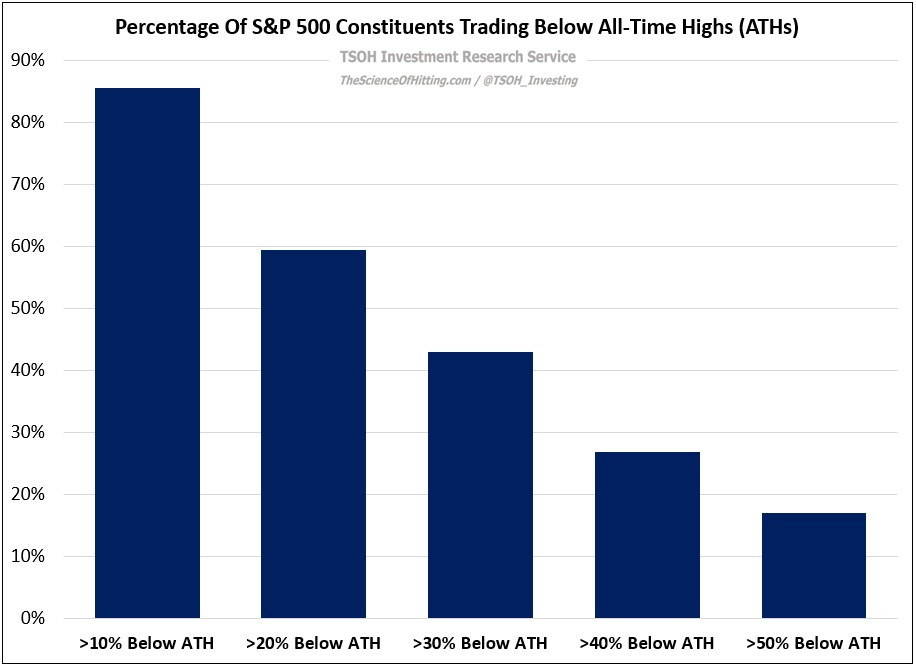
Paramount Skydance’s debt-heavy Warner Bros. Discovery acquisition, streaming bundle pricing and alcohol-industry diversification anchor…
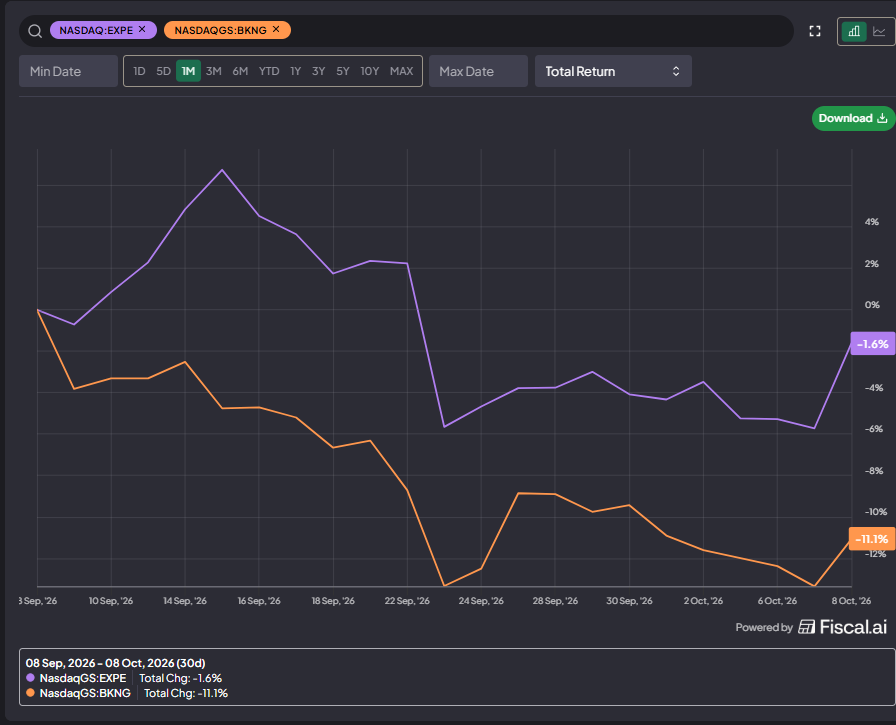
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
Alphabet pairs 17% Search growth, 82% Cloud growth and 500,000 weekly Waymo rides with a $195–205 billion AI capex plan.
AppLovin's Ads Manager targets middle-market e-commerce advertisers as Q3 guidance calls for 47% sales growth, while legal and compute-cost…
 Jack Elias 3 clicks
Mohnish Pabrai’s 69 quarterly filings are rebuilt into a never-sell portfolio, including Horsehead, Berkshire, Alphabet, Ferrari and…
Robinhood’s AI agents, 24/7 equity trading and 10:1 crypto perpetual futures encourage higher retail trading velocity, leverage and…
Lowe’s trades at 15x earnings after a 23% decline, with weak housing and high rates pressuring growth while inventory discipline supports…
 Seeking Profits
Yellow Cake and Cameco say U.S. utilities have contracted only 40% of 2030 uranium needs, setting up a new contracting cycle as…
Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Stacy Rasgon says AI chip demand is constrained by land, power and clean rooms, lifting memory, optics and wafer-fab equipment spending…
Nike's 4.8% dividend yield masks payout ratios above 100% of forward EPS and inadequate free cash flow coverage, while China sales declines…
 Sensor Unlimited
Geoffrey Williams explains CMBS underwriting, post-GFC securitized-credit risk transfer and why credit markets reprice in step functions.

Intuitive Surgical, down 32% from its January 2025 peak, faces slower US procedure growth and new robotic-surgery rivals despite $10.1…
Credo expects optical revenue to reach $600 million in FY27 after Q1 revenue grew 114.7% year over year, expanding from AEC cables into AI…
 Analysis Fundamental 4 clicks
Meta’s Reality Labs shifted spending toward smart glasses, accepting roughly $40 per-unit losses to build an eventual advertising platform…
Vertiv's 33% stock decline followed a 2026 forecast increase, despite a $15 billion backlog and rising AI data-center demand for power and…
Undercovered Dozen spotlights 12 lesser-covered stocks, including Brookfield Renewable, Annaly Capital and Seagate.
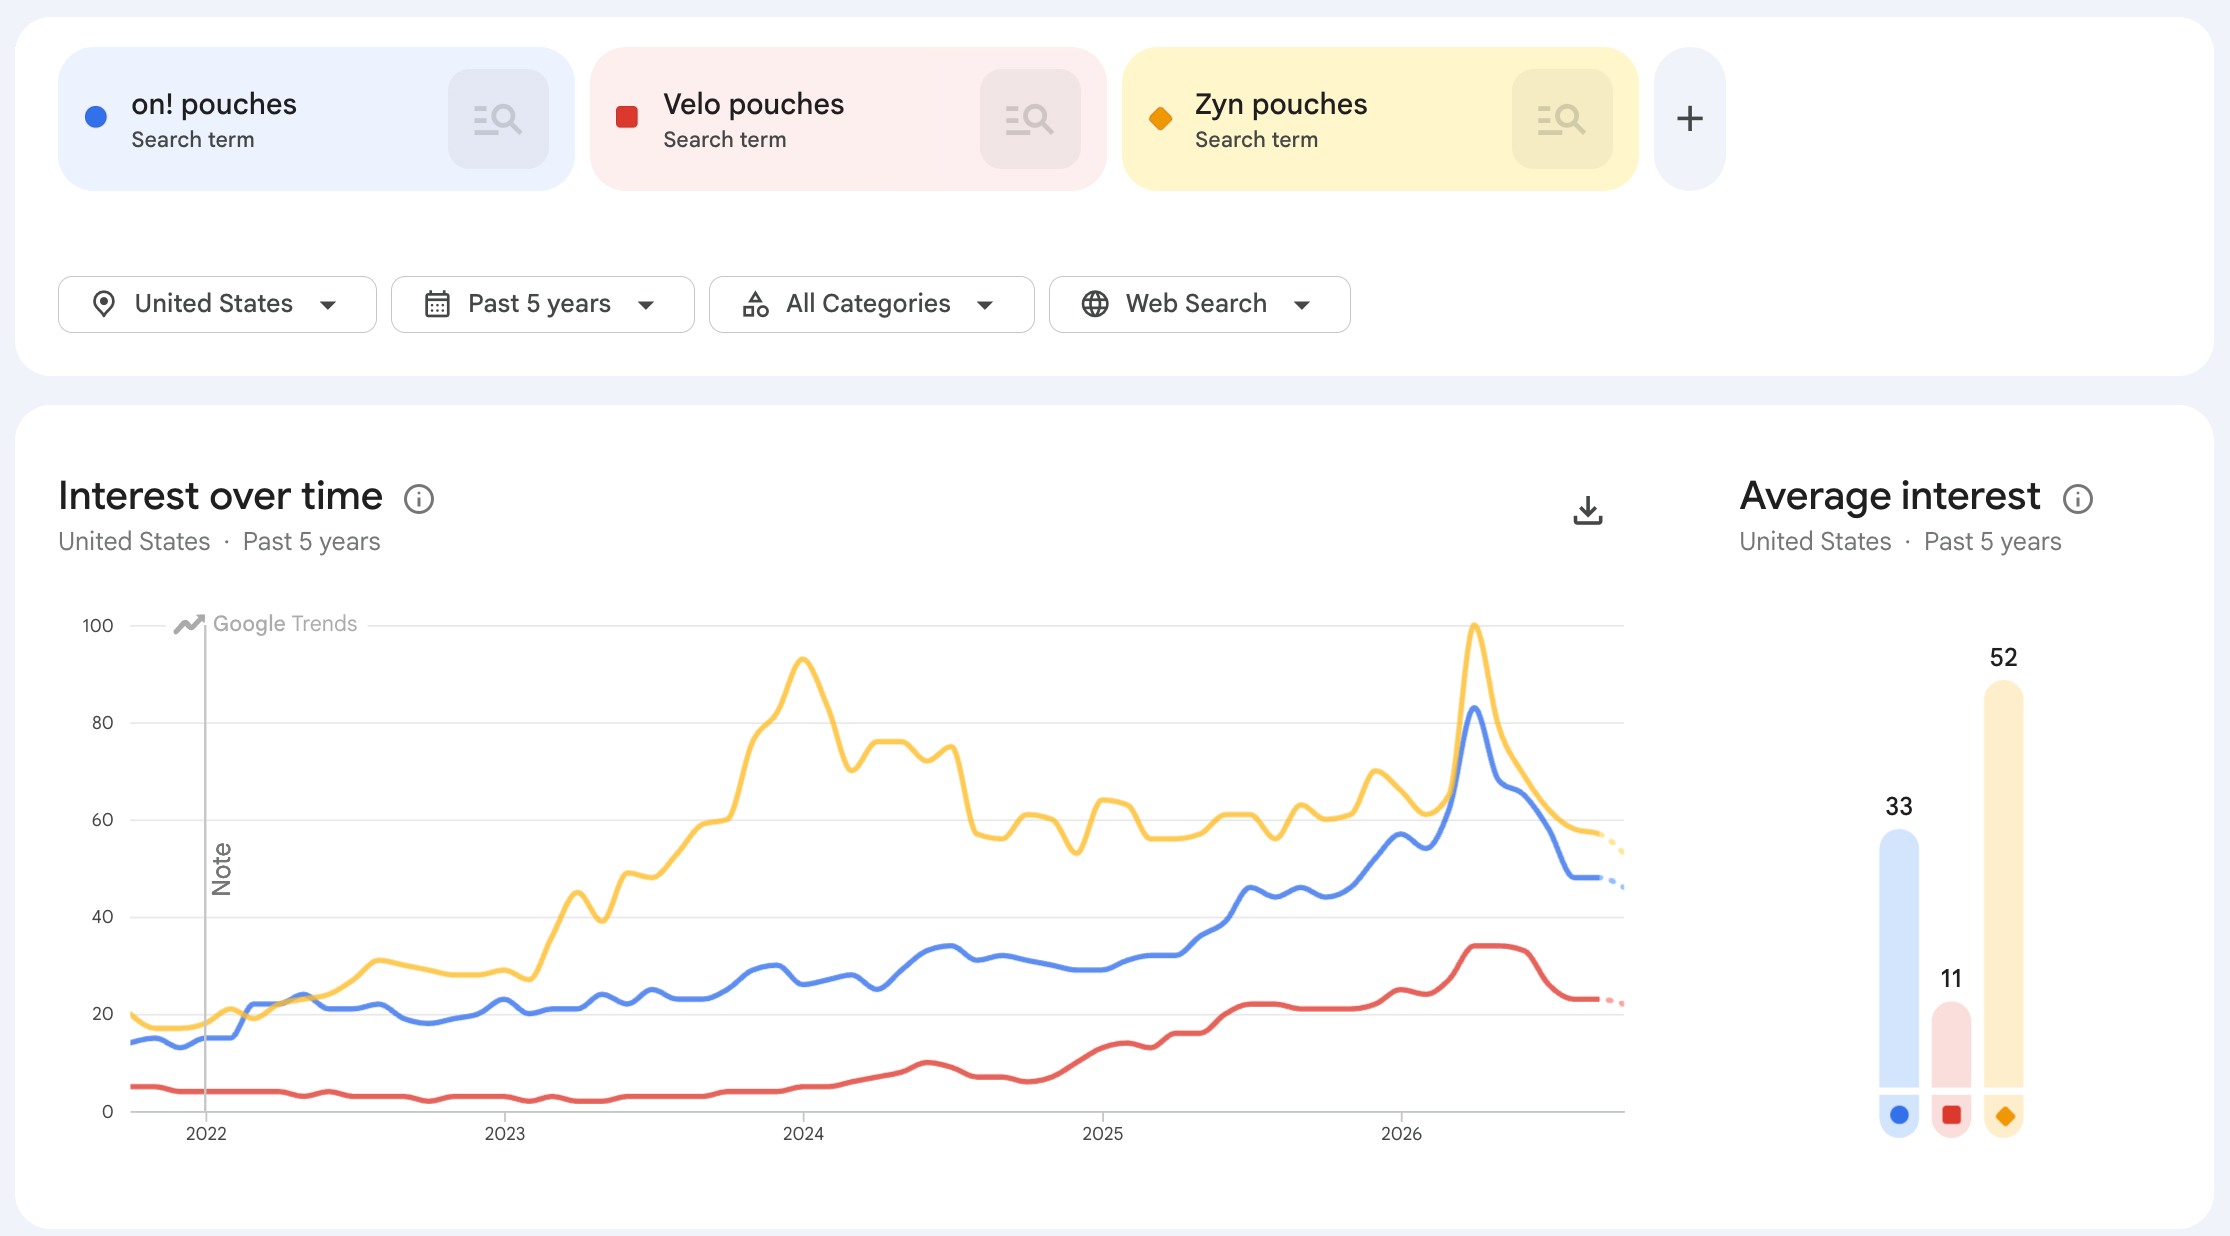
Nicotine pouches show low brand loyalty and sharply varied preferences, with U.S.
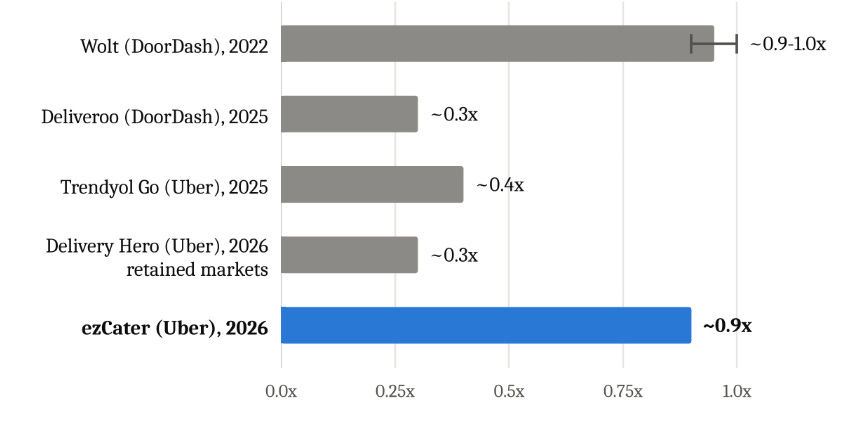
Uber’s $2.3 billion cash purchase of ezCater extends its buy-versus-build strategy and raises questions about the price and capital…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.