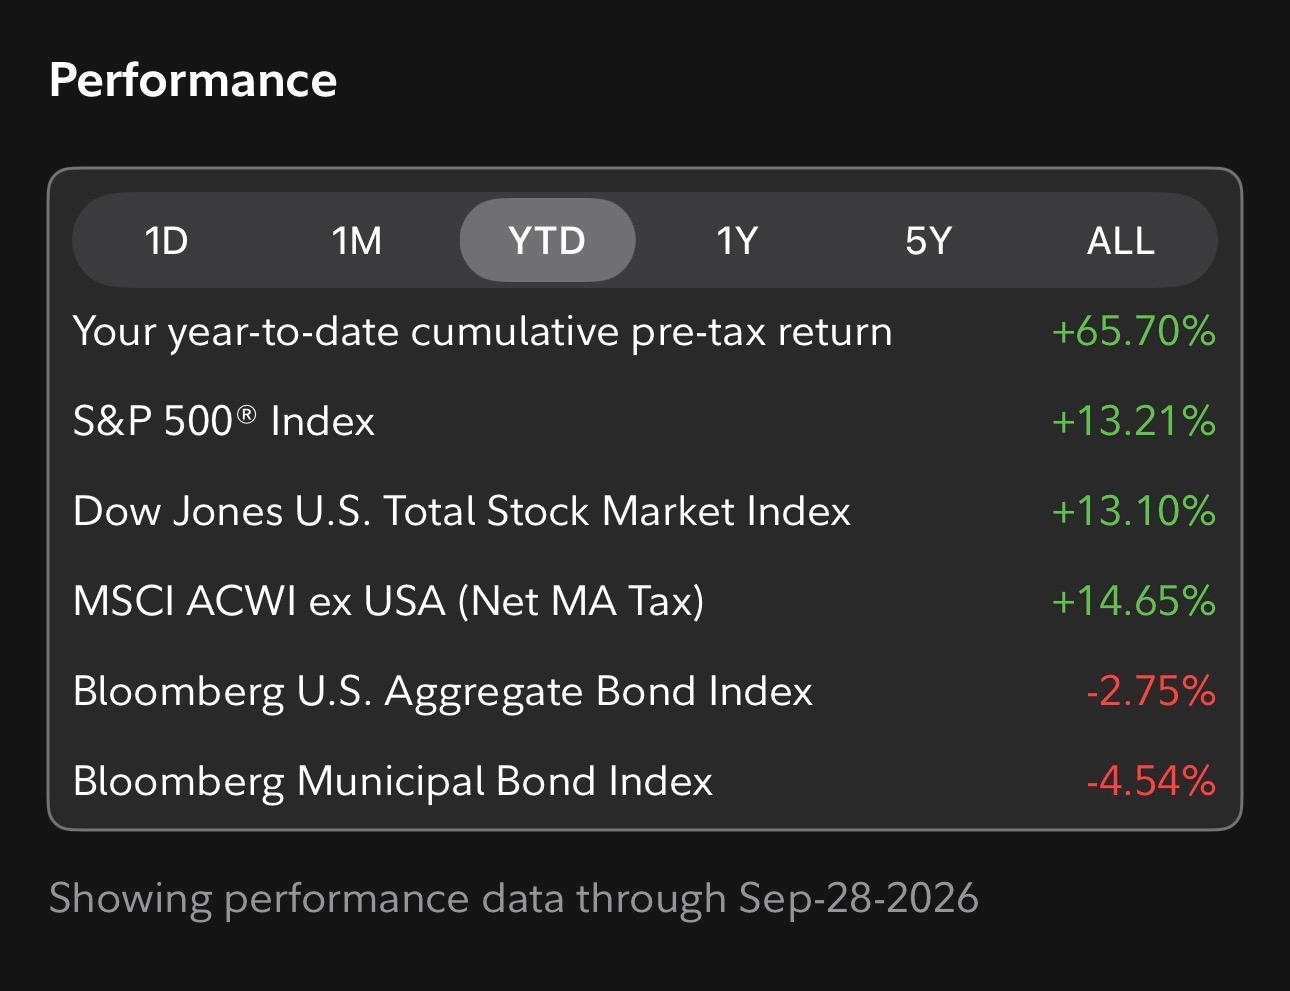
Portfolio returned 65.7% through September 28 versus the S&P 500’s 13.2%, while backing Tourmaline, EQT, Athabasca and SLB on gas demand…
S Guardian Research 5 clicks
FTAI Aviation’s engine-exchange model swaps CFM56 engines in days rather than 200-day overhauls, driving Aerospace Products adjusted EBITDA…
S Bristlemoon Capital 2 clicks
Archer Aviation's Insitu, Wisk and SkyGrid acquisitions add military and drone revenue, cutting FAA-certification dependence and leaving…
SA  The Alpha Analyst 2 clicks
Cisco’s Sam Badri says roughly 90% of AI users remain at basic prompting, with few advancing to skills files or AI agents.
YT Steve Eisman 5 clicks

Zscaler posted 25% Q4 revenue growth to $898.2 million and a 24.3% operating margin, but guided FY27 growth down to 16.6%-17.5% as free…
BL Cestrian Capital Research 3 clicks
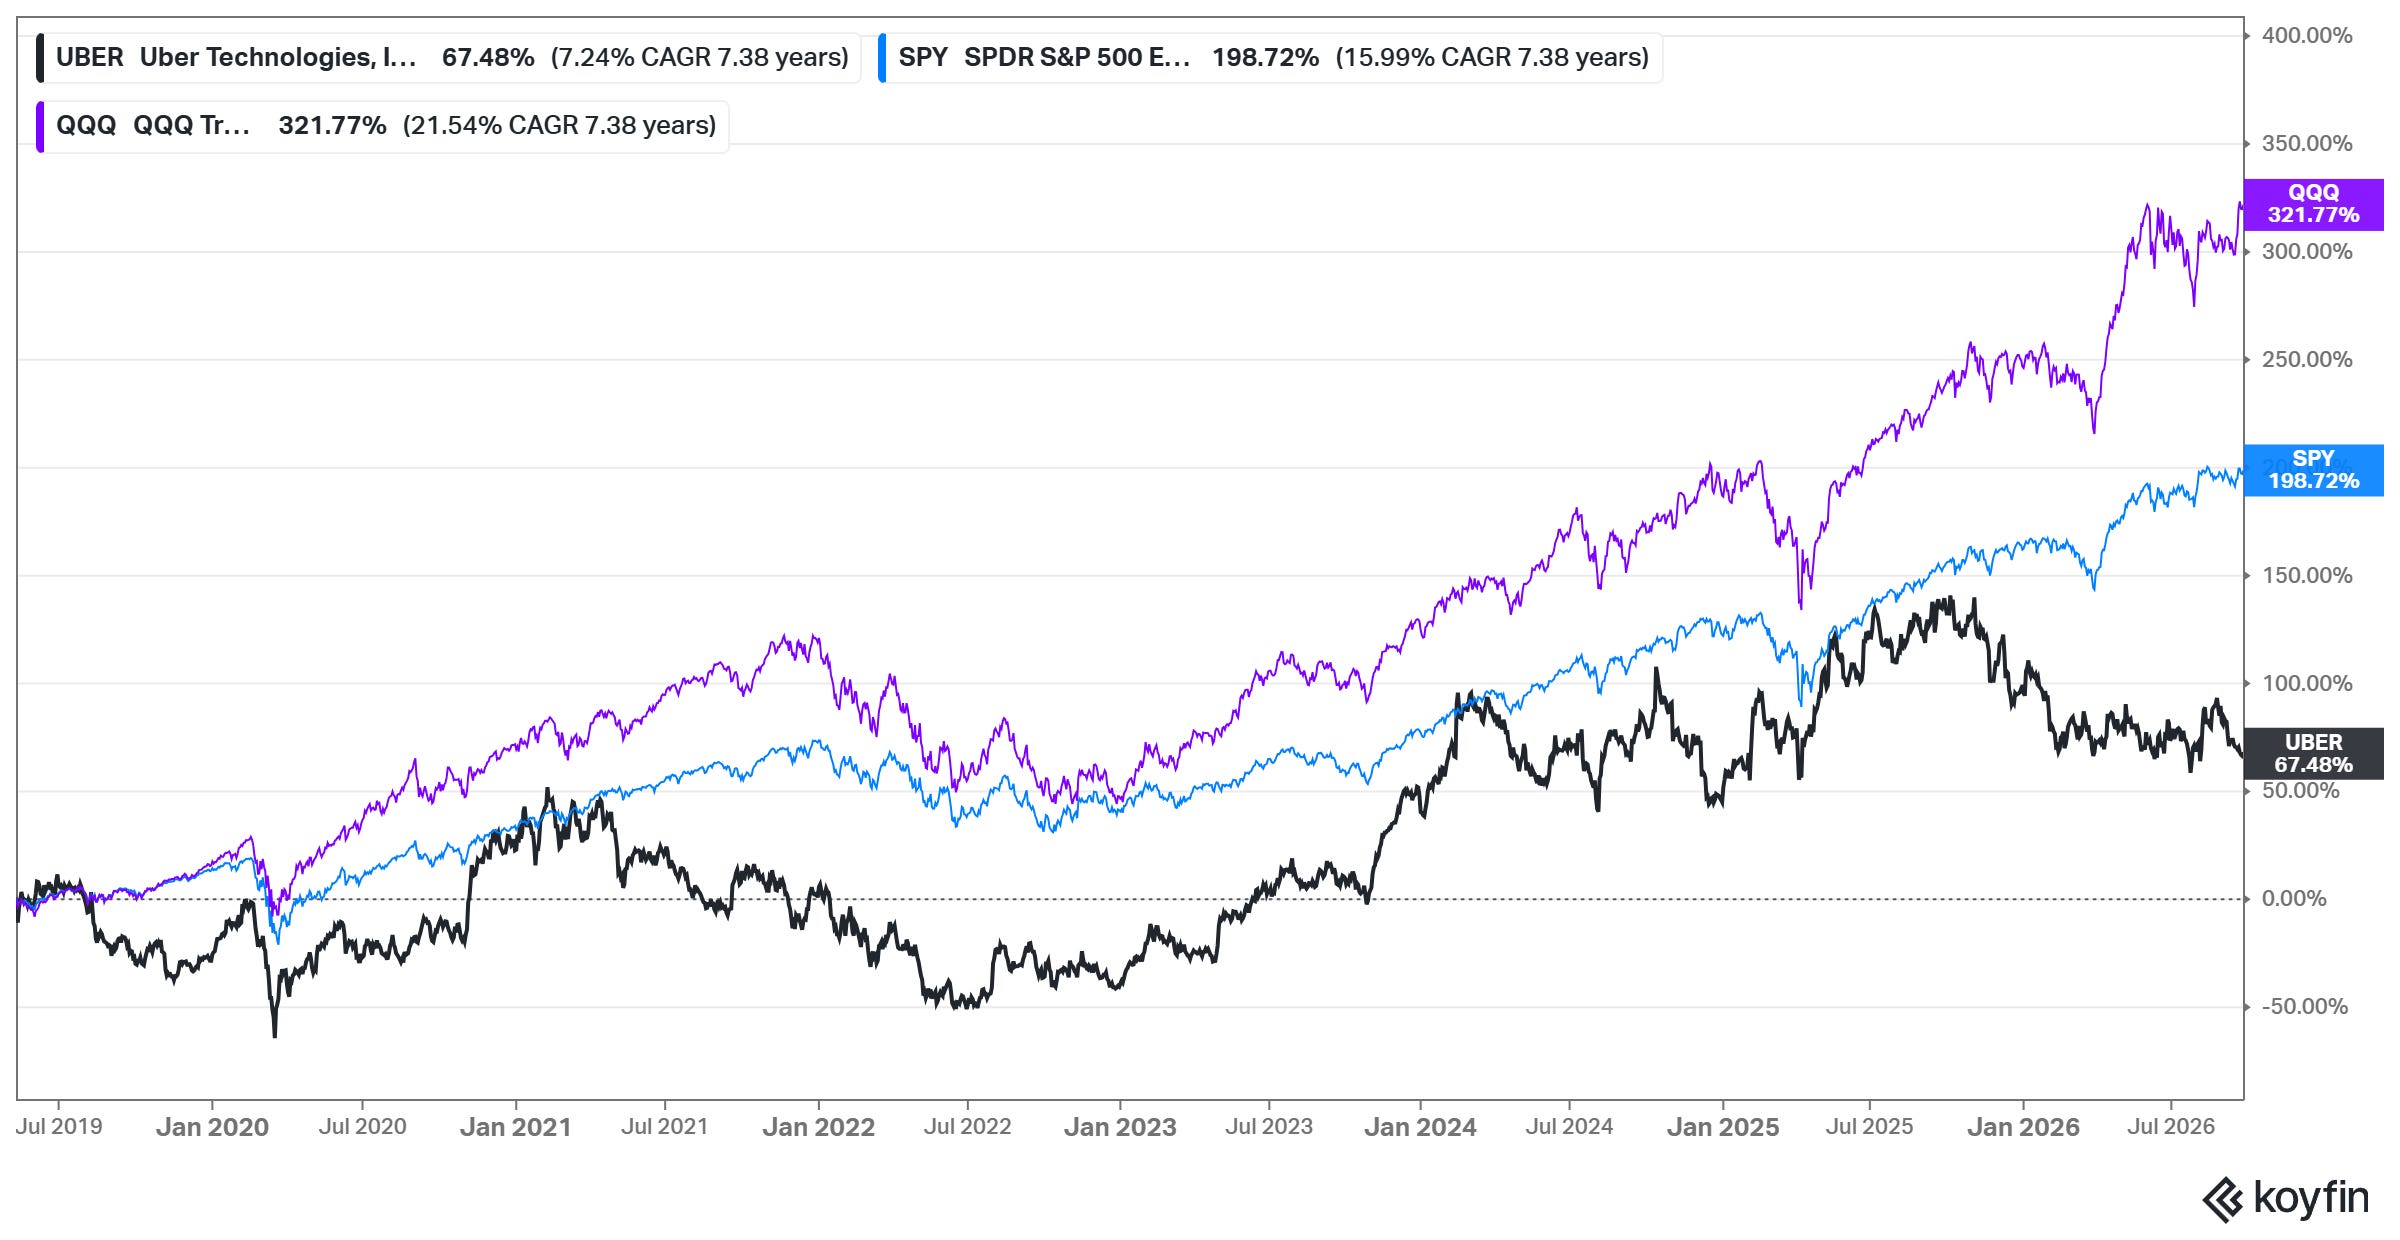
Uber's $193 billion in gross bookings and $10 billion in free cash flow contrast with modest stock gains as autonomous vehicles and…
S MBI Deep Dives 2 clicks
RTX’s $289 billion backlog and margin gains at Raytheon and Collins support its 2026 sales target of $95–96 billion, while Pratt & Whitney…
SA  Vishal Jadaun 3 clicks
Micron and Nike earnings headline a weekly briefing featuring Exor’s NAV discount, Meta’s Muse agent and Bellway’s UK housing valuation.
S Latticework by MOI Global 3 clicks
Hindsight Capital tests crisis-era investment decisions using anonymized company financials, including TransDigm, Halma and Texas Pacific…
S Rebound Capital 6 clicks
Brookfield’s BN, BAM, BIP, BEP and BBUC span asset management, infrastructure, renewables and private equity, with BN valued at a 15–20%…
SA  Brad Thomas

Veeva Systems moved VEEV to Distribute at $277 after a 41% gain in less than two months, despite Q2 revenue growth of 18% and 45% EBITDA…
BL Cestrian Capital Research 4 clicks
 CBOE · long
Cboe Global Markets trades near $232, with a roughly $24.3 billion market cap, net cash and a 16-17x forward P/E.
BL Value Investors Club 3 clicks
Mastercard’s VASS segment reached roughly 40% of net revenue and grew 20%, while AI, digital-wallet and stablecoin partnerships expand its…
SA  IWA Research
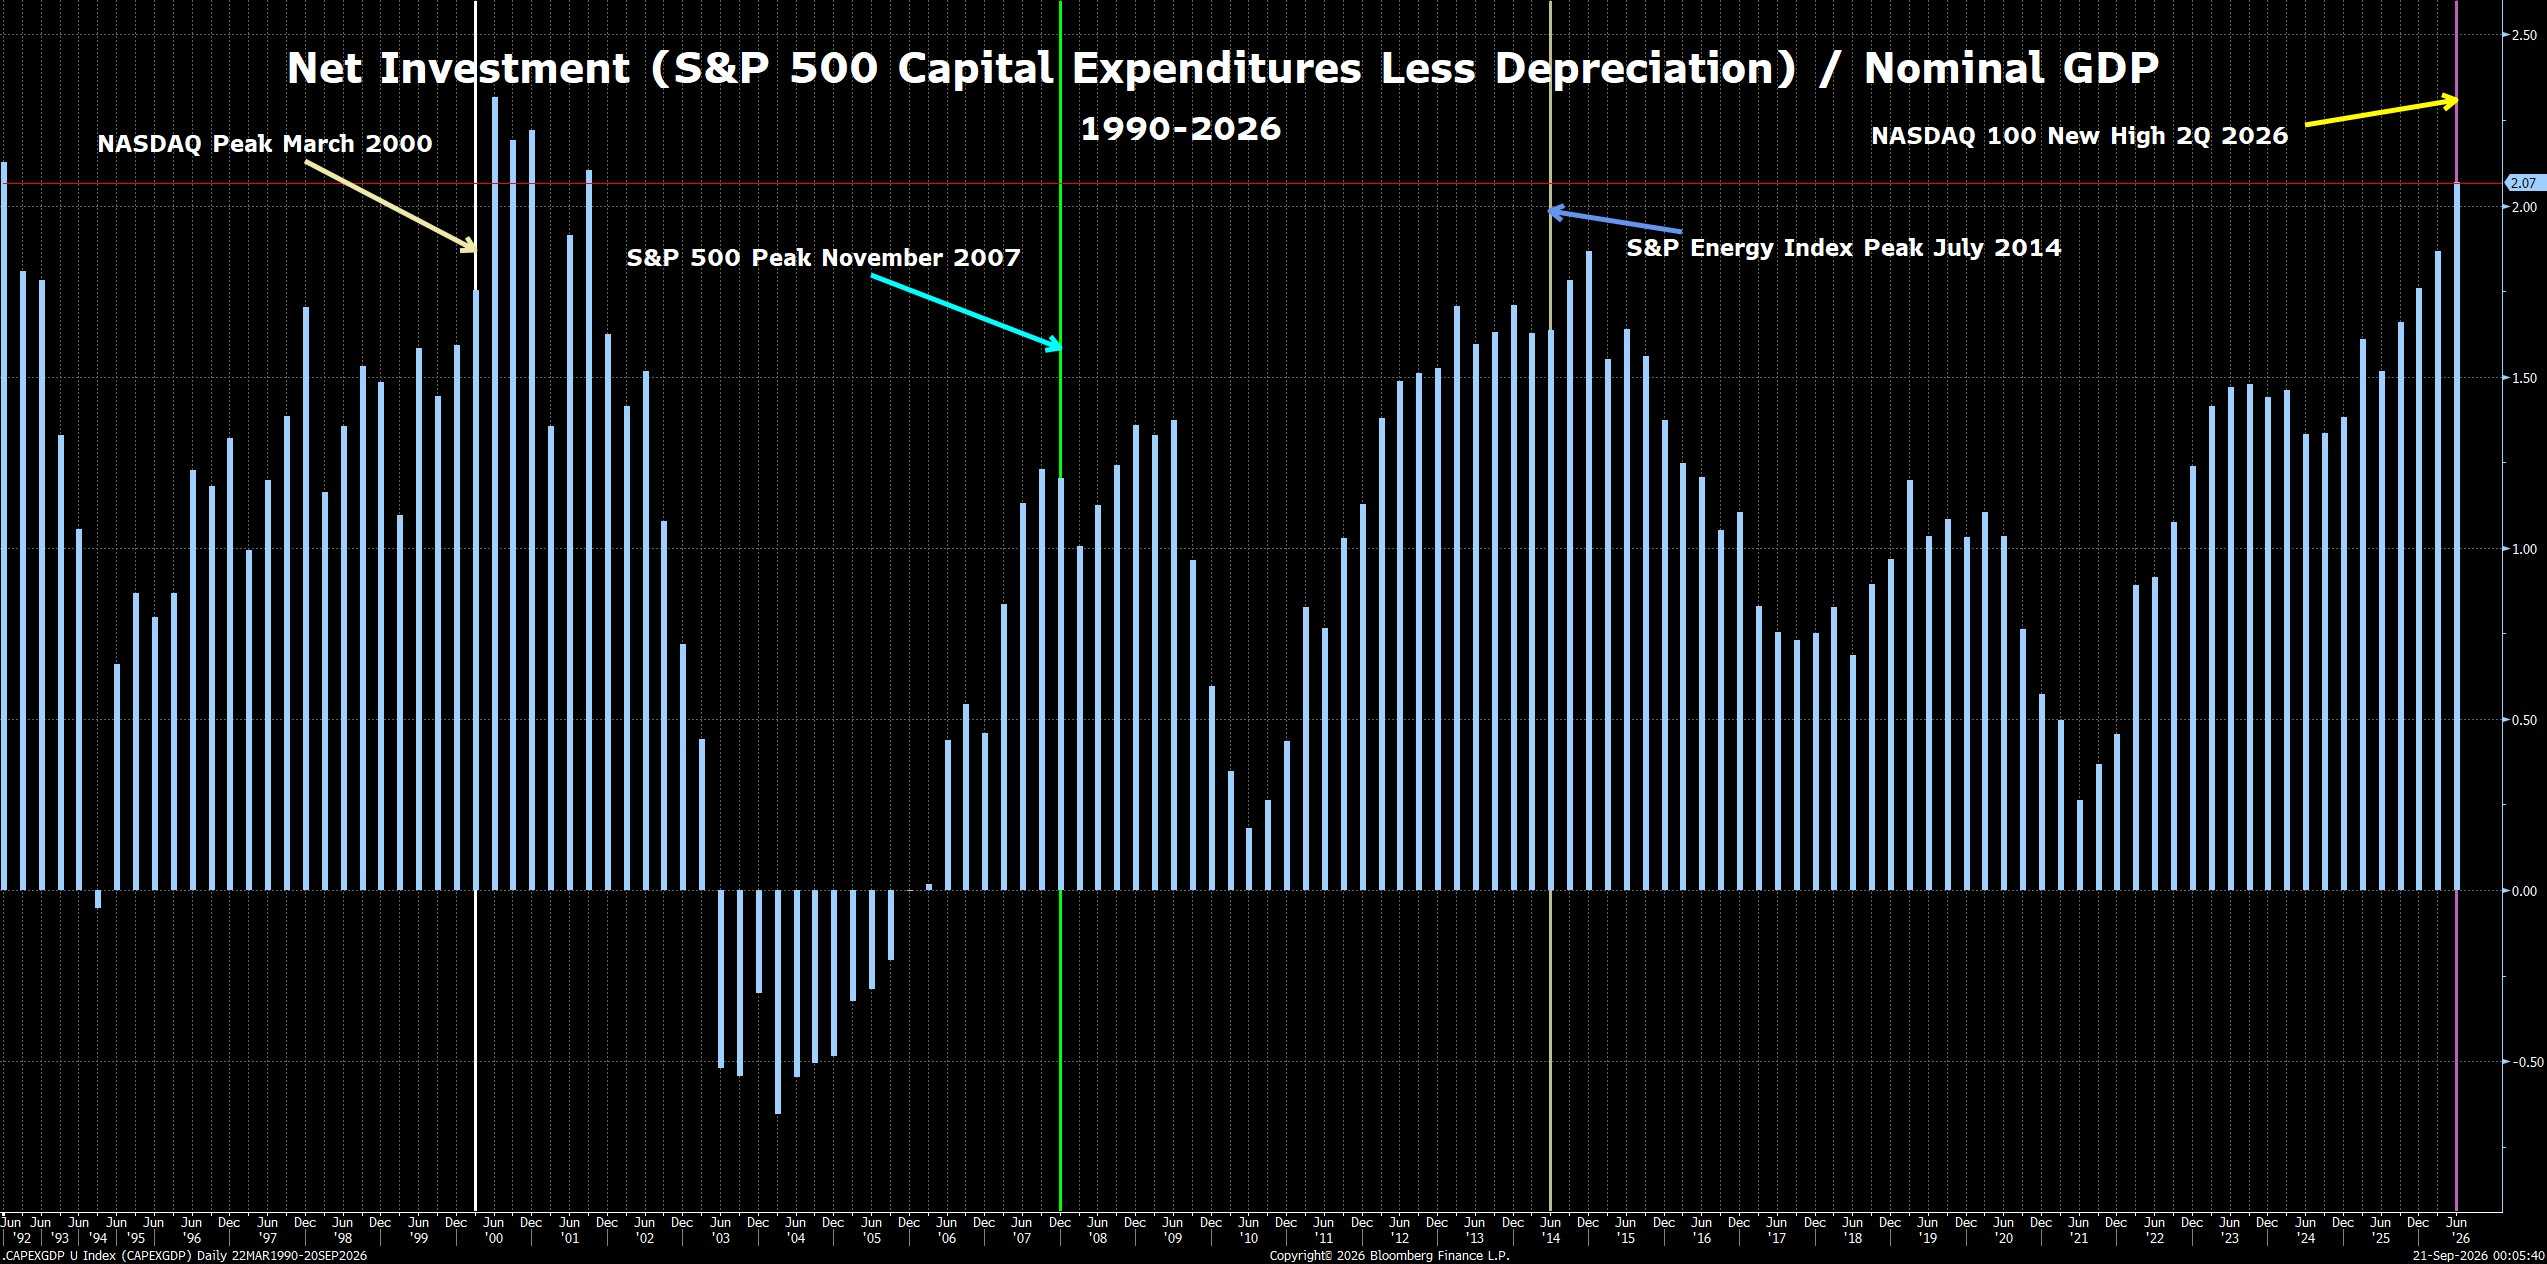
Microsoft, Amazon, Oracle, Meta and Alphabet face another two years of record AI data-center investment amid $3 trillion in commitments,…
S Cassandra Unchained 9 clicks
Intuit trades at historically low multiples as DIY tax pricing pressure and customer losses test its growth, while assisted tax, Money and…
SA  Daniel Schönberger 2 clicks
Honeywell Aerospace, newly spun off as HONA, fell 41% from post-listing highs after Q2 2026 as supply-chain bottlenecks delayed revenue…
S D Invests 13 clicks
Steve Eisman says AI companies are reviving Enron-era off-balance-sheet and circular financing, alongside concerns around Oracle and Blue…
YT Steve Eisman 5 clicks
Reddit’s DCF values shares at $225, driven by international ARPU expansion from $2.2 to $8.3 by 2035 and 38% operating margins.
S Hated Moats 7 clicks
Energy Transfer's volume growth and data center demand support EBITDA above guidance, potential Q3 upgrades and distribution growth.
SA  White Star Research 2 clicks
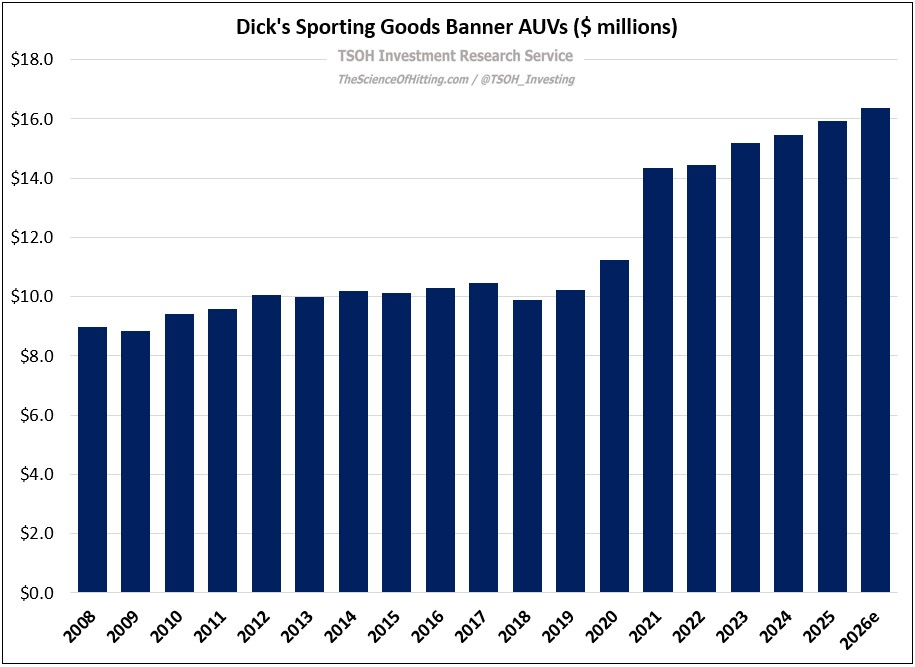
TSOH Weekly Roundup covers Ralph Lauren’s $1 billion distribution pullback, Peloton’s $2,195 foldable treadmill and $800 million…
S TSOH Investment Research 5 clicks