GameStop Is Extreme Deep Value
GameStop's collectibles mix rose to 45% of sales as gross margin reached 44%, supporting a deep-value case built on cash and store economics.
GameStop's collectibles mix rose to 45% of sales as gross margin reached 44%, supporting a deep-value case built on cash and store economics.

If you liked $FTAI at $209, you’re going to love it $186…

$ACMR

@SovietInvestor ok well $RYN sells for $1,800 per acre...
CoStar spent more than $1 billion building Homes.com to challenge Zillow, betting seller-agent leads, proprietary listing content and…
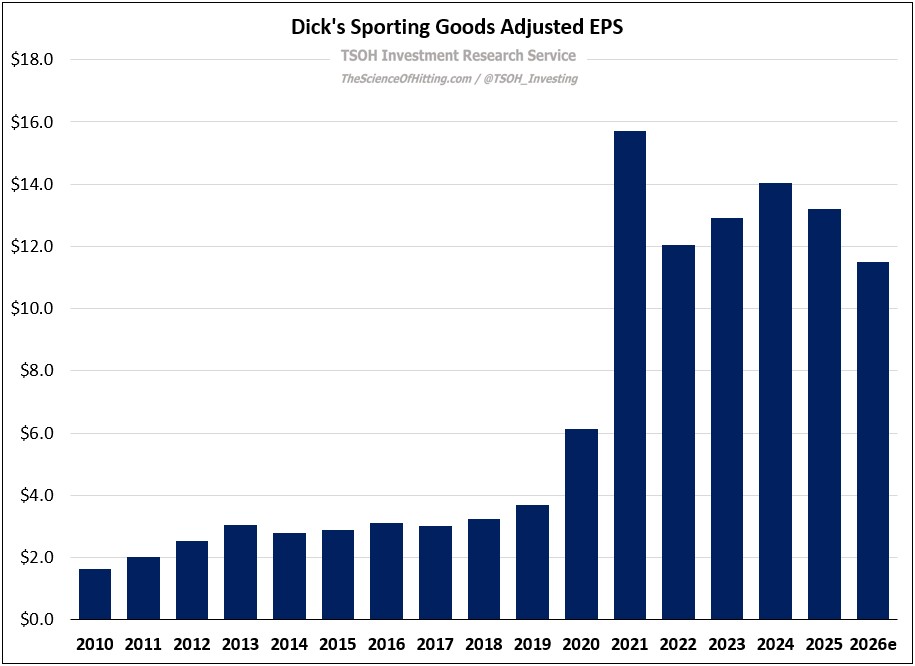
Dick’s Sporting Goods’ $2.4 billion Foot Locker acquisition nearly quadruples its store count and adds international exposure, risking a…
Goldman Sachs posted $20.98 in Q2 EPS on $20.3 billion of revenue and raised its dividend to $5 per share, with M&A and issuance activity…
 Mike Zaccardi, CFA, CMT 2 clicks
Latticework’s weekly briefing spotlights discounted European assets including Barco, Bolloré, Brookfield and D’Ieteren, with catalysts…
Genuine Parts targets NAPA network improvements, Motion’s industrial recovery and a 2027 Automotive-Industrial separation to lift sales,…
 Value Capital Research 2 clicks
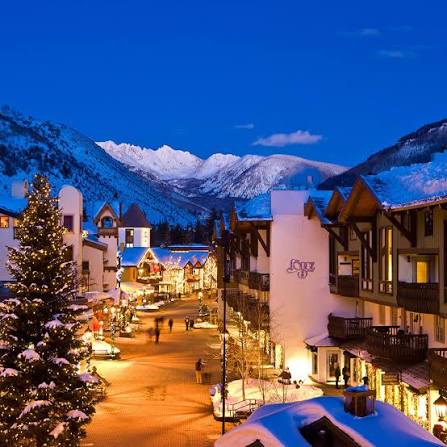
Vail Resorts, down 60% since 2022, is pitched for an El Niño-driven ski-season rebound; the portfolio also buys ORR and shorts GEO.
Brookfield Corporation, down 20% YTD, manages $1.27 trillion across asset management, insurance and operating businesses as rates, debt and…
Southwest Airlines targets more than $2 billion of 2026 EBIT from assigned seating, extra legroom and bag fees despite higher fuel costs…
 Dhierin Bechai 4 clicks

Palo Alto Networks posted 34% Q4 revenue growth to $3.41 billion, boosted by CyberArk and Chronosphere, while NGS ARR reached $9.1 billion…
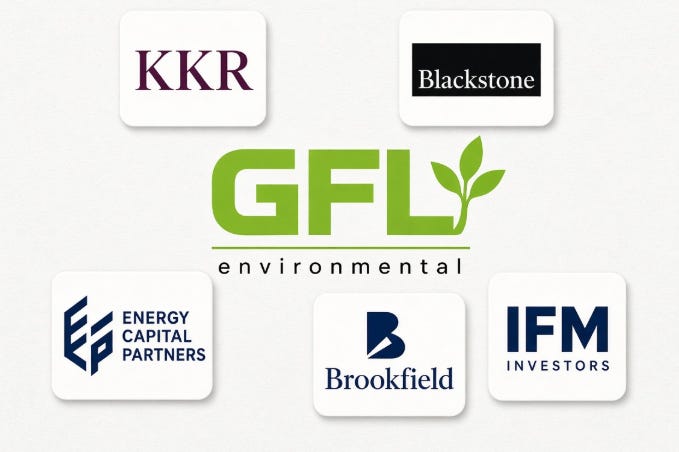
GFL’s take-private process has drawn KKR, Blackstone, Brookfield and IFM, while CEO Patrick Dovigi signals he will accept only the right…
 MSI · long
Motorola Solutions’ core value proposition remains intact after business changes since 2022, supporting a growth-at-a-reasonable-price…
Brookfield is recasting itself from an industrial owner into a $1.3 trillion asset manager and insurer, betting AI infrastructure can…
Karman Holdings (KRMN) is upgraded after a 68% drop, with 24% organic growth, a $1.3 billion backlog and higher 2026 guidance offset by…
Dhierin Bechai 
Steve Eisman argues AI extinction warnings from Dario Amodei and Sam Altman seek regulation that creates pricing moats.
Nintendo's Switch 2 attach rate, flat Switch Online accounts and rising memory costs fuel a bear case, while Spotify and Netflix margins…

DoorDash's grocery push targets a shift from weekly stock-up trips to frequent online fill-in orders, though smaller baskets complicate…
Planet Labs’ $116.1 million second-quarter revenue, 70% defense mix and planned Owl constellation position satellite imagery and AI data as…
 Petri Dish Reports 2 clicks
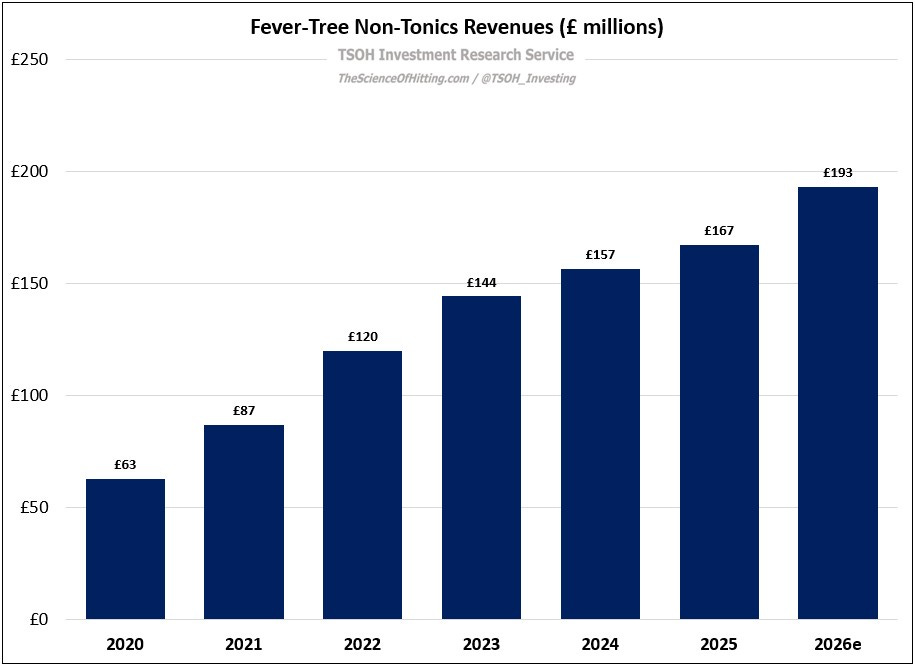
TSOH Weekly Roundup covers organized retail crime, Home Depot’s centralized operating missteps under Bob Nardelli, and research updates on…
Quantinuum's improving logical-qubit error correction, 1,504 successful-circuit benchmark score and paid deployments at RIKEN, BMW and…
Generac’s $2.4 billion Amazon generator agreement for 2027-28 anchors its data-center growth thesis, with 30% projected revenue growth in…
 Fernanda Galvez Jalil
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Atlas Diary
 Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 Daniel Jones
 Daniel Schönberger
 David Zanoni
 Deep Value Investing Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 M&M Capital
 Marc Gerstein
 Melissa Tucker
 Mike Arnold Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 Terry Chrisomalis
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey Value Capital Research
 Vishal Jadaun
 Yiannis Zourmpanos
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.