AI Terminator Fears Grow & Rates Breach 4.9% | The Weekly Wrap
Ten-year Treasury yields breach 4.9% as Steve Eisman discusses AI fears, OpenAI's price cut, Oracle's 30% revenue growth and Tesla's robotaxi setback.
Ten-year Treasury yields breach 4.9% as Steve Eisman discusses AI fears, OpenAI's price cut, Oracle's 30% revenue growth and Tesla's robotaxi setback.
@Freedom2Fart not a swing trader. and not that it matters, but the $AMZN trade in question was a one day options trade into expiration. fully exited.
$meta https://t.co/1JqV0PLtqm
@gamesblazer06 $GEV bulls probably didn’t see this coming… https://t.co/rVRcNDE52K
zero surprise $TTWO https://t.co/weuPg4PxZ7
How many $META users do they really see being willing and/or able to pay $200 per month for Hatch? I’m pretty good at ordering Doordash and scrolling Reddit on my own thank you very much https://t.co/2Oyf2hoyw4
Well, that escalated quickly. $TTWO https://t.co/J56bmG6WiS
Apollo Global Management’s five defining deals, from Executive Life to Intel, built a $1 trillion asset manager spanning insurance and…
NVIDIA sees inference, agentic workloads and robotics broadening AI compute demand beyond hyperscalers, while high-speed memory shortages…
Apple’s iPhone Duo foldable pairs a TSMC 2 nm chip, IP68 protection and iOS 27 features, positioning it against Samsung’s Galaxy Z Fold 8.
 Mark Hibben 1 click
Broadcom was upgraded to Accumulate at about $363 after Q3 revenue reached $29.6 billion, with AI semiconductor revenue up 221% to $16.7…

TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…
Nucor's growth and $250 fair value estimate hinge partly on the U.S.-Canada steel tariff dispute.
 Ray Merola

Applied Materials reported Q3 revenue of $9.1 billion, up 25%, and $2.3 billion in free cash flow as AMAT fell roughly 40% from its June…

AppLovin trades at 18 times EBITDA after a 57% drop, despite 84% EBITDA margins, rapid growth and a machine-learning advertising platform.
Williams Companies faces a revoked Northeast pipeline permit while pursuing growth through Momentum Midstream, Gulf export access and…
 Long Player
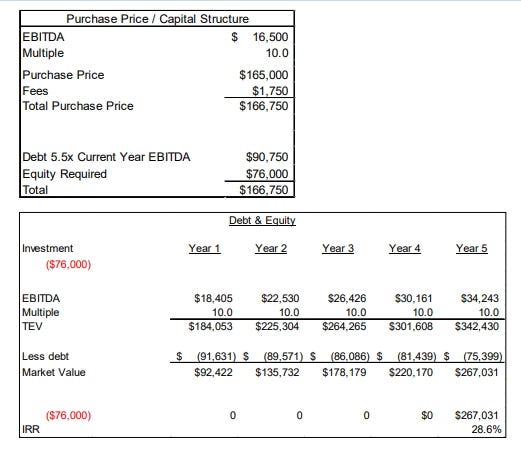
TransDigm’s sole-source aerospace parts generate roughly 70% aftermarket margins, with 90% of revenue tied to owned IP and 80% from…
Meta’s Muse personal agent connects multiple Gmail accounts, automates recurring tasks and offers free usage capped at 100 million weekly…
Deckers Outdoor has fallen about 60% from its late-2024 peak and trades at 11x earnings as HOKA growth slows.
Intercontinental Exchange's valuation case rests on 5% Q2 revenue growth, a 61% adjusted margin and $100 million of MarketAxess synergies.
 Mike Zaccardi, CFA, CMT
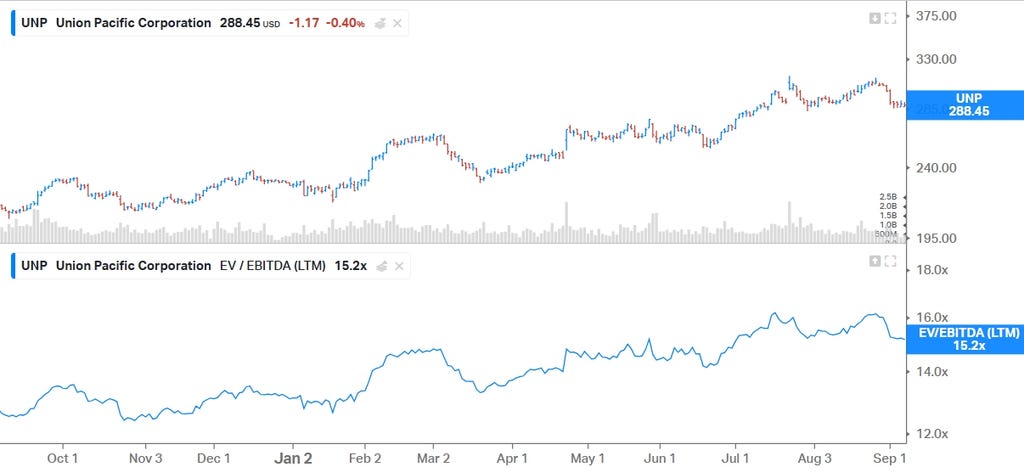
Union Pacific’s $85 billion Norfolk Southern merger pitch centers on a coast-to-coast rail network that cuts interchange delays and wins…

Dell’s Q2 revenue rose 57.7% to $47.0 billion and RPO tripled to $132 billion, but its stock trades at 32 times unlevered pretax free cash…
 FTAI · long
FTAI Aviation, valued near $23 billion at roughly $226 per share, is presented as a long investment.
Disney grew revenue 7% as buybacks and margins support earnings, but premium valuation, debt, rates, competition and legal risk point to…
 The J Thesis
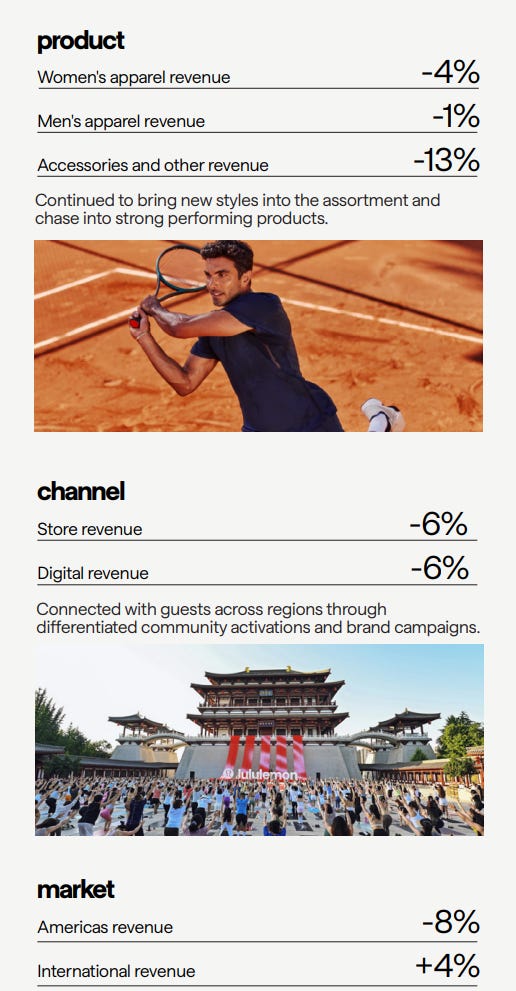
Lululemon’s Q2 revenue fell 4% and Americas comparable sales 12%, as markdowns, tariffs and activewear rivals pressure its premium apparel…
Ryan Tunis discusses P&C insurers, favoring Travelers over Chubb in a soft commercial market and calling AIG a near-book-value self-help…
Pinterest’s Q2 showed reaccelerating North American growth, while weaker international trends, AI-related engagement risks and elevated…
 Richard Durant 2 clicks
Every publication on this site, hand-picked.
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 LL Insights
 Marc Gerstein Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Robert J. Lake
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Steven Fiorillo
 The Bullionaire
 The Curious Analyst
 The Undercovered Dozen
 Value Capital Research
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.