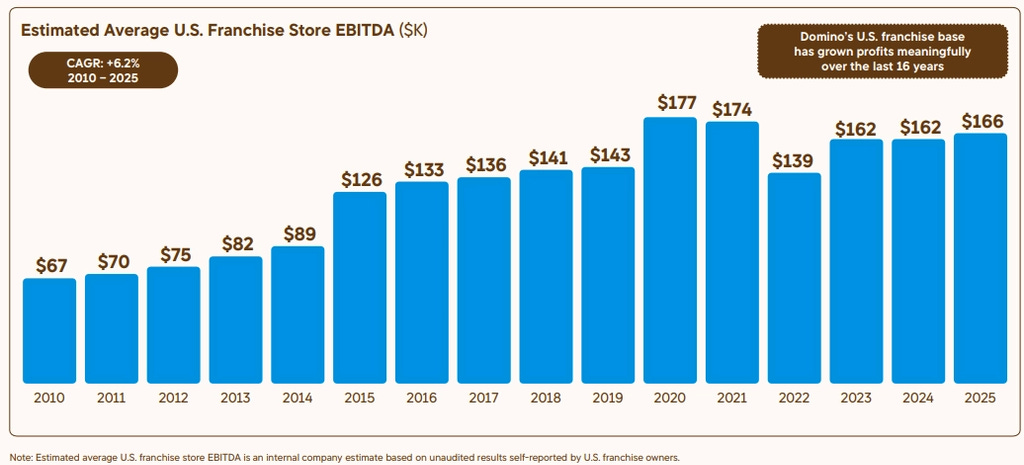
Domino’s built PULSE, online ordering and Pizza Tracker into a delivery machine, driving 10% annual global retail sales growth after its…
S scuttleblurb 4h ago 2 clicks
Nubank and MercadoLibre update target prices as Brazil’s 9% real rates, weaker currency and tighter credit favor their cost advantages and…
S Jimmy's Journal 6h ago 2 clicks
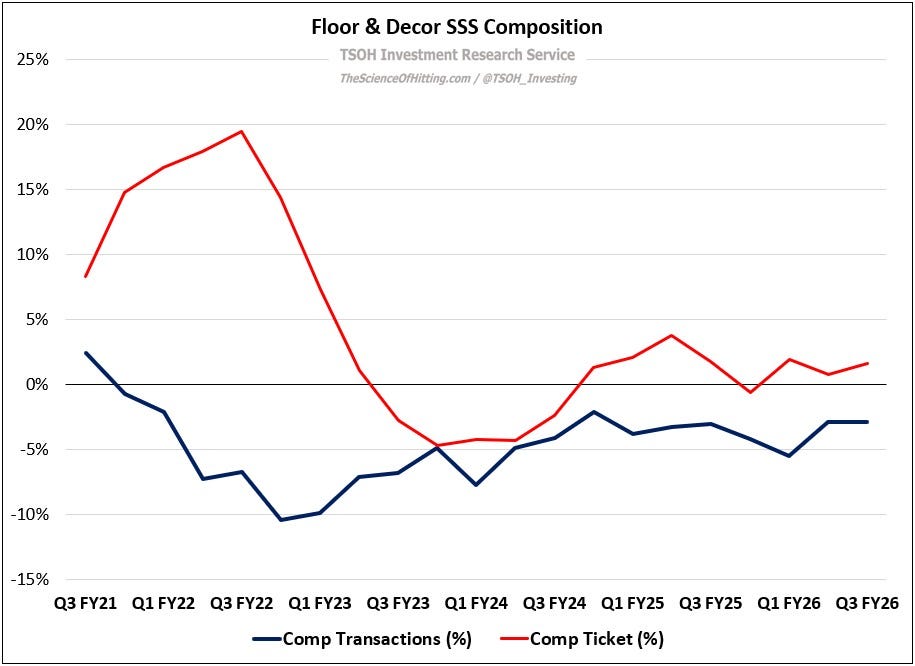
Floor & Decor has logged 20 straight quarters of comp transaction declines, with Q3 quarter-to-date same-store sales down about 3.8% as…
S TSOH Investment Research 6h ago 3 clicks
HCI Group grew Q3 revenue 13% and net income 27%, with $2 billion of invested assets driving investment income.
SA Given Mahlangu 8h ago 1 click TPG trades 20% below its average distributable-earnings multiple despite the fastest fee-related earnings growth among alternative…
S Capital Employed 16h ago 8 clicks
CDW CEO Chris Leahy says AI spending is entering a second wave focused on putting technology to work in everyday consumption.
BL The Technology Letter 18h ago 1 click
American Tower’s wireless network stayed operational during the FAA ground stop, while CoreSite lifted its 2026 data center revenue growth…
SA Brad Thomas 26h ago 3 clicks Intel’s custom ASIC business more than doubled last quarter as it pursues hyperscaler demand, AI accelerators and a stronger Intel Foundry.
S Chipstrat 28h ago 5 clicks
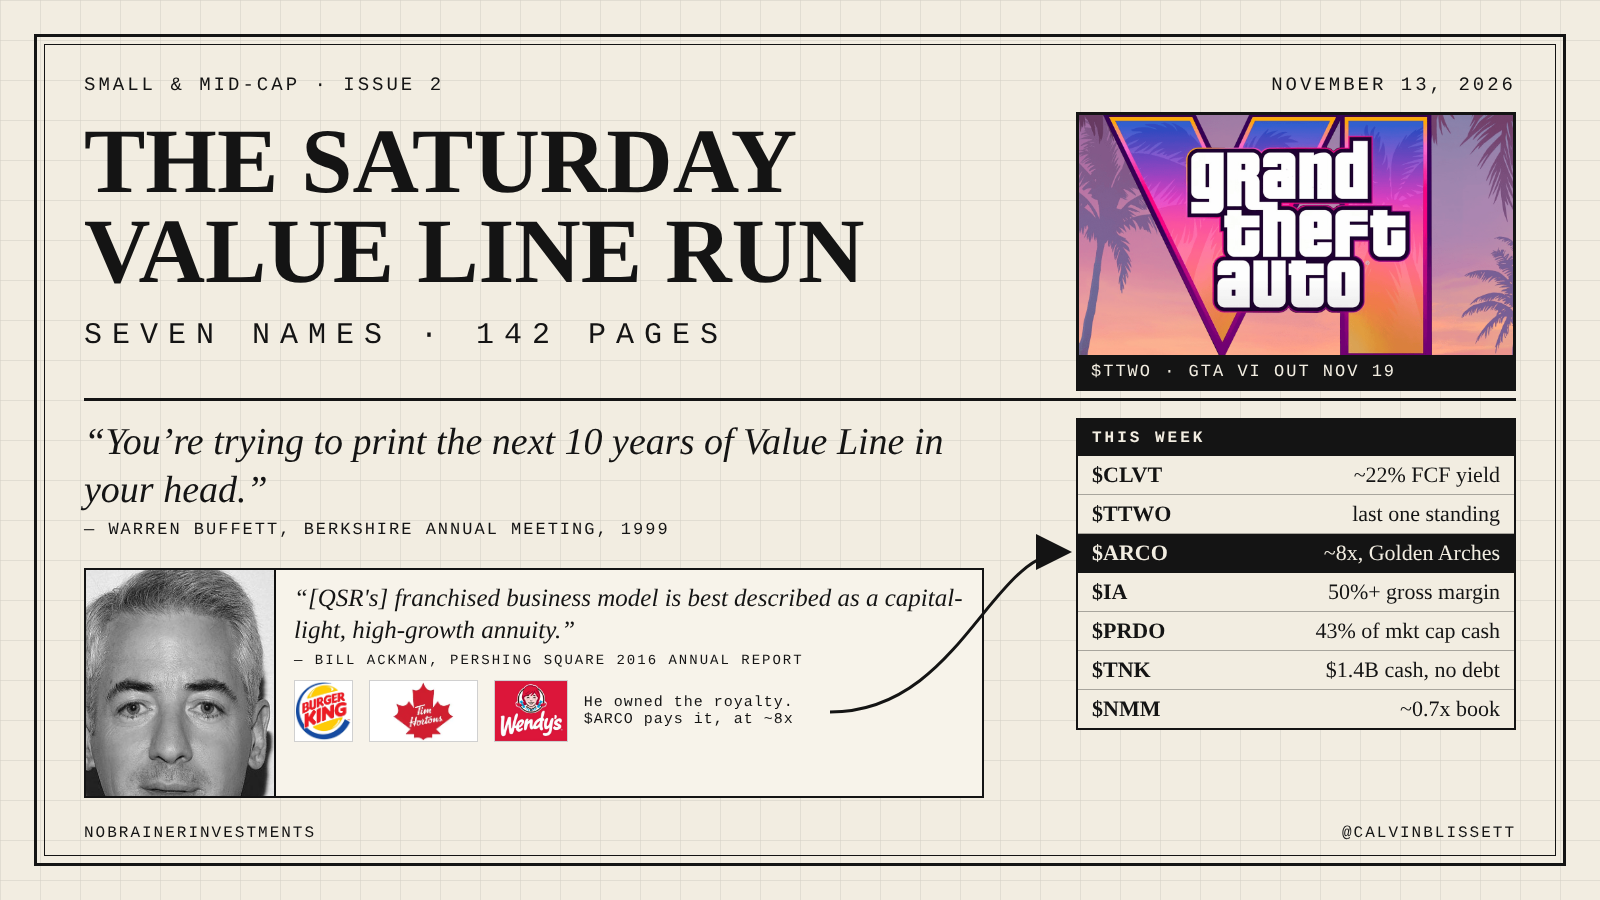
Clarivate, Take-Two and Arcos Dorados lead a seven-stock Value Line screen focused on debt paydown, GTA VI economics and Latin American…
S Calvin Blissett 28h ago 5 clicks
Celsius Holdings posted 17% Q3 revenue growth as Alani Nu and international sales rose 78%, offsetting a 6% decline in the core brand.
SA IWA Research 31h ago BKV · long BKV Corp, public for less than two years, is an underfollowed natural-gas producer pursuing early-stage projects and a transition.
BL Value Investors Club Jun 18 1 click
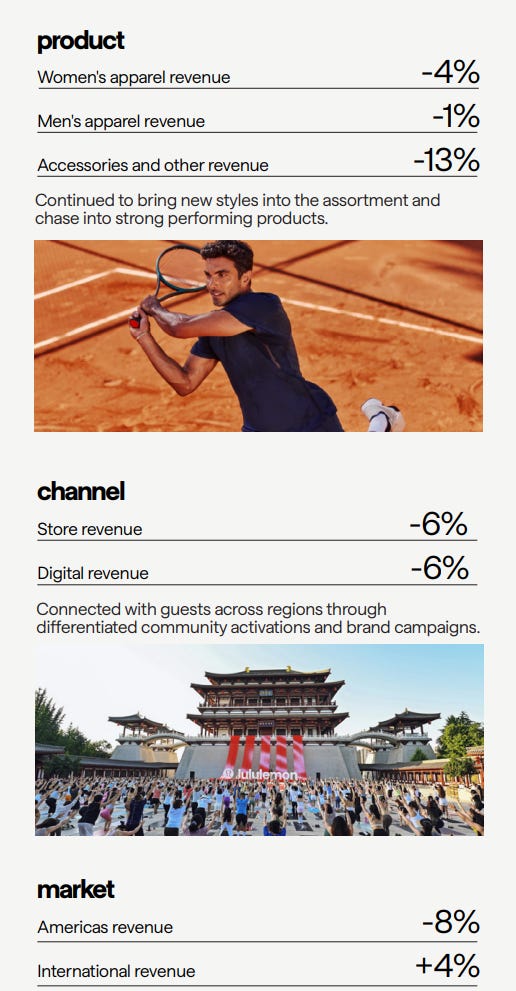
Lululemon’s North American sales, margins and legging demand are falling as Alo and Vuori gain share, leaving its brand moat and depressed…
S Hated Moats Sep 11 3 clicks
Chevron’s 2027 EPS could be underestimated by about $4.50 per share if U.S.-Iran conflict keeps oil near $100 rather than forecast $74 to…
SA Envision Research Sep 11 1 click Lululemon’s growth stalled as affordable-luxury apparel brands face fading post-Covid demand, cheap social-media influence and China…
S MBI Deep Dives Sep 11 2 clicks
Apollo Global Management’s five defining deals, from Executive Life to Intel, built a $1 trillion asset manager spanning insurance and…
S Net Interest Sep 11 1 click
TSOH weekly roundup covers Meta’s child-safety settlement, Markel’s leadership transition, Peloton’s gym strategy and an upcoming Alarm.com…
S TSOH Investment Research Sep 11 2 clicks
Independence Realty Trust is buying Centerspace in stock to create an $8.1 billion apartment REIT, targeting 5% 2027 Core FFO per-share…
SA Dane Bowler Sep 11 Dell closed Q2 2027 with a $95 billion AI-server backlog after $60.9 billion in quarterly orders, targeting data-center and enterprise AI…
S Monte Independent Investment Research Sep 11 2 clicks
Applied Materials reported Q3 revenue of $9.1 billion, up 25%, and $2.3 billion in free cash flow as AMAT fell roughly 40% from its June…
BL Cestrian Capital Research Sep 11 1 click
Joby Aviation is initiated at Accumulate after booking $116m of trailing revenue, forming a Toyota manufacturing venture and agreeing to…
BL Cestrian Capital Research Sep 11 1 click