Vicor Update, Part Four
Vicor’s Federal Circuit hearing put Foxconn’s disputed patent license under pressure, reinforcing its AI server royalty model and licensing leverage.
Vicor’s Federal Circuit hearing put Foxconn’s disputed patent license under pressure, reinforcing its AI server royalty model and licensing leverage.
$FOUR ride or die 🚀🚀🚀
$WEN rejects the Peltz proposal; adopts plan
*WENDY'S REJECTS TAKEOVER PROPOSAL FROM TRIAN PARTNERS-LED GROUP They did what now? $WEN
@aussieflya I’ve written and tweeted plenty Some continue to trade at discounts $CPT Some of them get bought out $ROIC $WSR $ALEX $PLYA $ Some of them get liquidated $ELME $SITC $AIV Some of them naturally trade close to NAV $CUBE
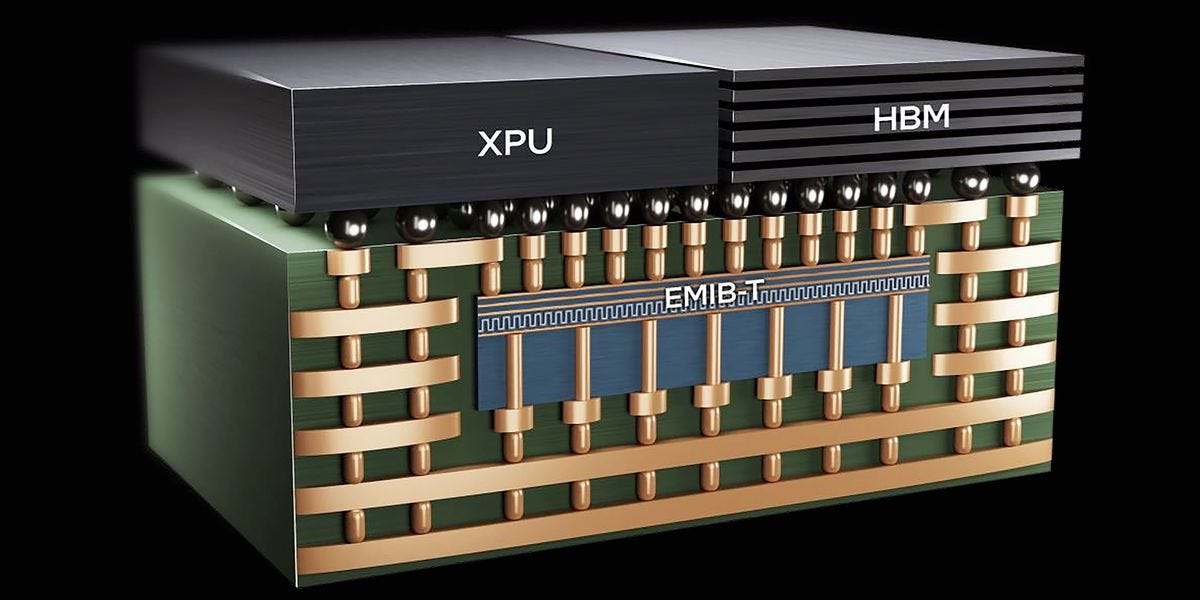
Intel’s EMIB-T, glass-core roadmap and 2027 ABF substrate supply outlook are the focus of an expert call.
Ouster grew Q3 revenue 50% to $59.3 million, shipped 27,000 sensors and guided Q4 revenue to $61 million to $64 million while posting a…
Floor & Decor’s 3Q26 sales rose 3% while comparable sales fell 1.4%; it cut 2027 openings to 10-15 as high mortgage rates pressure…

Floor & Decor's 3Q26 sales rose 3% while comparable sales fell 1.4%; it slowed 2027 openings to 10-15 as high mortgage rates pressure…
Kimberly-Clark’s Kenvue merger targets $1.9 billion in synergies by 2029, supporting roughly 6% long-term EPS growth and continued dividend…
 Gary Gambino 1 click
Blackbaud CEO says AI will be a tailwind for the nonprofit software and services provider.
Procore CFO Rachel Pyles discusses accelerating growth and economies of scale after an upbeat third-quarter report.
Diageo’s first quarter under CEO Dave Lewis showed modest price changes and regional growth outside North America, supporting a turnaround…
Tower Semiconductor reported $526 million in quarterly revenue and extended photonics contracts through 2029, while its low-loss silicon…
Perimeter Group posted 24% revenue growth to $390 million as fire-safety contracts and acquisitions lifted results, while it brings PDI…
 MTMTY · short
Metlen Energy & Metals faces a 40% short case centered on its overpriced aluminium, alumina and Greek power businesses.
McDonald’s U.S. comparable sales fell 0.2% as traffic declined, while a $280 share price assumes a turnaround despite weak free-cash-flow…
 Lee Bailey

Perimeter Group's third-quarter revenue rose 24% to $390 million as fire safety recovered and Specialty Products grew 84%, while…

AMD’s data-center revenue rose 97%, while MercadoLibre, TIC Solutions, XPEL and Zoetis also report quarterly results.
Marvell Technology’s Google custom-silicon win and upgraded long-term guidance lift its fair value to $187.35 standalone, or $199.48…
 Zbigniew Budzinski, CFA
EVC's Q3 update cites $30 million for a single station, a broadcast-business sale and stronger positioning for 2027.

Steve Eisman links a Democratic midterm sweep and CoreWeave concerns to an AI narrative shift as the S&P 500 fell 4.4% and Nasdaq 5.5%.
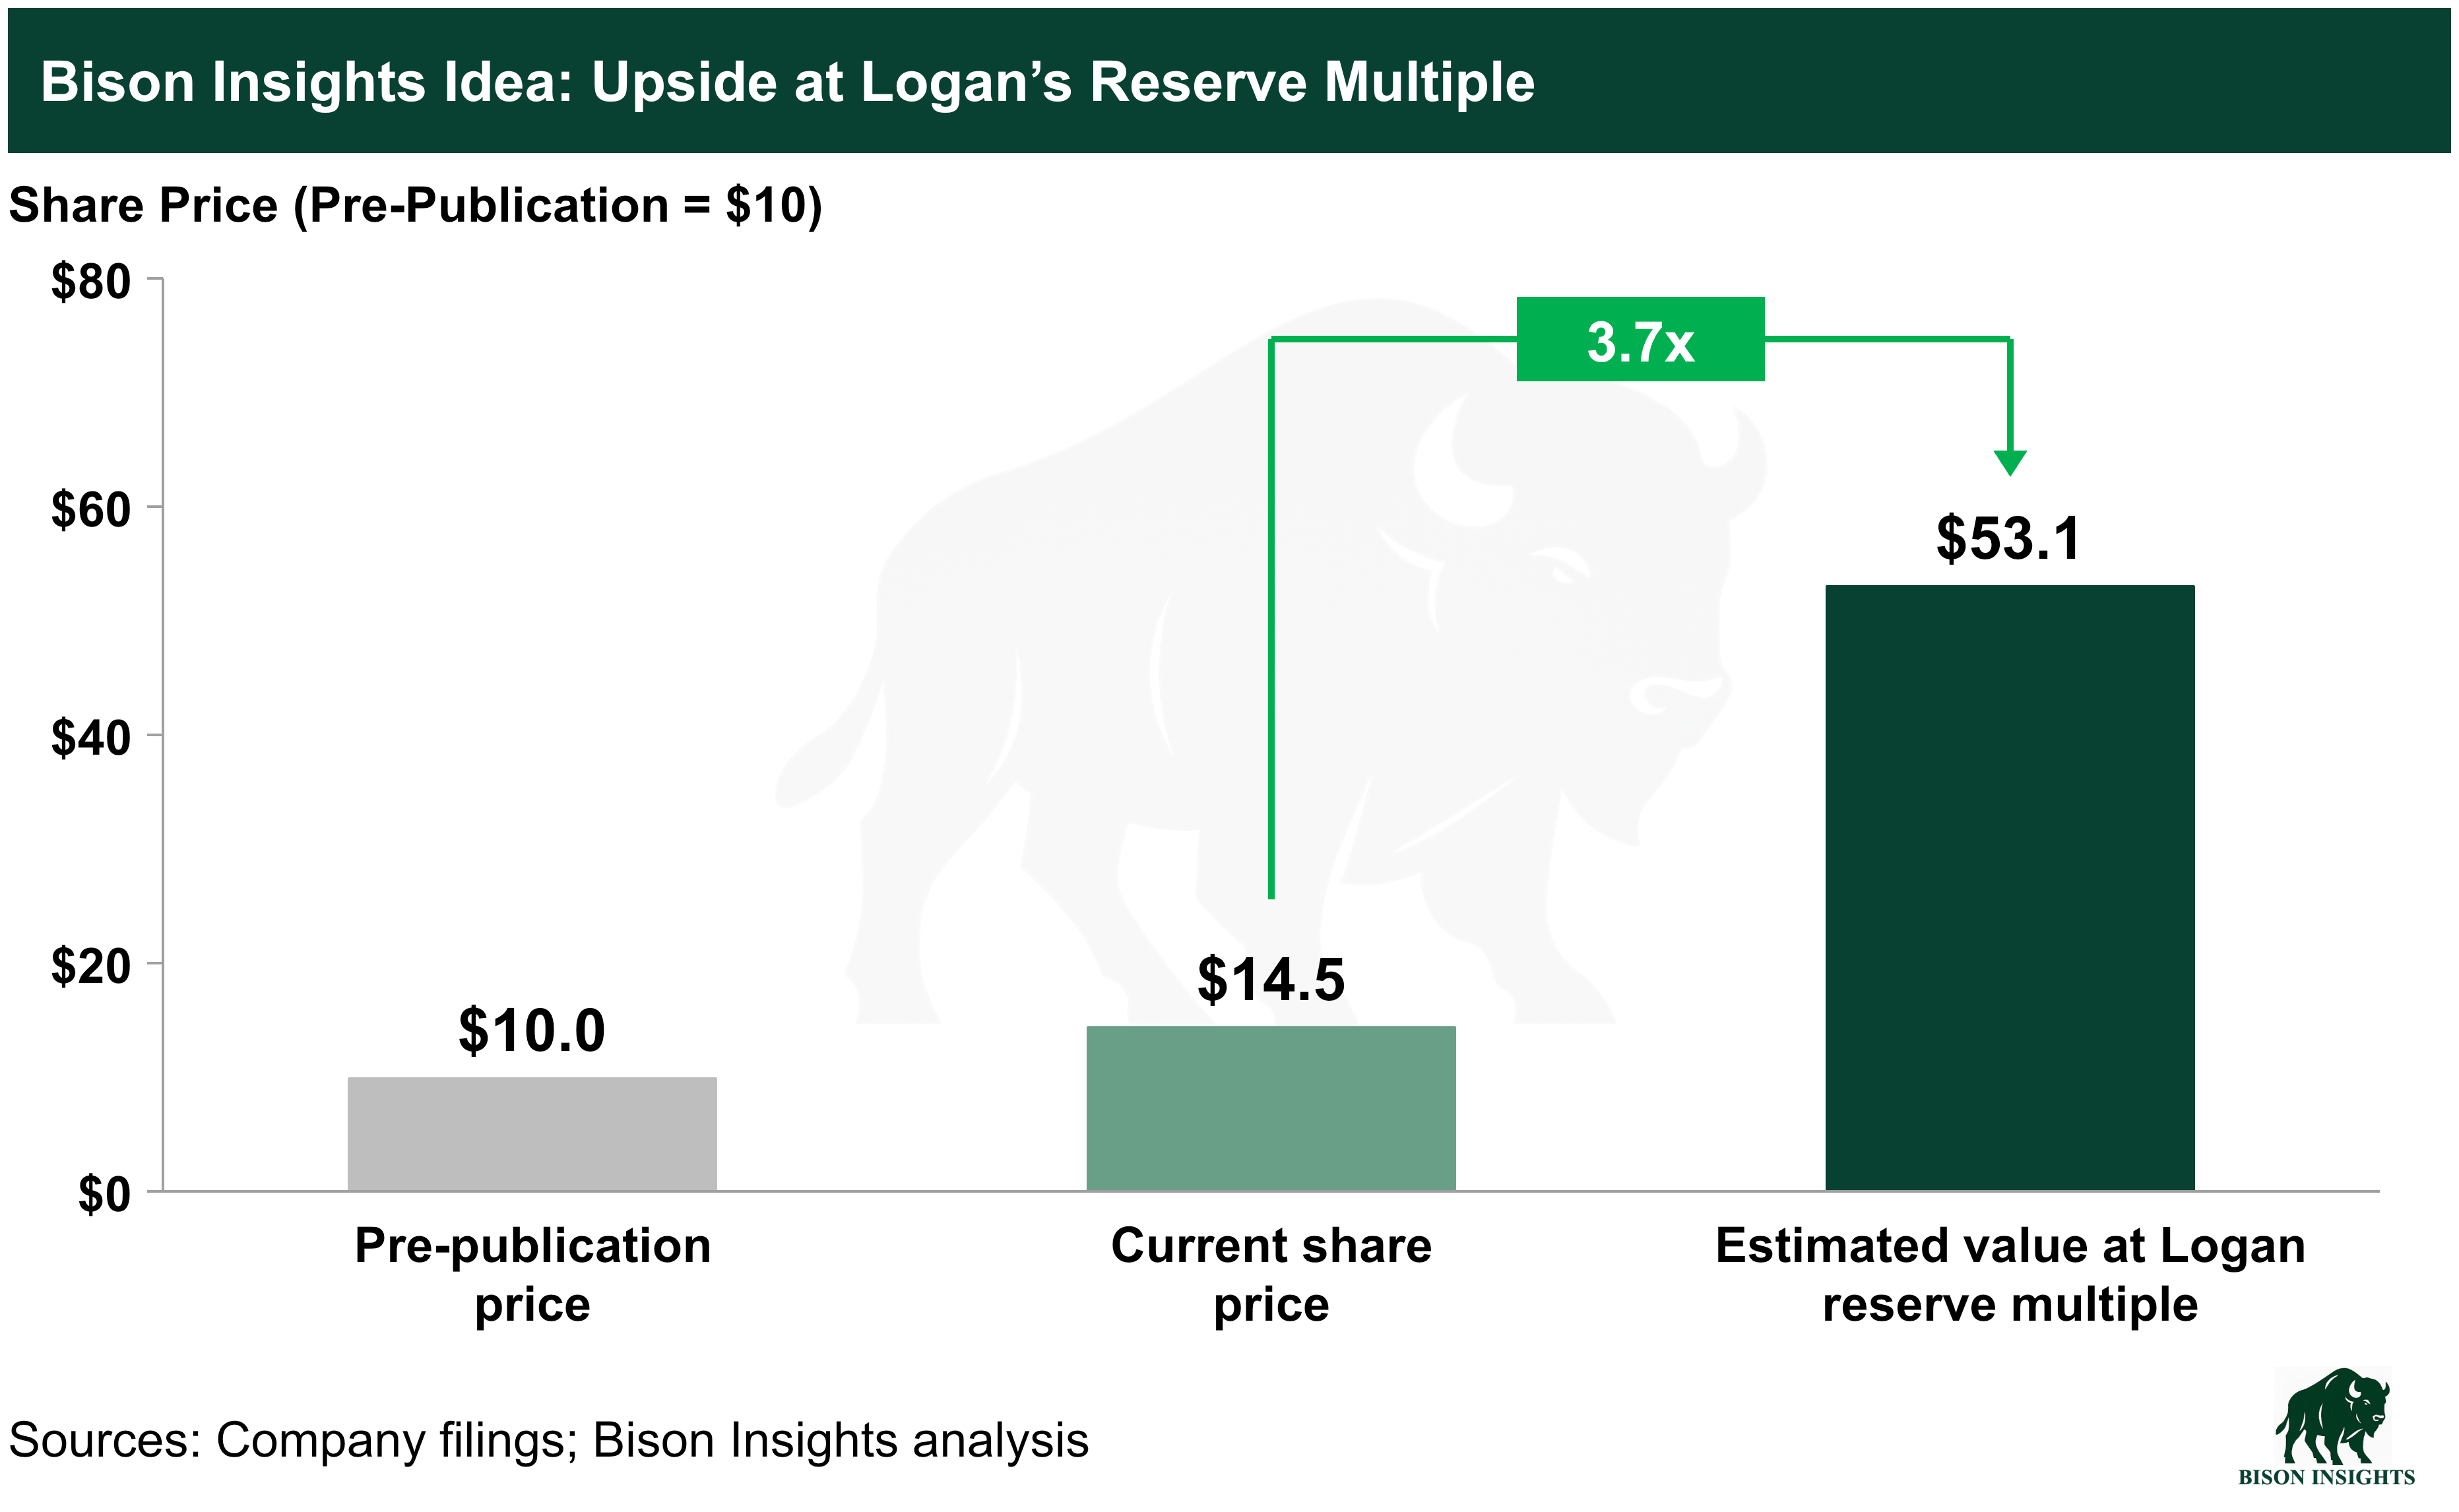
Ovintiv’s C$1.26 billion purchase of Logan Energy at roughly 2x proved reserve value points to further consolidation among Canadian oil…

Entravision’s Q3 ad-tech revenue reached $177.2 million, up 133% year over year, while total revenue rose 88% to $226.3 million and diluted…
Transocean’s 25.6% selloff reflects oil-market shorting and weak Q3 headlines, while debt reduction after the Valaris acquisition could…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead Gary Gambino
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.