The Midterms Have Changed the AI Narrative: S&P Down 4.4%, Nasdaq Down 5.5% | The Weekly Wrap
Steve Eisman links a Democratic midterm sweep and CoreWeave concerns to an AI narrative shift as the S&P 500 fell 4.4% and Nasdaq 5.5%.
Steve Eisman links a Democratic midterm sweep and CoreWeave concerns to an AI narrative shift as the S&P 500 fell 4.4% and Nasdaq 5.5%.
After taking a yuuuge loss by (somewhat) trusting Walgreens' former CFO (at $FIS), I'm plowing into $Adyen, where Klarnas' new CFO will soon be wielding his influence. Ride or die.🤡🚗 🚀 https://t.co/Ry1AAp4WbI
That’s just blatantly false, there’s heavy industry doubts if MicroLED are even commercializable for CPO. Also regarding $COHR on optical demand: “We continue to see no signs of attenuation in demand.” Laser demand is independently as strong as memory, and Coherent / Lumentum wouldn’t be signing $20B or $5B LTAs left and right.
Was reading MonotaRO's latest results and realized that $3064.T, basically the 🇯🇵 version of $GWW/Zoro.com, has been compounding at ~25% annually for two decades. And the last time you could buy the stock below 20x earnings was back in 2011. https://t.co/YdOm27MJON
Bullish china. $GDS and $VNET the two US listed Chinese Data centers were trading at their lows --- likely to benefit if we let china Win AI https://t.co/Tp9F9ADC7H
Axon cut full-year guidance after delayed federal Dedrone contracts slowed 3Q revenue growth to 28%, while software and services grew 43%.

Axon’s 3Q26 revenue growth fell to 28% after delayed federal Dedrone contracts, while software grew 43% and its $1.2 billion Skydio…

Datadog beat Q3 revenue guidance by $52 million, but guided Q4 revenue flat as its largest AI-native customer reduced usage after renewing.
Alpha Metallurgical posted a third consecutive quarterly loss as High Vol A coal margins fell to $14 a ton, while director Kenneth Courtis…
Shift4’s Q3 met guidance, but organic growth is decelerating, management credibility is weakening and leverage reduction remains too slow.
Vicor earns a Strong Buy after record Q3 results and AI gains, while QXO falls to Hold over capital structure and execution risk.
Cloudflare’s Q3 revenue rose 39% to $782.5 million, its fastest growth in nearly four years, while a $67.9 million GAAP operating loss and…
Dynatrace reported 17% Q2 revenue growth but flat new ARR and lower profit and free-cash-flow guidance, following its $816 million Arize…
Reddit fell 29% after warning that Google search traffic was declining, despite Q3 revenue rising 53%; the bull case rests on communities,…
 Bernard Zambonin 1 click
Marvell’s Lumentum acquisition targets optical networking demand as AI data centers shift from copper to lasers, expanding its hyperscaler…
Blue Owl Capital's NAV rose to $14.32 as buybacks and portfolio marks improved, while OBDC trades at a 25% discount despite a 0.33%…
 Tim Travis 1 click
 AAP · long
Advance Auto Parts, AAP, is presented as a long idea following prior write-ups at $48.81 per share in January 2025.
TransMedics reported record Q3 2026 revenue exceeding $200 million, driven by its organ transplant technology business.
JFrog jumped 35% to $100.44 after another beat-and-raise quarter, joining the TL20 Special Situations group.
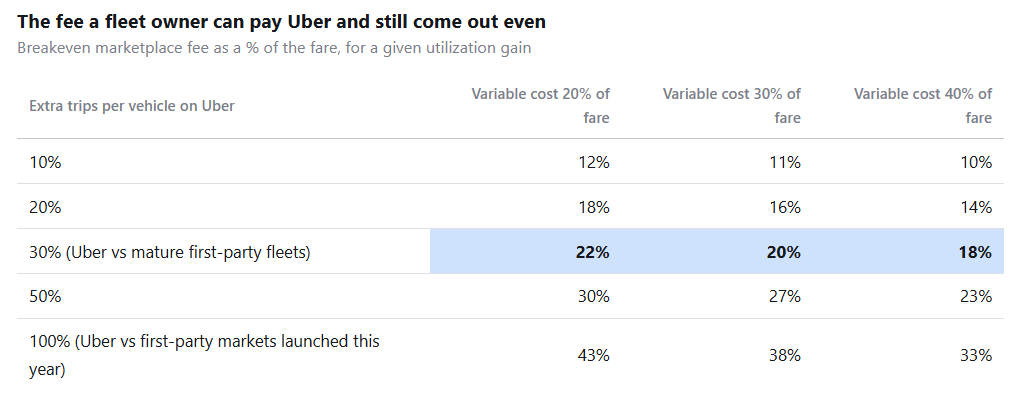
Uber Delivery generated an estimated $0.66 EBITDA after SBC per order in 3Q26, versus DoorDash's $0.80, while autonomous vehicles shape…
MercadoLibre’s logistics expansion cut margins by 60 basis points, while Mercado Pago grew credit 62% with 7% NPLs.
Twist Bioscience’s $200 rebound followed an Anthropic-linked short squeeze, yet its DNA and protein services face broad competition while…

Vishay reported record Q3 revenue of $979 million, up 24%, and guided Q4 to about $990 million as rising backlog and margins contrast with…
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests
 Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.