

Thursday, November 5, 2026
Back to the front page 
From X
JabroniCoin.USD on X
UBS: We believe $CENX offers the best leverage to a US Regional Premium that is sustainably higher. CENX currently trades at ~3.1x UBSe 2027 EBITDA estimates (below ~5x normalized 5yr average). We expect CENX to rerate towards our ~4x peak multiple driven by clarity…
DOMO Capital Management, LLC on X
Another $PBI debt upgrade... "Pitney Bowes Inc. Upgraded To 'BB-' From 'B+' On Strong Credit Metrics; Outlook Revised To Stable From Positive"
Colin King on X
Risk/reward at $75 looks really attractive… Own some $CALM common and Feb 2027 call spreads at $80 / $85 strike DYODD :)
A Capital on X
@DreamPositiveCp @grok what is the binary event for $NN?
Fierce_beast on X
@FishtownCap Could $UNFI and $CHEF merge or too much overlap already
Investor Letters
All letters- Forager Funds Management October 2026 OFX $70MPLT $96M
- Rathbones October 2026 SBGSF $143BSIEGY $237B
- FCL Capital October 2026 ANPDF $28BBKNG $122B
- Protean Funds October 2026 AAK $4.6BLFABF $13B
- JB Global Capital Q3 2026 BABA $262BFLO $1.4B
- Pendelhaven Asset Management B.V. Q3 2026 DR0 $416MALM $2.5B
- Chautauqua Capital Management Q3 2026 AAIGF $103BADYEY $32B
- Night Watch Investment Management Q3 2026 AZLGF $3.3BIMCDY $6.7B

Wolfspeed: Still Bullish After A Post-Earnings Wipeout
Wolfspeed's negative Q1 margins and revenue decline have not changed the bullish case for silicon-carbide power devices in data centers.
 Vince Martin 7 clicks
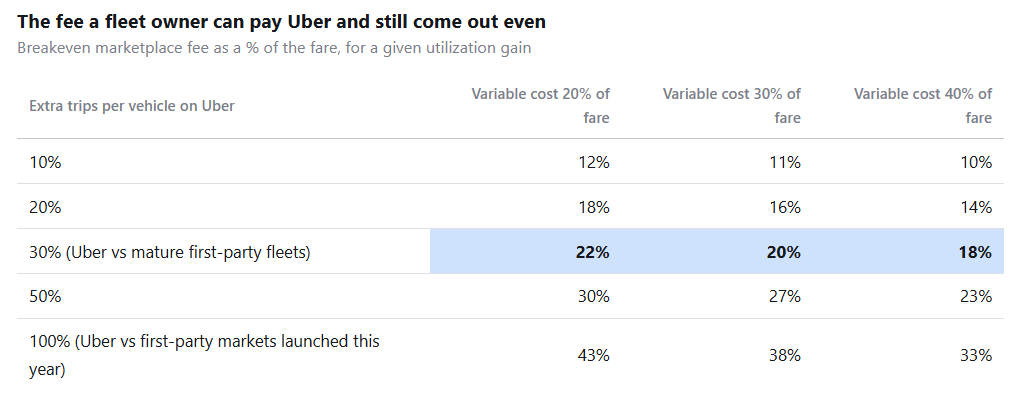
Uber 3Q'26: Eats vs DoorDash, and the AV Math
Uber Delivery generated an estimated $0.66 EBITDA after SBC per order in 3Q26, versus DoorDash's $0.80, while autonomous vehicles shape…
Trading Post November 5, 2026
MercadoLibre’s logistics expansion cut margins by 60 basis points, while Mercado Pago grew credit 62% with 7% NPLs.
Uber: The Robotaxi Discount Has Truly Gone Too Far (Earnings Review)
Uber's Q3 growth, margin expansion and rising cash flow clash with a bear-case valuation as investors price in robotaxi disruption risk…
 Luca Socci 4 clicks
Intel: The CPU Comeback, Discounted
Intel's Q3 2026 results were hit by memory costs and an Israel shutdown, but enterprise AI inference could lift CPU demand as server…
Problems at Twist Bioscience (TWST)
Twist Bioscience’s $200 rebound followed an Anthropic-linked short squeeze, yet its DNA and protein services face broad competition while…

VSH Earnings Review
Vishay reported record Q3 revenue of $979 million, up 24%, and guided Q4 to about $990 million as rising backlog and margins contrast with…
This Week in Special Situations: Lear, AutoNation, NexPoint, AudioCodes, Xponential Fitness
AutoNation, Lear, NexPoint, AudioCodes and Xponential Fitness lead a 52-situation screen spanning buybacks, insider purchases, M&A and…
Array Technologies And Shoals Merger Creates Upside Potential
Array Technologies and Shoals Technologies plan to merge, targeting cross-selling and cost synergies as ARRY's order book holds firm and…
 Caffital Research 3 clicks
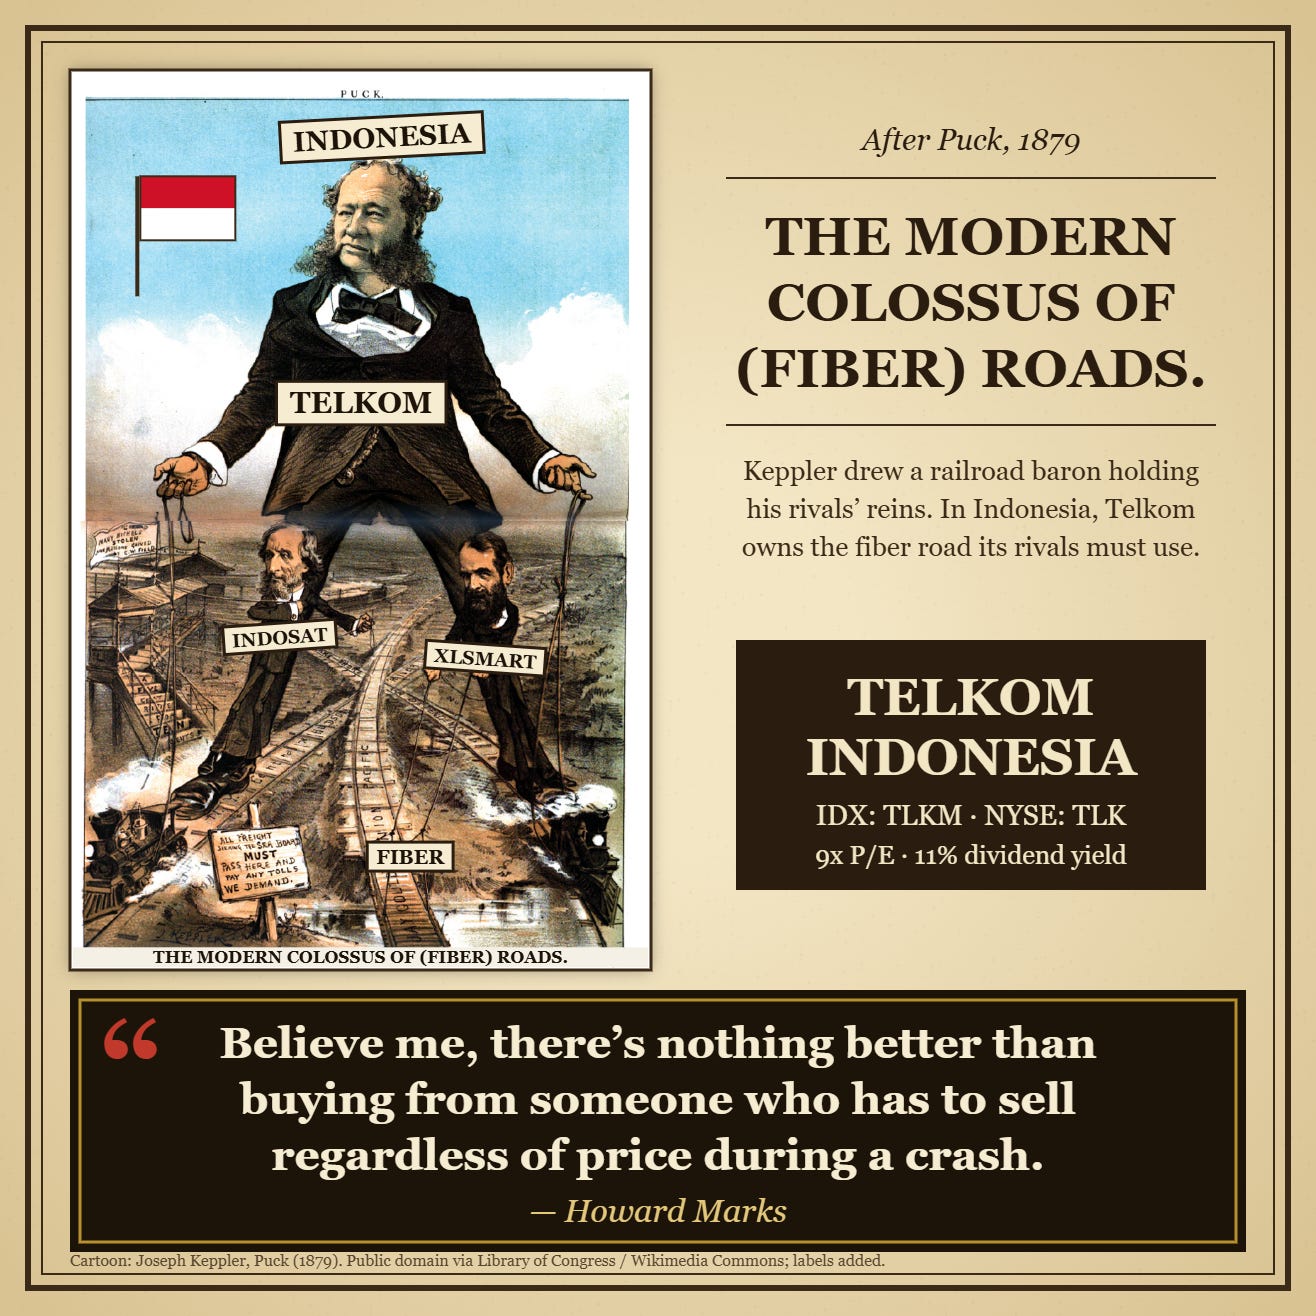
Telkom Indonesia (TLKM/TLK): 9x P/E, 11% dividend, separable assets ≈80–95% of market cap, stub at ~2x EBITDA. Industry went from 11 operators to 3, a new rule kills the price war, and MSCI is forcing the sellers.
Telkom Indonesia trades at 9x earnings and an 11% yield as MSCI-driven selling obscures telecom consolidation, price increases and…
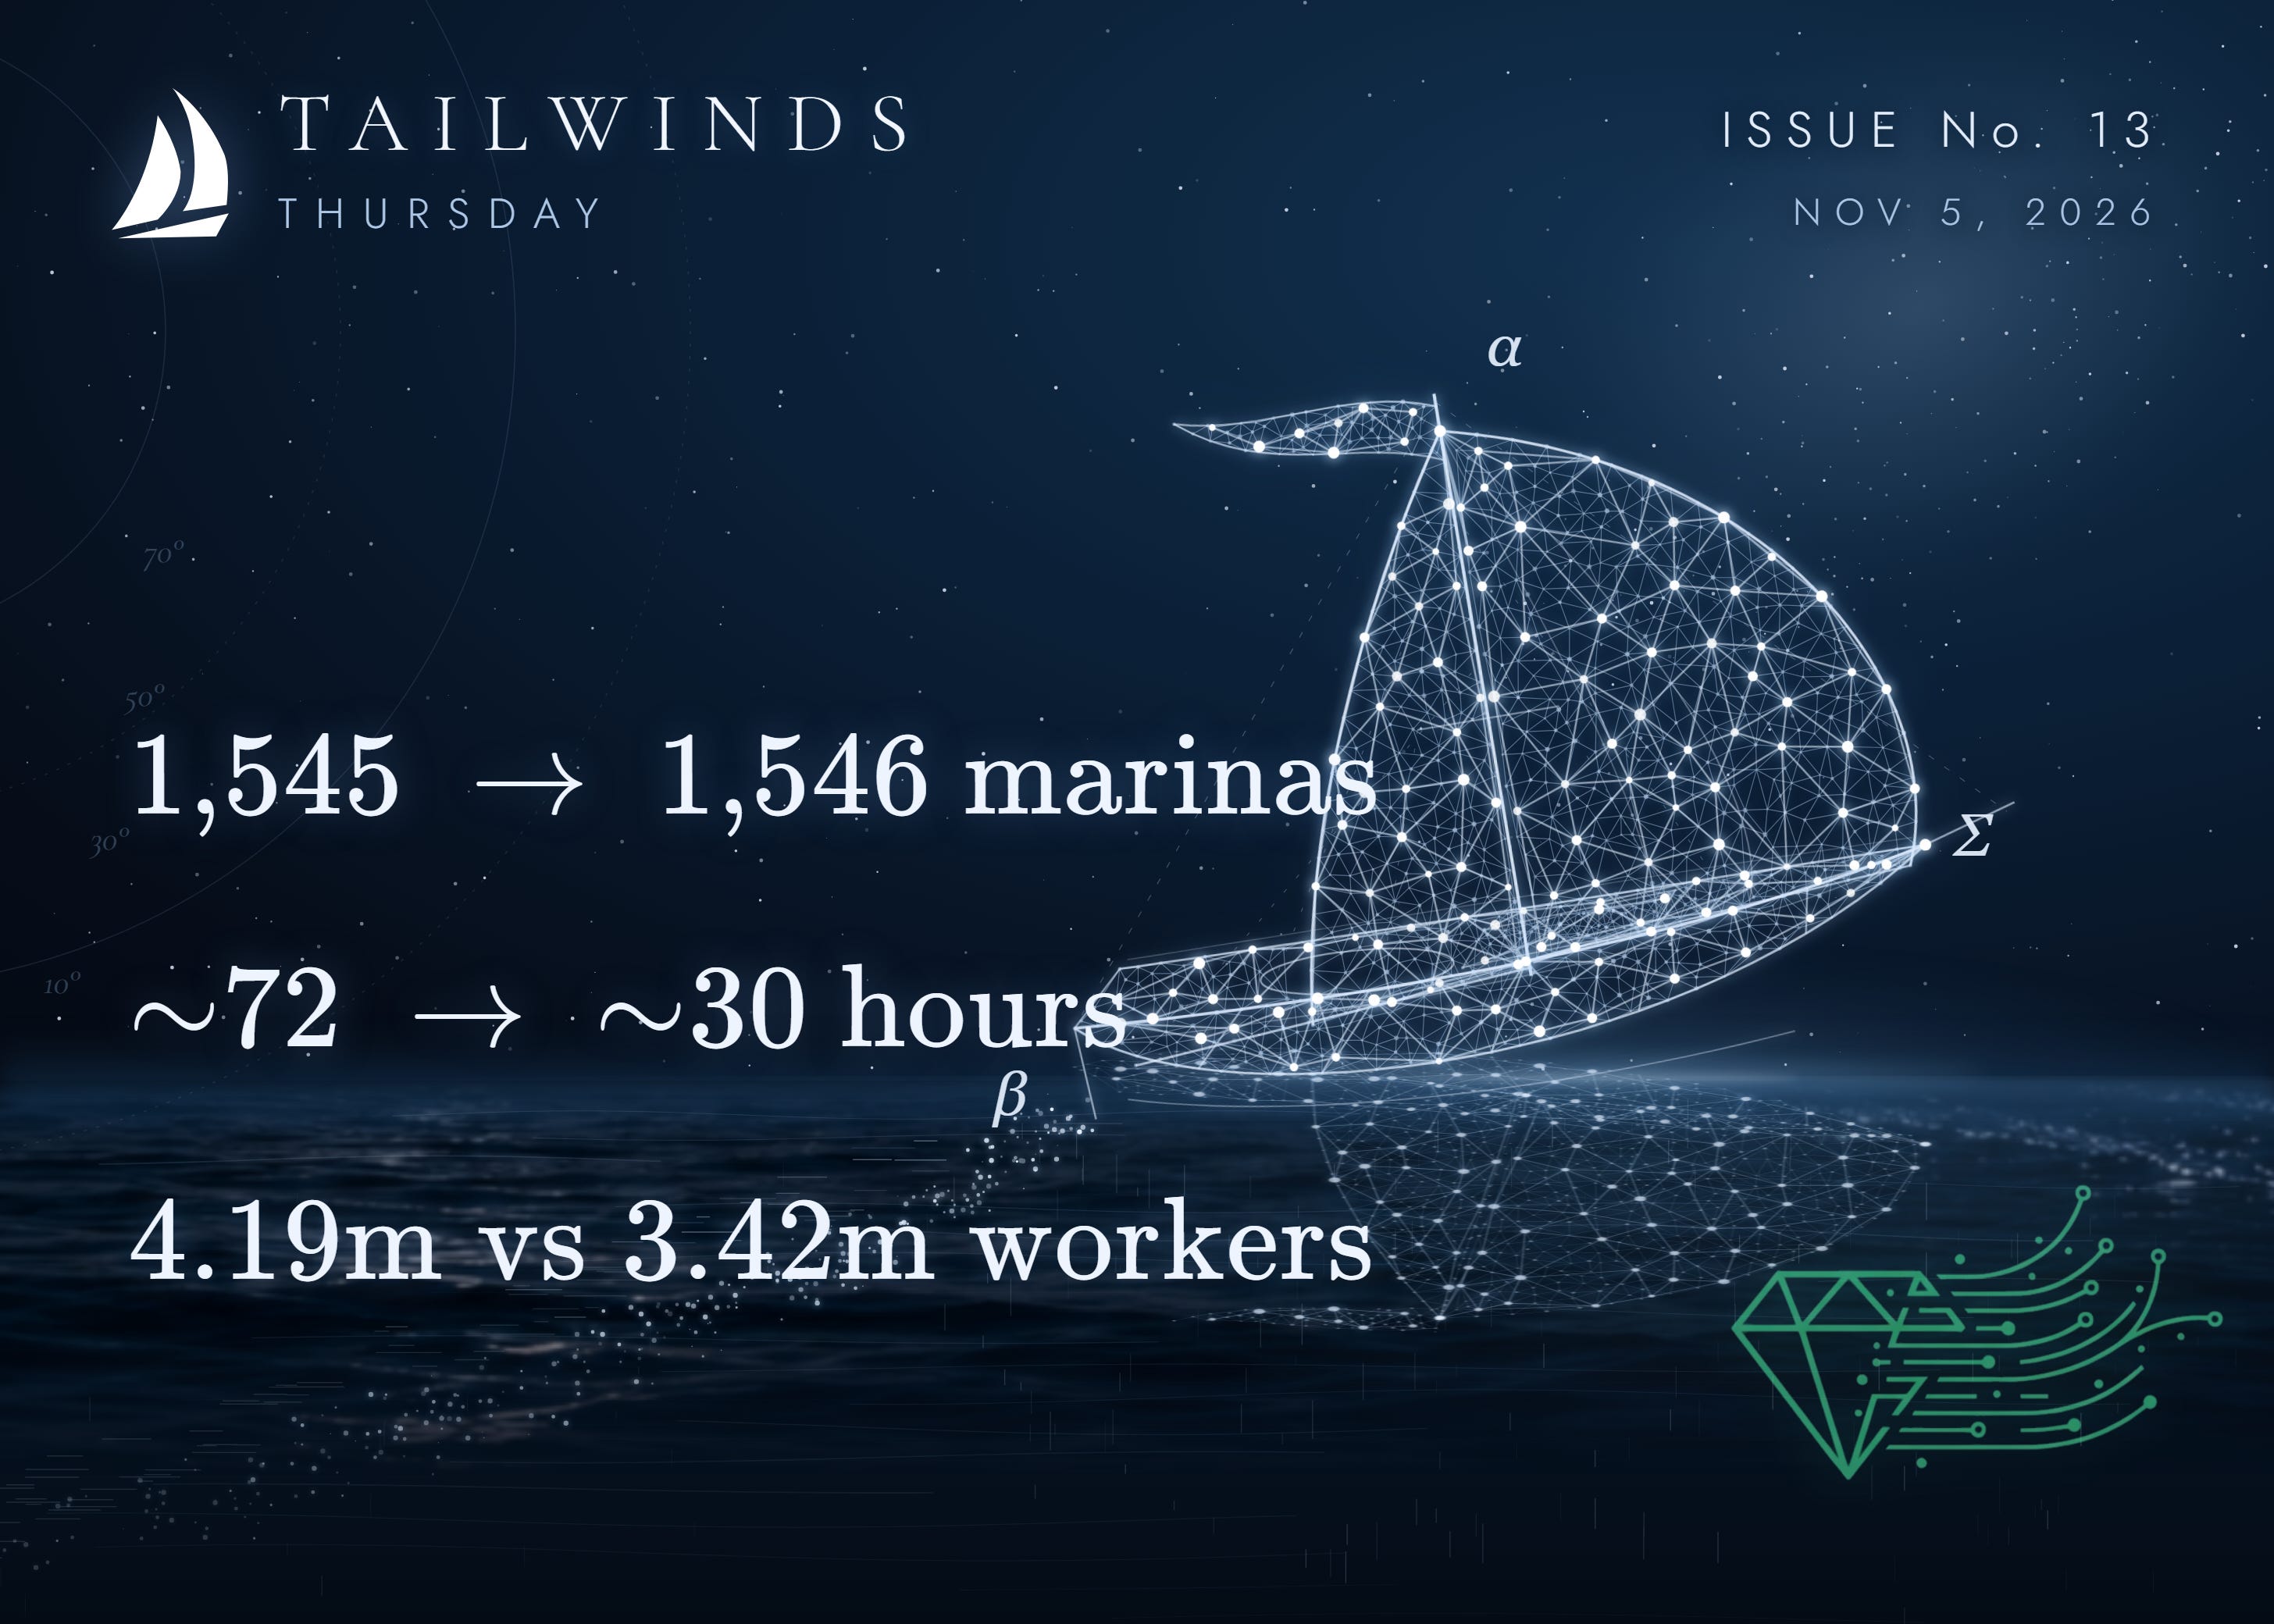
Thursday Tailwinds #13: Nov 5, 2026
Florida marinas are 92% full as boat counts rise and permits constrain new supply, creating pricing power for existing operators such as…
eToro: Expanding Beyond Crypto
EToro trades at 2.89x EV/FCF with $304 million in trailing free cash flow, expanding from crypto into equities, commodities, currencies and…
 Max Arnoldi 5 clicks
 SILC · long
Silicom LTD
Silicom (SILC) is pitched as inexpensive on its existing hardware business, with upside framed as a cheap call option.
Amdocs: The T-Mobile Shock Changes Everything (Rating Downgrade)
Amdocs cut FY27 guidance after a T-Mobile dispute, projecting a 7–11% revenue decline and backlog down nearly 10% to $3.5 billion.
 Motti Sapir 2 clicks
The Buyback Shows Up (ESRT Q3 2026)
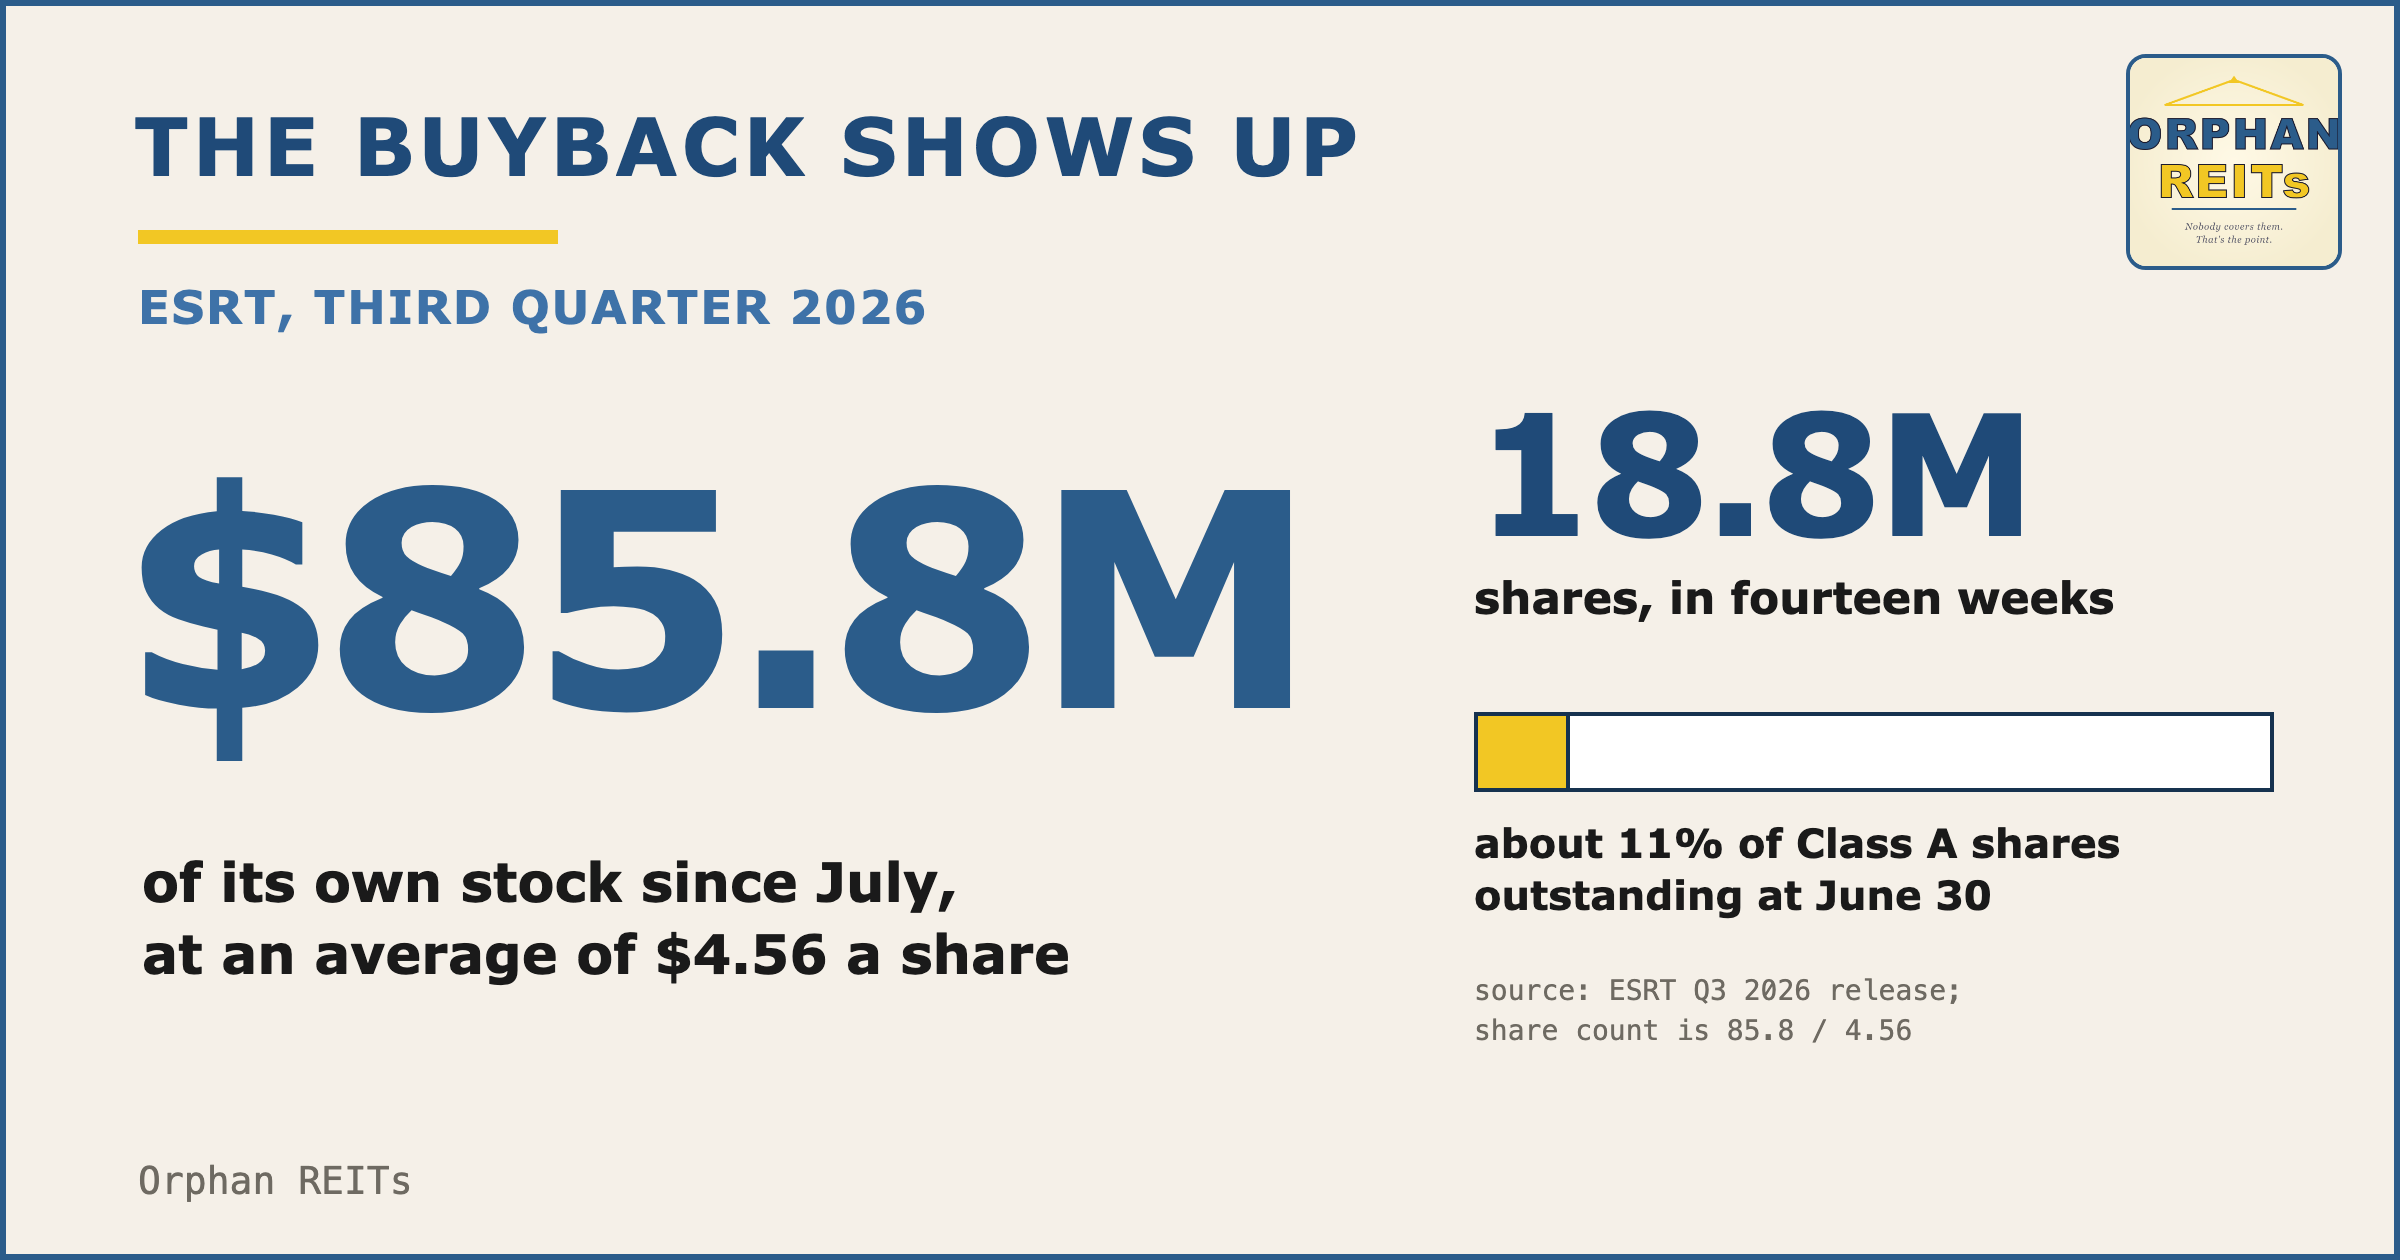
Empire State Realty Trust repurchased $85.8 million of shares at $4.56 each, using 1359 Broadway sale proceeds to fund buybacks and debt…
Warrior (HCC): Q3 2026 Earnings
Warrior Met Coal’s Blue Creek mine cut costs to about $93 a ton, offsetting a wider discount for High Vol A coking coal as US supply…
GPC Q3 2026: a quick North America Automotive update
GPC’s NAPA commercial sales grew 4% in Q3, trailing AutoZone and O’Reilly as freight, fuel and rent cut North American Automotive margins…
Research Note
Nine Mile Metals is the subject of a research note.
AMSC, Datadog will be fine, SiTime is worth a look
AMSC and Datadog will be fine, while SiTime is worth a closer look.
An Interview With Intuit CEO Sasan Goodarzi About Accounting and AI
Intuit CEO Sasan Goodarzi discusses using AI to turn accountants from customer-acquisition partners into customers, alongside QuickBooks,…
Publications we follow
Every publication on this site, hand-picked.
Newsletters 109
- 310 Value’s Newsletter
- Absurdly Cheap Stocks
- Altay Capital - Mostly Value Investing
- AmsterdamStocks
- Asian Century Stocks
- Aurelion Research
- Base Hit Investing
- Bearhold Research
- Bearstone
- Behind the Balance Sheet
- Best Anchor Stocks
- Bilbel's Substack
- Bison Insights
- Brevarthan Research
- Bristlemoon Capital
- Byron Street Research
- Calvin Blissett
- Cannibal Stocks
- Capital Employed
- Capitalist Letters
- Cassandra Unchained
- Chipstrat
- Citrini Research
- Cluseau Research
- CV's Substack
- D Invests
- Daniel Romero
- Deep Value Insights
- Dismissed & Asset-Backed
- Doomberg
- Eagle Point Capital
- Easy Value
- Emerging Moats Research
- Exploring with Alluvial Capital
- Ezra's Notes
- Fabricated Knowledge
- First Strike Research
- Flyover Stocks
- Global Outperformers
- Guardian Research
- Hated Moats
- Hayden Capital
- Healthy Stock Picks
- HFI Research
- Hidden Gems Investing
- Hidden Rock Capital's Newsletter
- Ian’s Insider Corner
- Iggy on Investing Newsletter
- Inglenook Growth
- Invariant
- Invested Capital
- Investing 501
- Irrational Analysis
- Jimmy's Journal
- John Hempton's Newsletter
- Kairos Research
- Kakashii's Materials
- Key Context by Tae Kim
- Latticework by MOI Global
- Lewistown Capital
- Librarian Capital's Research Library
- Maius Partners
- MBI Deep Dives
- Mispriced Assets
- Modern Value Investing
- Monte Independent Investment Research
- Multibagger Monitor
- Nat Stewart - Stock Picking Newsletter
- Net Interest
- Nongaap Investing
- Nugget Capital Partner's Substack
- Open Insights
- Orphan REITs
- Overlooked Alpha
- P Equity Research
- PETITION
- Phynvesting
- Raging Bull Investments
- Real Assets, Real Value
- Rebound Capital
- Rod’s Ruminations
- ROE The Boat
- scuttleblurb
- Sector Stories
- SemiAnalysis
- Shallow Dives
- Singularity Research
- SixSigmaCapital: Navigating the Financial Markets
- Sleep Well Investments
- Speedwell Memos
- Stock Thoughts
- Substack von Philipp
- Sunday's Idea Brunch
- Sylence Capital
- The Curious Compounder
- The Mikro Kap
- The Oak Bloke
- The Rational Walk
- The Value Road
- Trade Ideas Flow
- Treasure Hunting
- Triple S Special Situations Investing
- TSOH Investment Research
- Underlying Value
- Value Don't Lie
- Vik's Newsletter
- WHAT ARE WE DOING? “Contrarians At The Gate”
- XIX Value
- Yet Another Value Blog
Blogs 15
- Atrium Research - Equity Research
- Bireme Capital - Investor Letters
- Cestrian Capital Research
- Choice Equities Capital Management
- Clark Street Value
- Crossroads Capital | Research-driven, Value-centric
- Hunterbrook
- Kerrisdale Capital
- NoNameStocks
- Raging Capital
- Speedwell Research
- Stratechery by Ben Thompson – On the business, strategy, and impact of technology.
- The Technology Letter
- Undervalued Shares
- Value Investors Club
Seeking Alpha 77 of 280
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Gary Gambino
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
- Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
X accounts we follow
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
- RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Investor letters we follow
- 1 Main Capital
- 103 Advisory Group
- 1290 Funds
- 13D Activist Fund
- 1851 Capital
- 49 Financial
- ABS Global Investments
- ACATIS Investment
- Aberdeen Investments
- Accelerate Financial Technologies
- Advisors Capital Management
- Advisory Research
- Aegis Value Fund
- Aikya Investment Management
- Akre Capital Management, LLC
- Allspring Global Investments
- Alluvial Capital Management
- Alpha Wealth Funds
- Alpine Capital Research
- Alpinum Investment Management AG
- Amati Global Investors
- Amber River
- Andrew Hill Investment Advisors
- Andvari Associates
- Angel Oak Capital Advisors
- Aoris Investment Management — Aoris International Fund
- Appalaches Capital
- Ariel Investments
- Aristotle Funds
- Artisan Partners
- Askeladden Capital
- Asset Value Investors Ltd
- Atai Capital Management
- Atherean Asset Management
- Auxier Asset Management
- Avenue Investment Management
- Azvalor Asset Management
- BBH
- BNY Mellon
- Bahl & Gaynor
- Bailard
- Baird Equity Asset Management
- Barometer Capital Management
- Baron Funds
- Bell Asset Management
- Bengal Capital
- Berkshire Hathaway
- Bestinver
- Biglari Holdings
- Bilbel Capital
- Biondo Investment Advisors
- Bireme Capital
- Bison Interests
- BlackRock
- Blue Tower Asset Management
- Brandes Investment Partners
- Brasada Capital
- Bretton Fund
- Brighton Jones
- Bristlemoon Capital
- Broadleaf Partners
- Brookfield Asset Management
- Brown Advisory — Large-Cap Growth
- Brown Advisory — Mid-Cap Growth
- Broyhill Asset Management
- Brummer & Partners
- Burke Wealth Management
- ByteTree
- Cambiar Investors
- Cantor Fitzgerald Asset Management
- Carillon Eagle — Mid Cap Growth Fund
- Carillon Eagle — Small Cap Growth Fund
- Carrington Wealth Management
- Castlebay Investment Partners
- Cedar Creek Partners
- Cedar Grove Capital Management
- Chautauqua Capital Management
- Chenavari Investment Managers
- Chevy Chase Trust
- Chilton Capital Management
- Choice Equities
- City Different Investments
- Claret Asset Management
- ClearBridge Investments
- Compound Everyday Capital
- Comus Investment
- Conestoga Capital Advisors
- Confluence Investment Management
- Cooper Investors
- CrossingBridge Advisors
- Crossroads Capital, LLC
- Crypto Native Capital
- Curreen Capital
- Davenport Asset Management
- Davis Advisors Global ADR
- Davis Advisors Large Cap Value
- Davis Opportunity Fund
- Davis Real Estate Fund
- Diamond Hill — Large Cap Fund
- Diamond Hill — Small Cap Fund
- Diranko Capital
- Distillate Capital
- Dodge & Cox Stock Fund
- Donville Kent Asset Management Inc.
- DoubleLine
- Downing
- East 72
- East Capital
- Easterly Asset Management
- EdgePoint Wealth Management
- Elm Ridge Management
- Emerald Wealth Partners
- Emeth Value Capital
- Equity Management Associates
- Evolve Private Wealth
- FCL Capital
- FPA Crescent Fund
- Fairfax Financial Holdings
- Fairlight Capital
- Fairtree Asset Management
- Fawkes Capital Management
- Fenimore Asset Management
- Fiduciary Management
- Fiera Capital
- Financial Synergies Wealth Advisors
- First Eagle Investments
- Focus Capital Management
- Forager Funds Management
- Frank Capital Partners
- Fred Alger Management, LLC
- GCQ Funds Management
- GDS Investments
- GROW Funds
- Gabelli Funds
- Generation Investment Management
- Giverny Capital
- Glass Lake Wealth Management
- Glenmede Investment Management
- GoodHaven Capital Management
- Grandeur Peak Global Advisors
- GreenWood Investors
- Greenhaven Road Capital
- GreensKeeper Asset Management
- Greenwood Gearhart
- Gresham House
- Gresham House Strategic Equity Capital
- Grey Owl Capital Management
- Greystone Capital
- Guinness Global Investors
- HORAN Wealth
- Halvio Capital
- Harding Loevner
- Hardman Johnston
- Harry Qelm Baabsman
- Hayden Capital
- Heartland Advisors
- Hennessy Funds
- Heptagon Capital Future Trends Equity Fund
- Heptagon Capital Kettle Hill US L/S Equity Fund
- Highwood Value Partners
- Hinde Group
- Hoisington Investment Management
- Holland Advisors
- Hood River Capital Management
- Horizon Kinetics
- Horos Asset Management
- Hosking Partners
- Hotchkis & Wiley
- Impax Asset Management
- Infuse Asset Management
- Integrity Asset Management — Micro Cap Value Equity
- Intrepid Capital
- Invenomic Capital Management
- Invesco — Discovery Fund
- Ironvine Capital Partners
- Ithaka Group — US Growth Strategy
- JB Global Capital
- JM Finn
- Jacob Asset Management
- Janus Henderson Investors
- Jemekk Capital Management
- Jenga Investment Partners
- Kathmandu Capital
- Kaydan Wealth Management
- Kennedy Capital Management
- Kernow Asset Management
- Kingdom Capital Advisors
- LVS Advisory
- Lakehouse Capital Global Growth Fund
- Lakehouse Capital Small Companies Fund
- Langdon Equity Partners
- Lansing Street Advisors
- Latitude Investment Management
- Laughing Water Capital
- Lazard Asset Management
- Leonard Rickey Investment Advisors
- Lindsell Train Limited
- Long Cast Advisers
- Loomis Sayles — Global Growth Fund
- Lyrical Asset Management
- MJG Capital
- Madison Investments — Small Cap Fund
- Mairs & Power
- Manole Capital Management
- Mar Vista Investment Partners
- Maran Capital Management
- Markel Group
- Marram Investment Management
- Massif Capital
- Matrix Asset Advisors
- Matthews Asia
- Mayar Capital
- McIntyre Partnerships
- Meridian Growth Fund
- Meridian Hedged Equity Fund
- Merion Road Capital
- Miller Value Partners
- Miller/Howard Investments
- Minot Light Capital Partners
- Minotaur Capital
- Moerus Capital Management
- Mondrian Investment Partners
- Moneta Group
- Montaka Global Investments
- Moon Capital Management
- Mott Capital Management
- Mountain Vista Wealth Management
- Muhlenkamp & Company
- Munro Partners
- Myrmikan Capital, LLC
- NS Partners
- Nelnet
- Newport Capital Group
- Next Century Growth Investors
- Night Watch Investment Management
- Nightview Capital
- Nixon Capital
- North Sky Capital
- O'Keefe Stevens Advisory
- Oak Associates Funds
- Oak Ridge Investments
- Oakmark Funds
- Oceana Investimentos
- Oldfield Partners
- Open Insights Capital
- Ophir Asset Management
- Optimist Fund
- Orange Investment Advisors
- Oujo Wealth Strategies
- Overseas Asset Management Asian Recovery Fund
- Overseas Asset Management European Value Fund
- PM Capital
- Packer & Co
- Palm Harbour Capital
- Palm Valley Capital
- Parnassus Investments
- Patient Capital Management
- Peak Asset Management
- Peapack Private
- Pendelhaven Asset Management B.V.
- PenderFund Capital Management Ltd.
- Penn Davis McFarland
- Pershing Square Holdings
- Pittenger & Anderson
- Plural Investing
- Polaris Capital Management
- Polen Capital 5Perspectives Growth Opportunities
- Polen Capital U.S. Opportunistic High Yield
- Praetorian Capital
- Private Capital Management
- ProChain Capital
- Protean Funds
- Pzena Investment Management
- QV Investors
- QuantStreet Capital
- Quercus Fund
- RD Capital Partners
- REQ Capital
- RF Capital Management
- RGA Investment Advisors
- ROCKLINC Investment Partners
- Rathbones
- Regal Partners Global Investments
- Regency Wealth Management
- Renaissance Investment Management — Large Cap Growth
- Rewey Asset Management
- Right Tail Capital
- RiverPark Funds
- Riverwater Partners
- Robinson Capital Management
- Rowan Street Capital
- Royce Investment Partners
- Rozendal Partners
- SRK Capital
- Saga Partners
- SaltLight Capital
- Sandon Capital — Activist Fund
- Sands Capital — Select Growth Fund
- Sawgrass Asset Management
- Seafarer Capital Partners
- Sequoia Fund
- Seven Corners Capital
- Sharp Capital
- Shelton Capital Management
- Sigil
- Signia Capital Management
- Skybound Wealth Management
- Smead Capital Management
- Social Capital
- Sorfis Investments
- Sound Shore Management
- Southeastern Asset Management
- SouthernSun Asset Management
- Sparrow Wealth Management
- Spheria — Global Smaller Companies Fund
- Spyglass Capital Management
- Starvine Capital
- Stenham Asset Management
- Stewart Asset Management
- Steyn Capital
- Stone Ridge Asset Management
- Stone Sentinel Capital
- Stonehearth Capital Management
- Summers Value Partners
- Sustainable Growth Advisers
- TEAM Asset Management
- TIFF Investment Management
- Tall Oak Capital Advisors
- Tapasya Investment
- The London Company
- Third Avenue Management
- Third Point
- TimesSquare Capital Management
- Touchstone — Balanced Fund
- Troy Asset Management
- Tweedy, Browne
- Unconventional Value
- Upslope Capital Management
- VH Standard Asset Management
- Value Line Funds
- Victory Capital — Sycamore Mid Cap Value Equity
- Vision Capital Fund
- Vltava Fund
- Voss Capital
- Voya Investment Management — MI Dynamic Small Cap Fund
- Vulcan Value Partners
- Warden Capital
- Wasatch Global Investors — Micro Cap Fund
- Wasatch Global Investors — Small Cap Growth Strategy
- Wealthspire Advisors
- Wedgewood Partners
- Weitz Investment Management
- Wellington Management — Quarterly Market Review
- WestEnd Capital Management
- Westfield Capital Management
- Westwood — Quality SmallCap Fund
- White Brook Capital
- White Falcon Capital Management
- YCG Investments
Sectors
Ordered by how often our editor reaches for them.
