When the liquidity does not add up
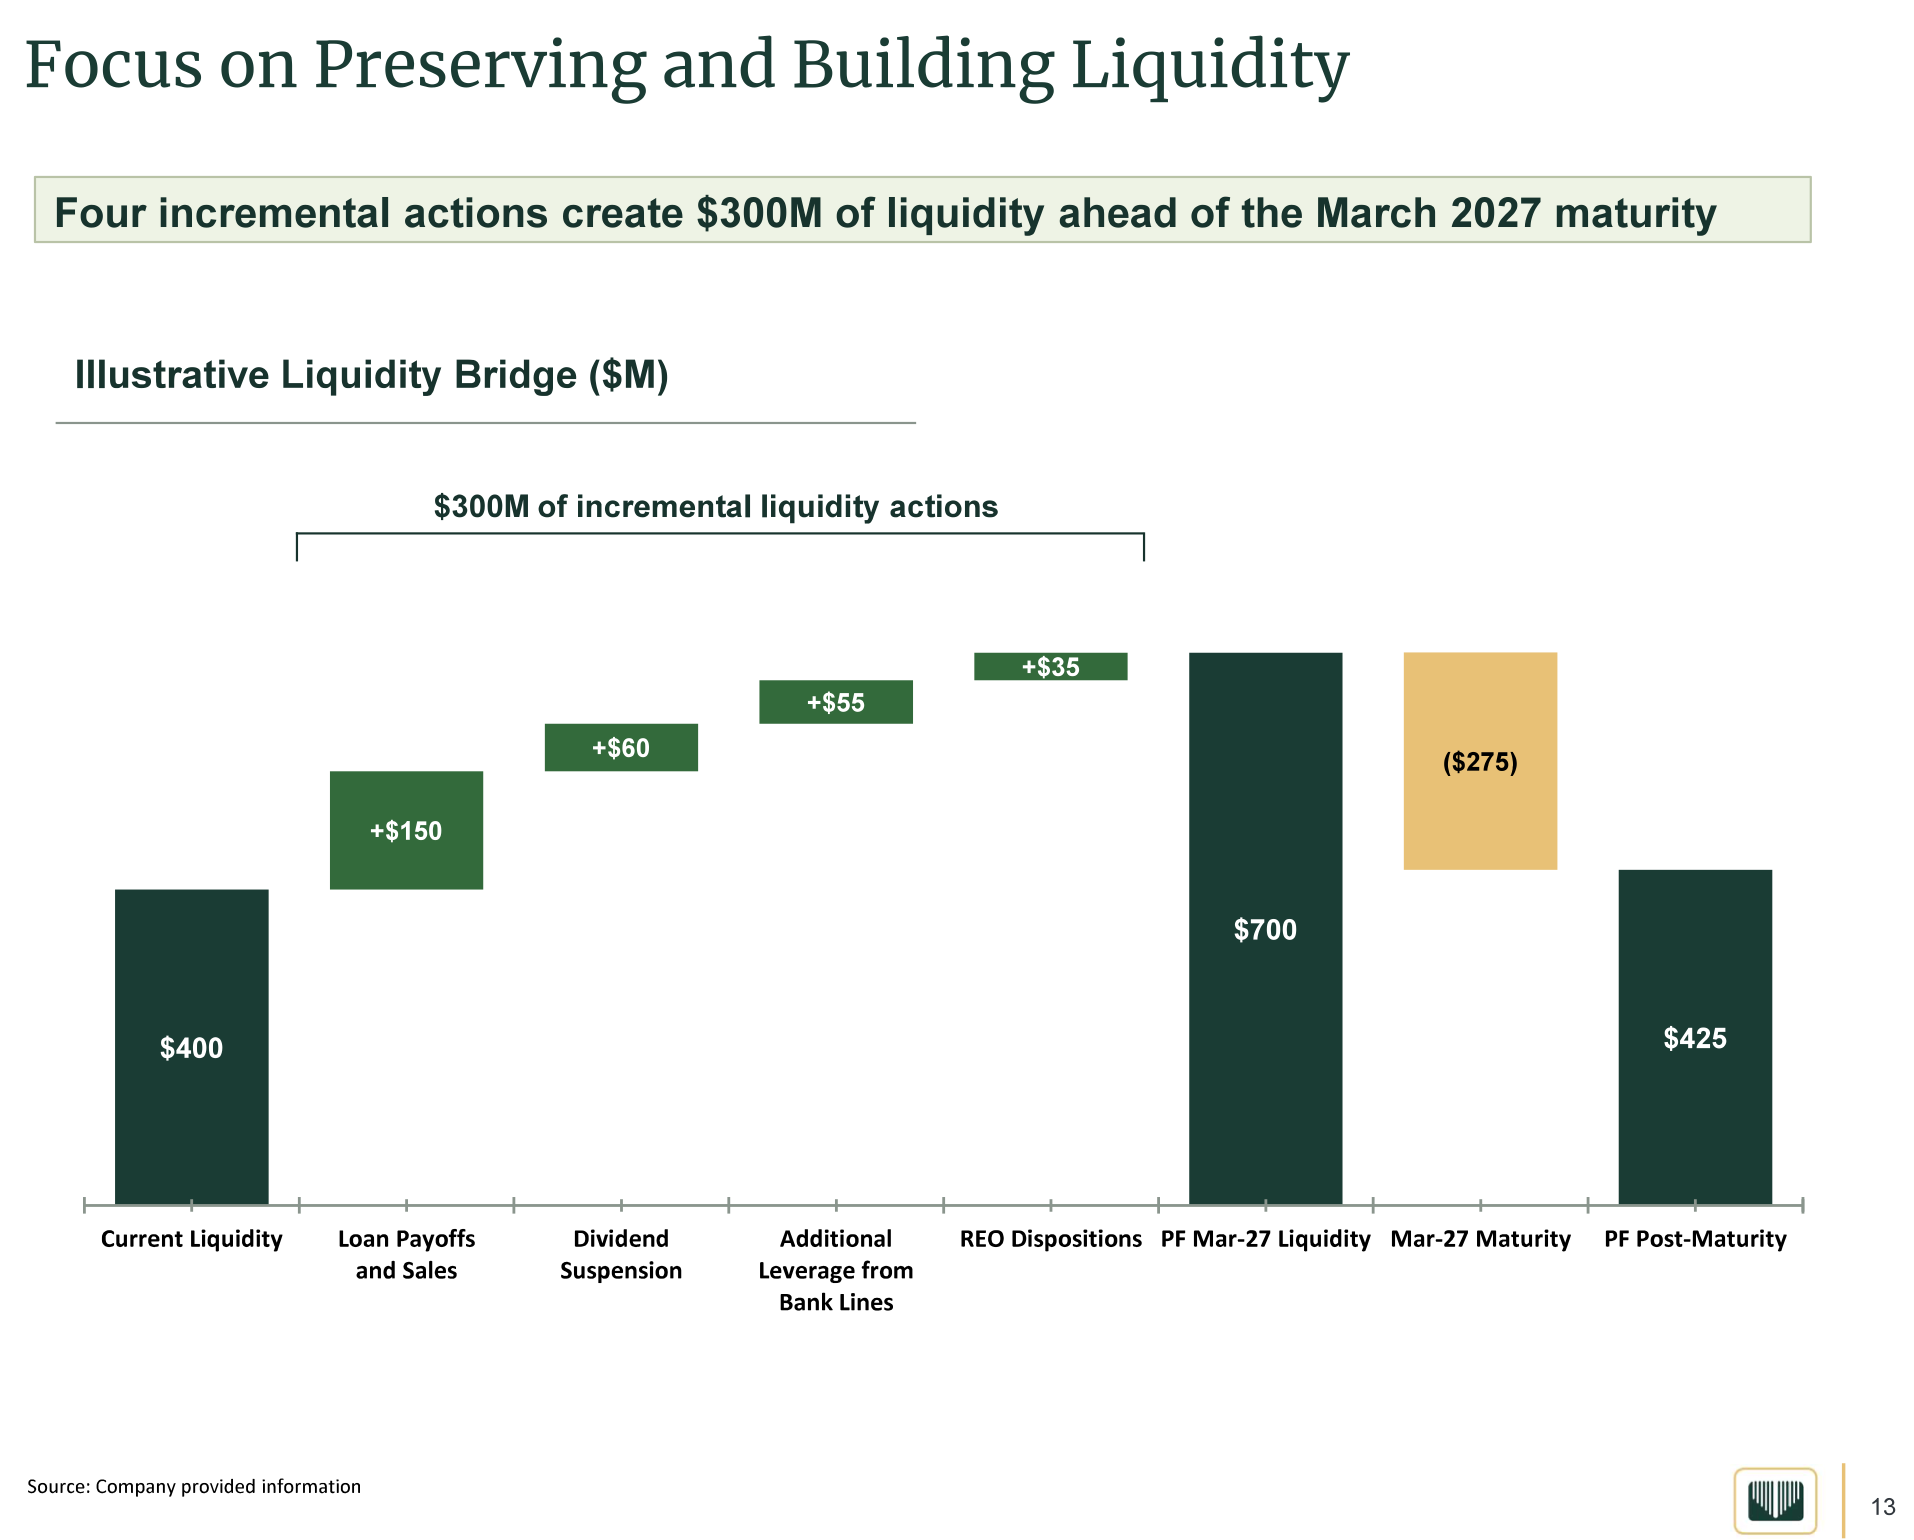
Arbor Realty Trust’s dividend suspension is presented as creating $60 million of liquidity, raising questions about its ability to meet 2027 debt maturities.
Arbor Realty Trust’s dividend suspension is presented as creating $60 million of liquidity, raising questions about its ability to meet 2027 debt maturities.
If you liked $FTAI at $209, you’re going to love it $186… https://t.co/J40mboCyG8
$ACMR https://t.co/gzKlQTn1pF
@SovietInvestor ok well $RYN sells for $1,800 per acre...
A fun trade I've had in is arbing convertible preferreds. Long $PCGPRX short $PCG, long $QXOPRB short $QXO. Trading below the convertible price while pocketing a nice dividend with cheap financing.
$BMRN up premarket on settlement agreement. I continue to like/own. https://t.co/a6WZ9ksaeH
FTAI’s Aerospace Products margin rebounded to 31% as CFM56 module output rose, while Power deposits and contracted deliveries fund its 2027…
Life360 has fallen 60% despite 40% revenue growth, 100 million monthly users and profitability, as its family-safety subscriptions and…
American Tower could gain $1.13 to $3.54 in AFFO per share if Starlink accesses 80,000 U.S. cell sites and becomes a fourth major tenant.
 Dane Bowler 4 clicks
Chevron’s Q3 revenue rose 35% to $65.2 billion and EBITDA 75% to $20.2 billion, while production trailed guidance and refining margins…
AstraZeneca reported $16.2 billion Q3 revenue, up 7%, as oncology grew 17% and Farxiga fell 25% after US generics.
Sanofi raised FY26 guidance after Q3 sales grew 14.3% at constant currency, led by 34.8% Dupixent growth; vaccines declined 6.6%.
Bloom may have reopened imports of scandium-containing components from China to the United States, according to new trade data.

Markel spent $315 million repurchasing shares in Q3 as Thrive agreed to buy ADT for $7.6 billion and Hasbro cited rising adult toy demand.
Verisk Analytics’ 40 petabytes of proprietary insurance data and regulatory infrastructure shield its underwriting business from generative…
Tango Therapeutics reported an 82% response rate and 88% nine-month PFS for vopimetostat plus RASONQUE in RAS-mutant pancreatic cancer,…
 Terry Chrisomalis 2 clicks
 PSN · long
Parsons generates roughly half of its $6.4 billion revenue from Federal Solutions, serving defense and intelligence customers.
Regeneron’s Q3 revenue rose 36% to $5.1 billion, driven by a 68% jump in Sanofi collaboration revenue, while operating income doubled to…
Applied Materials posted 51% growth while trading near 23 times forward earnings; memory spending and fab construction support orders, but…
 Capital Minded 1 click
Marvell’s reported Lumentum bid would combine DSPs, lasers and optical modules, but $4 billion of cash and $5 billion of debt point to a…
Smart Fit, Brazil’s SMFT3, is expanding its low-cost gym network across Latin America, with corporate-wellness platform TotalPass adding to…
SoFi’s stock case hinges on interest rates, tangible book value and private-credit loan sales after its $1.5 billion equity offering.
Miami International Holdings posted 20% Q3 revenue growth and 47% EBITDA growth as options volumes, market-share gains and operating…
 Seeking Profits 4 clicks
Intel’s Q3 2026 datacenter CPU shortage reflects wafer-start planning failures, not substrate constraints, after demand shifted from client…
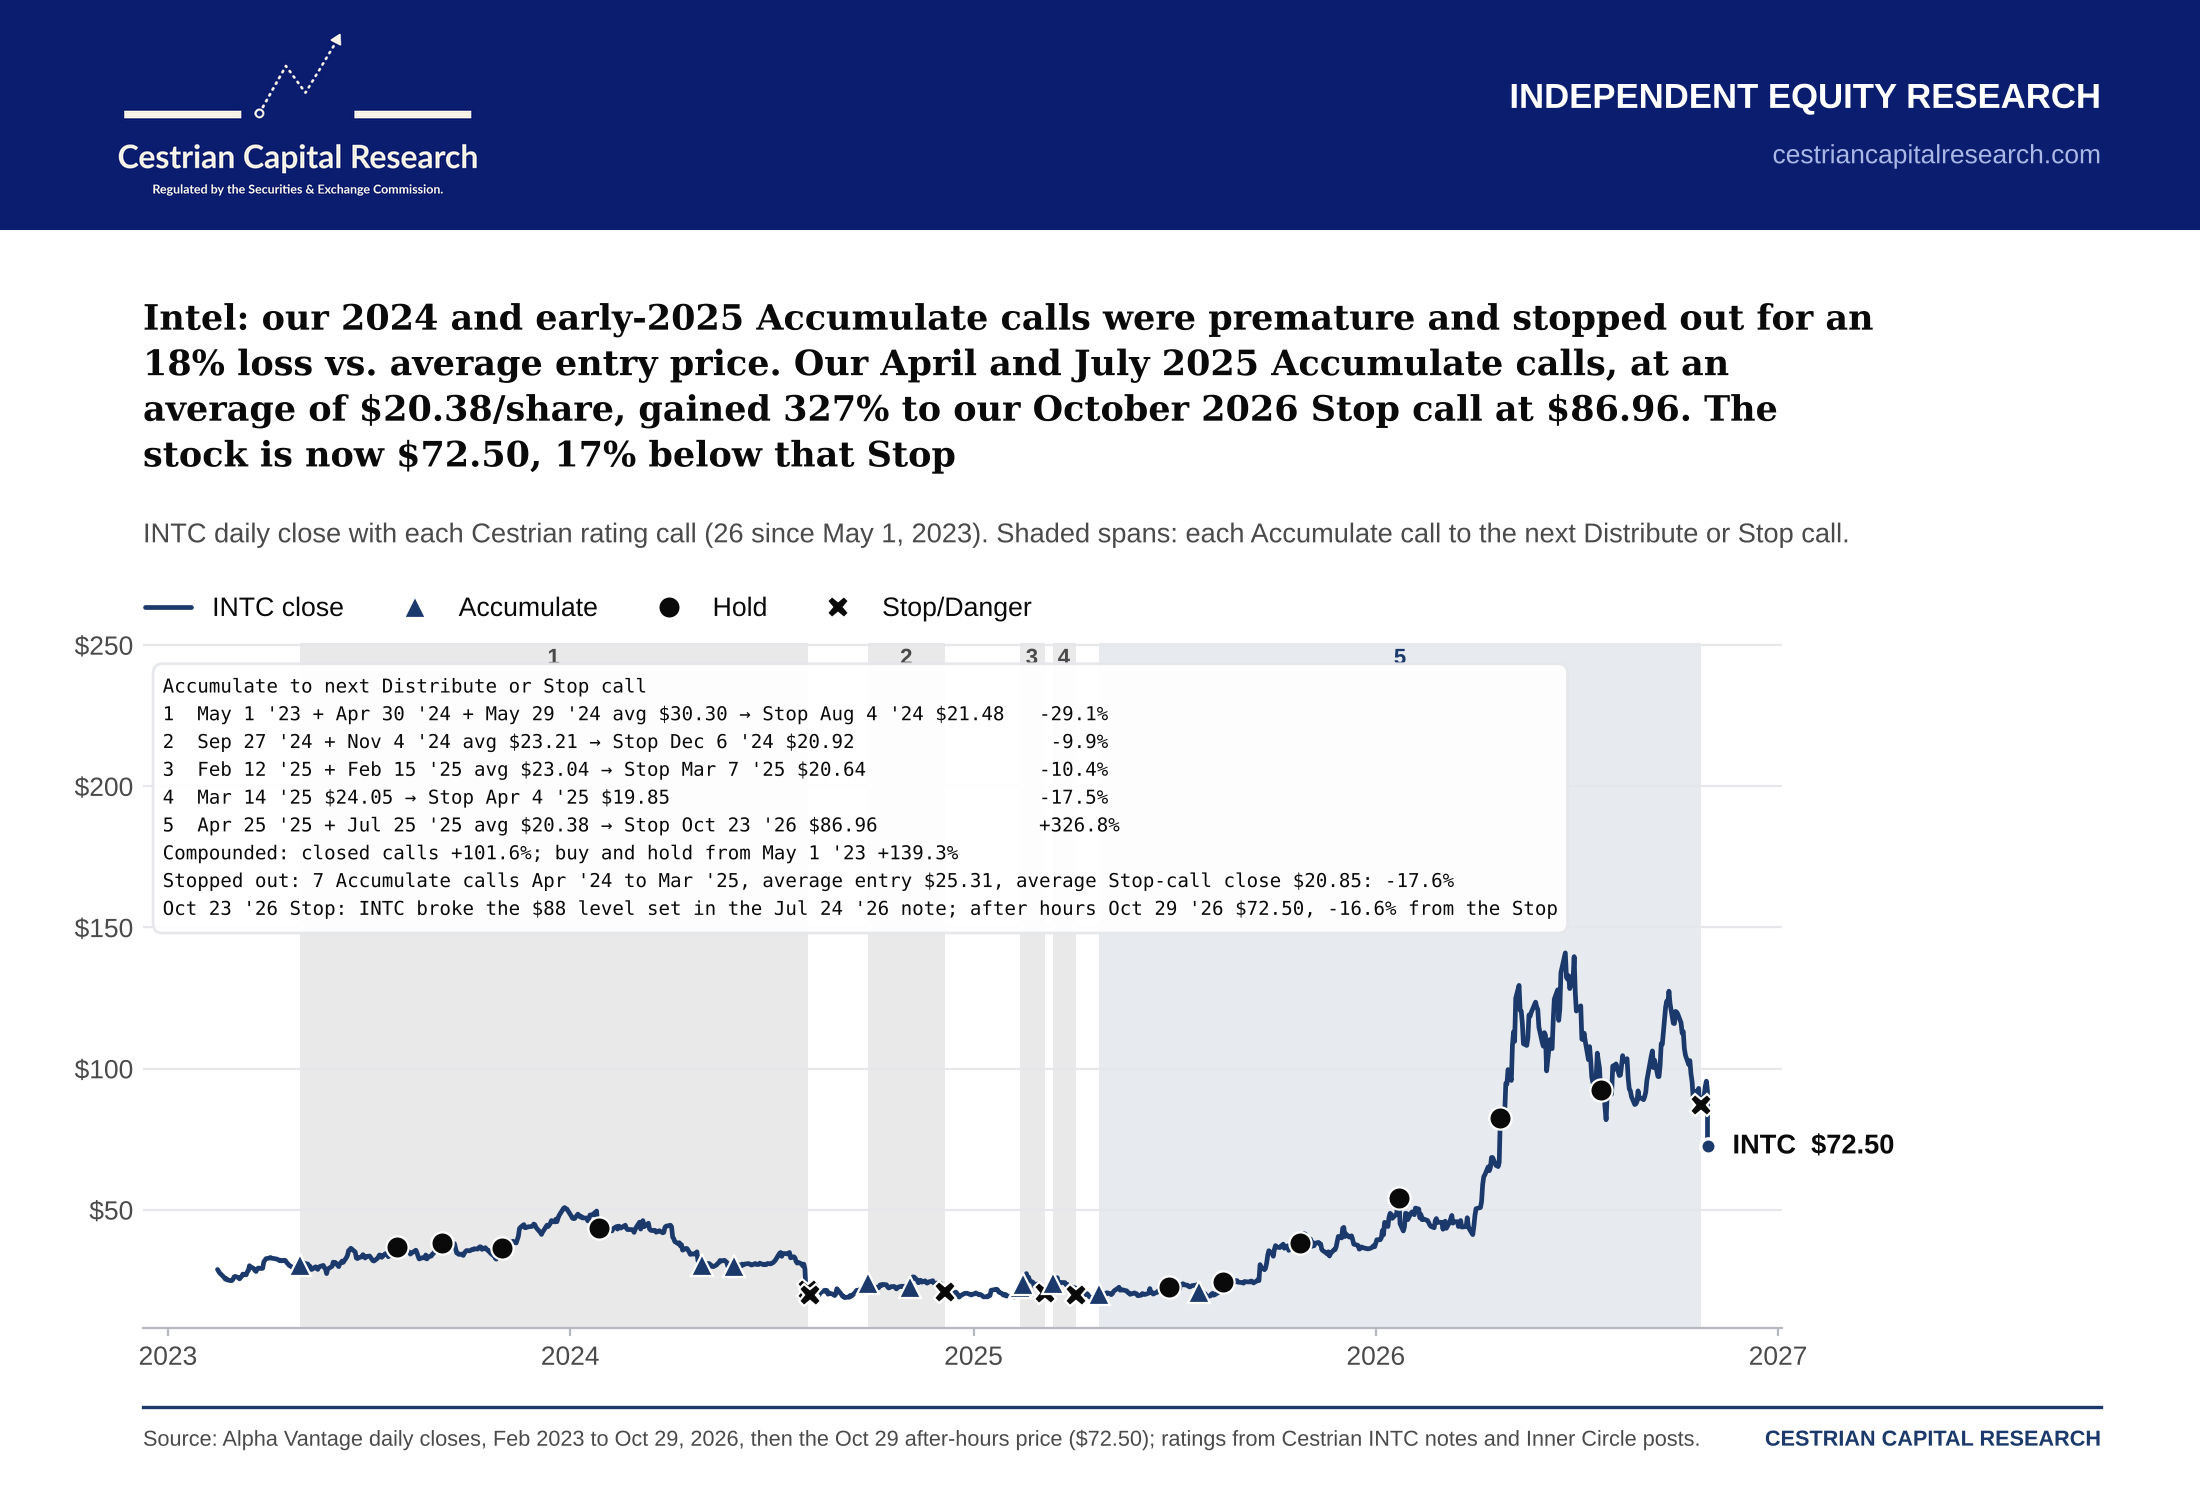
Intel's Q3 revenue rose 21% to $16.5 billion, led by 78% data-center and AI growth, but Q4 guidance of $15.5 billion trailed consensus.
Alphabet, Amazon and Intel face market pressure as the big three cloud giants reaffirm AI spending plans.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 Cypriot Invests Dane Bowler
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Fountainhead
 Geneva Investor
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Rubicon Associates
 Ryan Canady
 Sam Mancini Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey
 Value Capital Research
 Vishal Jadaun
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.