WD #360: New Trade, Recent Market Action, Brazil/Inter Update
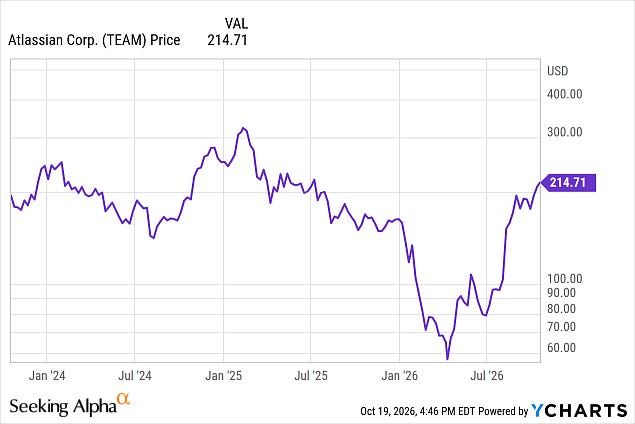
Atlassian is sold after a 130% gain, while iShares MSCI Indonesia ETF is added following the market plunge; the update also assesses the AI-stock selloff and CoreWeave’s collapse.
Atlassian is sold after a 130% gain, while iShares MSCI Indonesia ETF is added following the market plunge; the update also assesses the AI-stock selloff and CoreWeave’s collapse.
$AAOI is... finally... done... With their $600m ATM program, turns out it's ~$105.36 average. I do think AOI outperforms $LITE, as long as they stop filing these ATM programs. Just due to their sheer magnitude of ramp with $471m/month transceiver revenue + 400K/month ELSFP coming up.
When rates jerk higher and everything rate-sensitive gets smoked together, that’s when you want to swoop in on the names where you actually have conviction. Rates spike. $FTAI, $CORZ, $CIFR, $OWL all gap down 5%. Did anything change in the catalyst? No? Buy the dislocation.
Maybe I'm being too simplistic, but it seems like it's going to be hard for the market to have a sustained move higher if $GS doesn't start acting better.
Should probably look at $FSLR < $175… Just saying.
Why is $SPCX up 12% in the last two days https://t.co/UNaneqcrfX
$MELI - Excellent Brazil outcome. Stock was at a technical bottom of its consolidation wedge. Business results will begin inflecting as the credit portfolio growth slows due to it’s now to size. Very bullish: Economic Backdrop, Business Results forward, and technicals
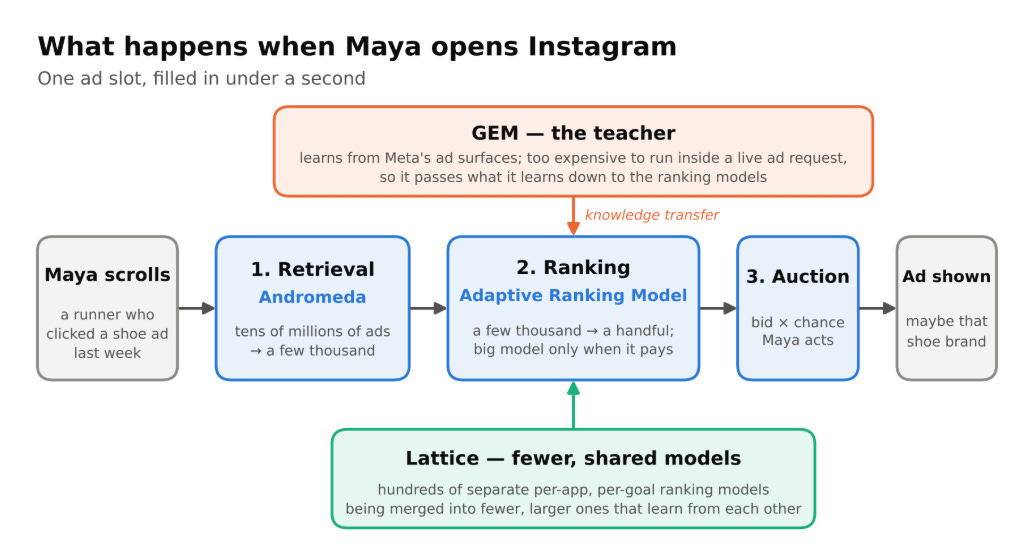
Meta’s GEM trains smaller ad-ranking models across its platforms, with Kunlun showing performance scaling predictably as compute rises.
SaaS companies including Salesforce, ServiceNow, CrowdStrike, Synopsys and Veeva are ranked by agentic AI progress, from pilots to…
Lennar’s land-bank costs pressure homebuilding margins, while Flowers Foods weighs a Tastykake sale after falling branded-bread share,…
 Michael Fitzsimmons 4 clicks
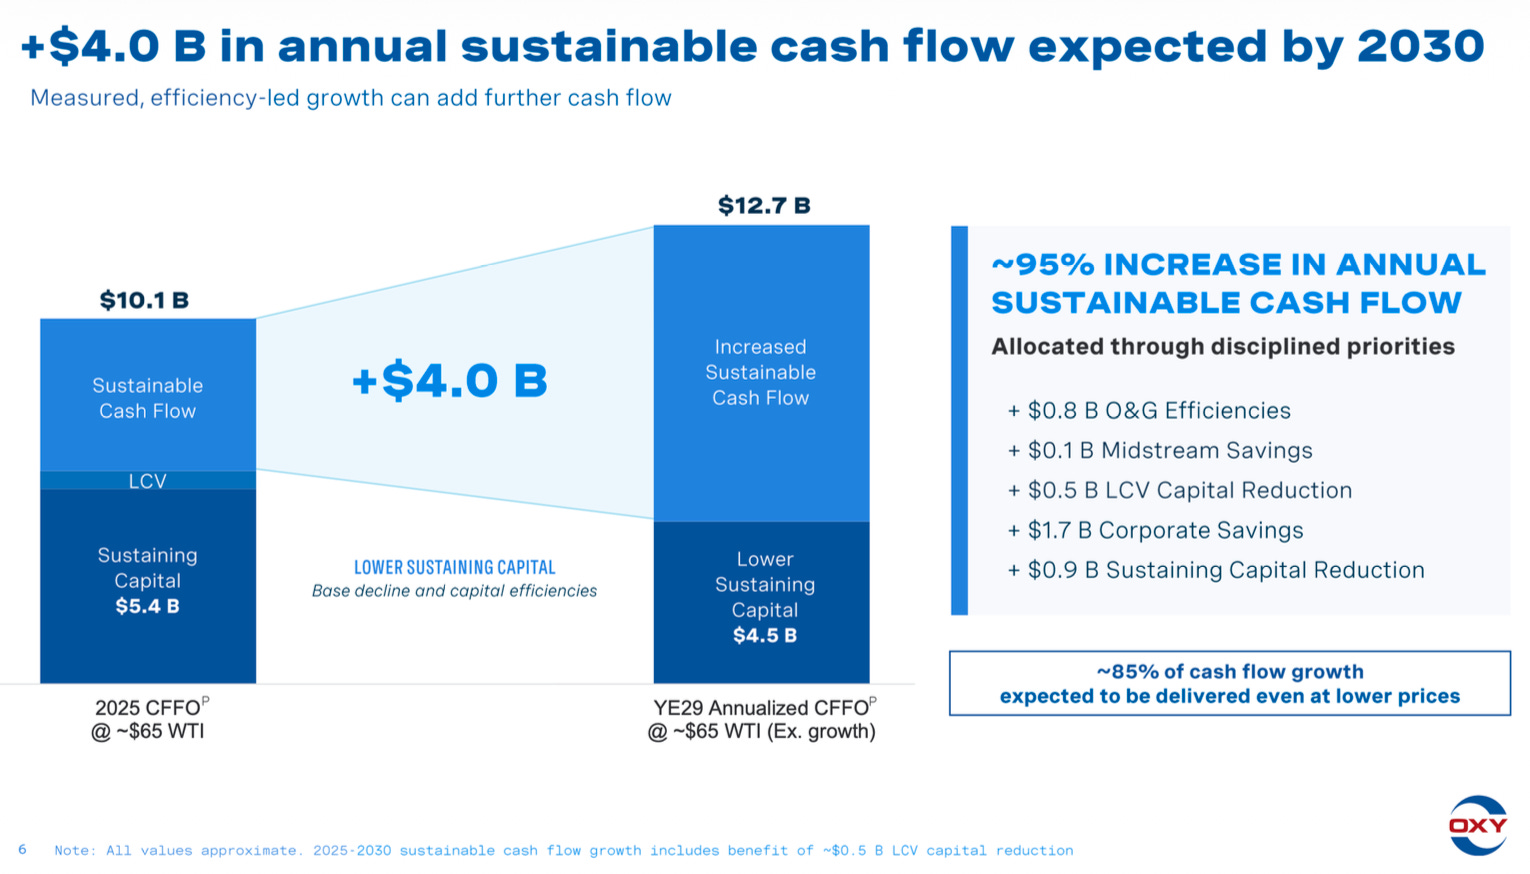
Occidental Petroleum’s debt should fall further after Q3 oil prices averaged $85 per barrel WTI and $91 Brent.
Zscaler CEO Jay Chaudhry and CFO Kevin Rubin discuss the cybersecurity company’s growth prospects and valuation.
Apple’s HomeView strategy ties Siri, privacy and smart-home control to consumer trust in its vision for the home.
Digital Realty paid $120 million for Atlanta-area parcels including a former Army dump with buried carcinogens and military ordnance.
Wells Fargo’s Q3 EPS beat and $12.5 billion net interest income failed to move shares, while WFC.PZ preferreds yield 7.10%.
 Jeremy LaKosh 7 clicks
Semtech raised Q3 guidance and targets $3.2 billion of fiscal 2030 revenue, excluding upside from its AI data-center optical and copper…
DigitalOcean’s CEO says the cloud company will not take on extraordinary leverage to fund its AI push.
Optical-component vendor call covers 800G and 1.6T demand, AI cluster optical density, market share, pricing and 2027 growth for Coherent,…
PayPal’s 10.3x forward earnings multiple and more than $6 billion in free cash flow frame a turnaround driven by cost cuts, Venmo and BNPL…
 JR Research 12 clicks
Steve Eisman examines AI data-center debt, CoreWeave's tech correction and agentic AI's effect on banks as earnings season begins.
RELX’s 13-petabyte fraud and identity data moat supports its high-margin Risk segment as its valuation falls to roughly half its peak P/E.
 LA Capital 9 clicks
OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
GE Vernova’s 116 GW gas-turbine backlog and $5 billion in early-2026 data-center orders target AI-driven electricity demand, though its…
 Todd Feldman 4 clicks
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.