Thursday, October 15, 2026

Back to today

Is The Market Turning The Page?

CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.

From X

@StableBread

Fajasy on X

The Department of Energy conditionally committed $17.5B in loans in June 2026 for long-lead equipment for up to 10 AP1000 reactors (Westinghouse’s large U.S. design), and only “a limited number of heavy engineering plants” can make the components, per World Nuclear News. BWX Technologies $BWXT bought Precision Components Group (PCG) in July 2026 to get a U.S. foothold. PCG makes heat exchangers and other heavy components at plants in York, Pennsylvania, and Florence, New Jersey, but it can’t make the largest parts, like an AP1000 reactor pressure vessel, CEO Rex Geveden said on the Q2 call. So $BWXT is weighing New Jersey, Indiana, and one other location for a new U.S. large-component plant, and Geveden expects “a final investment decision in the coming months.” He also expected at least one new-build equipment order by the end of 2026, from the three additional small modular reactors (SMRs) planned at Darlington in Ontario, the AP1000 projects, or BWRX-300 SMR projects in the U.S. John MacQuarrie, president of Commercial Operations, widened that window at $BWXT’s Investor Day on September 29, 2026, saying awards should start “either later this year or early in 2027.” $BWXT’s Investor Day targets call for high-teens annual revenue growth in the commercial segment through 2030, with adjusted EBITDA margins rising to the high teens from 13% in 2026. Reading “high teens” as 16-19%, commercial revenue would grow from ~$1.1B in 2026 to ~$2.0-2.2B by 2030, and adjusted EBITDA from ~$140M to ~$320-420M. That would make commercial about a third of $BWXT’s adjusted EBITDA, up from about a fifth.
@convequity 2 clicks

Convequity on X

A laser that only one company can supply will not scale to the volumes AI needs. That is the main reason $LITE is a less attractive investment to us than it was a few quarters ago. Our post on Lumentum got more attention than we expected, so we want to set out the argument in plain terms, including what we think about microLED. We did not say microLED will certainly happen. 1. The part in question is Lumentum's ultra-high-power external laser source. In co-packaged optics, the optical parts sit inside the chip package. The laser sits outside, in its own module, and its light is carried into the package by fibre. That outside module is the external laser source. Ultra-high-power means one laser produces enough light to feed many optical channels at once. 2. If only one vendor can make that laser, it has little chance of reaching meaningful volume. One supplier cannot carry a part the whole industry needs. So the industry has to find other paths around that bottleneck. 3. The first likely path is micro-VCSELs. A VCSEL is a vertical-cavity surface-emitting laser: a tiny laser that sends light out of the top of the chip rather than out of its edge. They are made many at a time on a wafer, and each one is low power. A micro-VCSEL is a very small version. Many small lasers do the job of one very powerful one. 4. The second path is a less powerful laser packed inside the NPO package. CW stands for continuous wave: the laser emits a steady beam, and a separate part, the modulator, switches that light on and off to carry data. NPO is near-packaged optics: the optical engine sits on the board right next to the chip, rather than inside the chip package or in a pluggable module at the front of the switch. In this path the CW laser is still fairly high power, but not ultra-high power, and it sits inside the optics package instead of in a separate external module. 5. The third path is microLED. A microLED is a very small light-emitting diode, the same kind of device as in a display, not a laser. Each one is switched directly to carry data, and many of them run in parallel over short distances. 6. On microLED, the consensus on X is that it will not work for AI interconnects. We are not saying it will certainly happen. It is one of several alternatives. But there is good research work on it, and it has a chance. Most of the criticism we see is aimed at one architecture. The research we rate uses microLEDs in a different architecture, and the criticism does not address it. 7. Lumentum will still grow. But compared with the previous few quarters it is a less attractive investment, because its ultra-high-power laser is the part the industry has to find a way around. We trimmed most of our Lumentum position earlier this year, around when the share price began to flatten.
@StableBread 1 click

Fajasy on X

Neither of the two commercial prospects BWX Technologies $BWXT has named for its BANR microreactor is a data center. 1) Prodigy Clean Energy, a Montreal-based developer of factory-built nuclear plants: Two BANRs for a transportable pilot plant in Belledune, New Brunswick, built mainly at $BWXT’s Ontario plants and running in the early 2030s. New Brunswick’s government signed a letter of intent (LOI) to buy the power. $BWXT and Prodigy are still negotiating a definitive agreement, and the release provides no dollar value. 2) Tata Chemicals Soda Ash: A Wyoming soda ash producer that signed an LOI to explore deploying up to eight BANRs. $BWXT also markets BANR to data centers. However, I found no data center contract, customer, LOI, or revenue in any $BWXT press release from January 2025 through October 2026, in the FY2025 10-K, or in the 2026 10-Qs. $BWXT’s own mentions stop at a product page saying BANR can provide “clean electricity for municipalities, data centers and campuses,” and slides 11 and 25 from its Investor Day on September 29, 2026, which list “AI/data center demand” as a driver of nuclear demand in general. I didn’t hear the phrase “data center” mentioned once during Investor Day, and slide 49 lists data centers in the third phase of $BWXT’s microreactor plan. CEO Rex Geveden said at Investor Day that “the incremental demand from AI right now is 60 GW” and “winning at AI means winning at power, and winning at power probably means having a nuclear solution.” If he’s right, $BWXT benefits by supplying components, fuel, and services to more reactors, not by selling microreactors to data centers. Advanced Reactor Design and Engineering, the product line that includes Project Pele (its prototype microreactor for the Pentagon) and $BWXT’s other microreactor programs, brought in $203.8M in 2024 and $147.1M in 2025, then $52.6M in H1 2026, down from $69.8M a year earlier. At 3.0% of $BWXT’s $1,761.8M of H1 2026 revenue, microreactors are still a small, early business.
@calvinblissett 3 clicks

Calvin Blissett on X

$CHRD: 6.5x FCF, Good CEO, buying back lots of stock, low-cost pure play EP. 8% FCF yield at $60 WTI. No meaningful leverage CHRD trades at ~$142, market cap ~$7.74B, enterprise value ~$8.63B. Dividend yield ~3.7% ($5.20 annual base). Buyback/total shareholder yield is higher: policy returns ≥75% of adjusted free cash flow (mostly buybacks after the base dividend) at current low leverage (<0.5x). On 2026 guidance of ~$1.3B Adj. FCF, this implies a potential total cash return yield in the low-to-mid teens. Valuation is low: ~9.5x TTM P/E, ~7.6x forward P/E, EV/EBITDA ~3.2-3.6x, P/FCF ~6.5x. Analyst consensus PT ~$166-174 (~20%+ upside); highs to $193. Marcellus non-op sale (to POSCO, expected Q4 2026 close) provides ~$550M gross proceeds, sharpening pure-play Williston focus, boosting cash/flexibility for returns or balance-sheet strength, and removing a non-core asset. Reasons for future growth: Flat-to-low absolute oil volumes (maintenance program ~161 MBopd oil) but rising per-share metrics via efficiency and buybacks. Longer laterals (majority of program, including 4-mile) cut costs/breakevens and improve recovery; base production enhancements and lower declines support volumes with less capital. Pure-play focus post-sale plus disciplined consolidator role in the Bakken. Efficiency gains already drove material FCF improvements. LTM Owner’s Earnings (Buffett-style): Roughly Net Income + DD&A + other non-cash charges − maintenance CapEx (and normalized for WC/one-time items). For this E&P, nearly all CapEx is maintenance to offset natural declines, so Owner’s Earnings approximates free cash flow. TTM (to ~Jun 30, 2026): Operating cash flow ~$2.59B, CapEx ~$1.40B → FCF ~$1.19B. DD&A ~$1.54B; Net Income ~$841M. Company-reported adjusted FCF (preferred operational proxy) was strong in 1H26 (~$738M combined Q1+Q2) and has been running at an elevated rate. This is a rigorous, cash-based measure after the capital required to sustain the business. Expected next-12-months Owner’s Earnings: ~$1.3B adjusted free cash flow (company 2026 guidance, including derivatives, at $75 WTI / $3 HH for 2H). Why higher than LTM: stronger realized oil prices vs. prior periods, operational efficiencies (longer laterals, cost controls, base enhancements), volumes at/above high-end of prior guidance, and capital discipline (CapEx held ~$1.4B midpoint). The $550M Marcellus proceeds is one-time cash (not recurring earnings) that further supports returns and balance-sheet optionality. At ≥75% payout, this supports substantial shareholder distributions while maintaining a strong BS. Business simply: Pure-play Williston Basin (Bakken) E&P—largest operator there. Drills oil-focused horizontal wells, produces/sells crude, NGLs, and gas. High-quality inventory; shift to longer laterals improves economics. Management: Danny Brown (CEO; prior Oasis/Anadarko). Track record of efficiency, synergies, disciplined capital allocation, and per-share value creation. Capital allocation: Base dividend + aggressive buybacks under the 75%+ Adj. FCF framework (leverage-dependent). Share count reduced meaningfully; cumulative returns large relative to market cap. Maintenance production focus. Risks: Oil price sensitivity/volatility (primary driver), basin decline/inventory longevity, execution on laterals or M&A, regulatory factors in ND/MT, energy transition headwinds. Margin of safety & upside: Low leverage, high cash generation even at moderate oil prices ($60-70 WTI still supports solid FCF/returns), conservative CapEx, and efficiency gains provide protection. Upside from multiple expansion toward peers/history, continued buyback accretion to per-share metrics, operational outperformance, oil strength, and pure-play clarity. Consensus implies ~20%+ near-term upside; higher in stronger commodity scenarios. Attractive FCF yield + value profile in E&P. Figures based on company results/guidance, market data, and analyst notes as of early October 2026. Oil prices and execution remain key variables.

AppLovin Deep Dive

AppLovin rebuilt its ad model with AXON 2.0, lifting LTM revenue to about $7 billion and margins to 77% as Unity competition threatens…
Constellation: Stars Aligning?

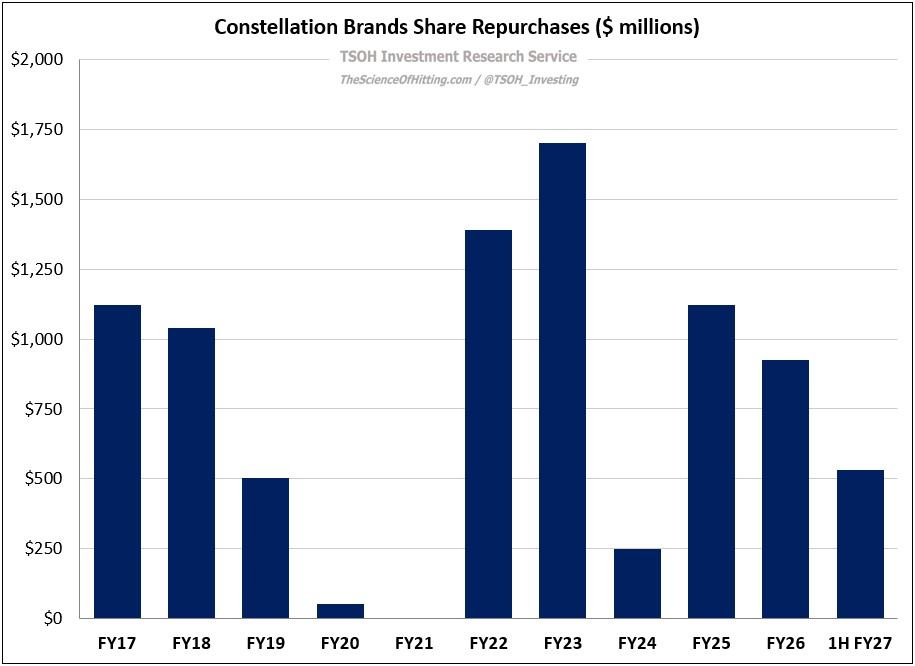
Constellation Brands trades near $127 at roughly 11x next-twelve-month EV/EBIT, with recent business results offsetting concerns over…
TSMC Q3 FY12/26 Earnings Review

TSMC reported excellent Q3 results, guided Q4 revenue growth higher and saw its shares slip despite strong AI-driven earnings momentum.
SPHR · long

Sphere Entertainment CO

Sphere Entertainment is shifting from construction and startup spending to a high-margin, cash-generative venue-operator model, with…
My 2028 numbers

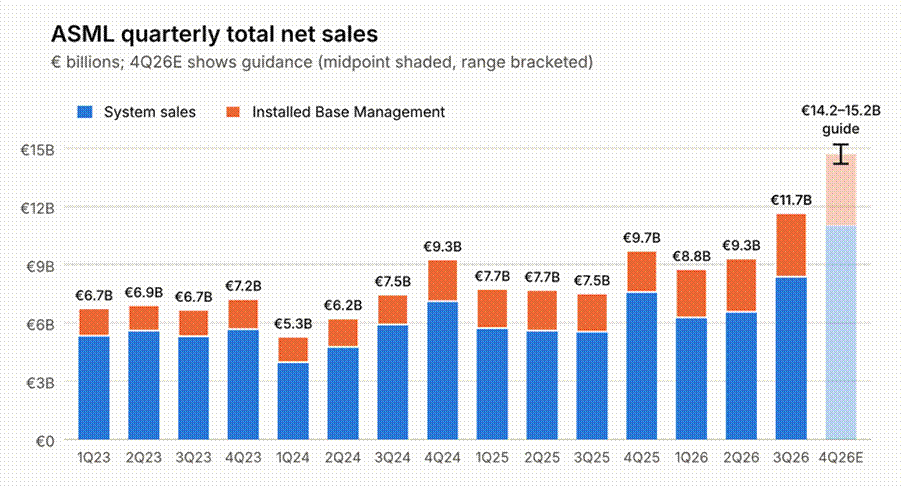
ASML’s €11.7 billion quarter benefited from €3.3 billion in installed-base sales and operating leverage, while the MATCH Act threatens…
Publications we follow

Every publication on this site, hand-picked.

129 publications

Newsletters 107

X accounts we follow

Every account on this site, hand-picked.

88 accounts

Investor letters we follow

189 firms

Sectors

Ordered by how often our editor reaches for them.