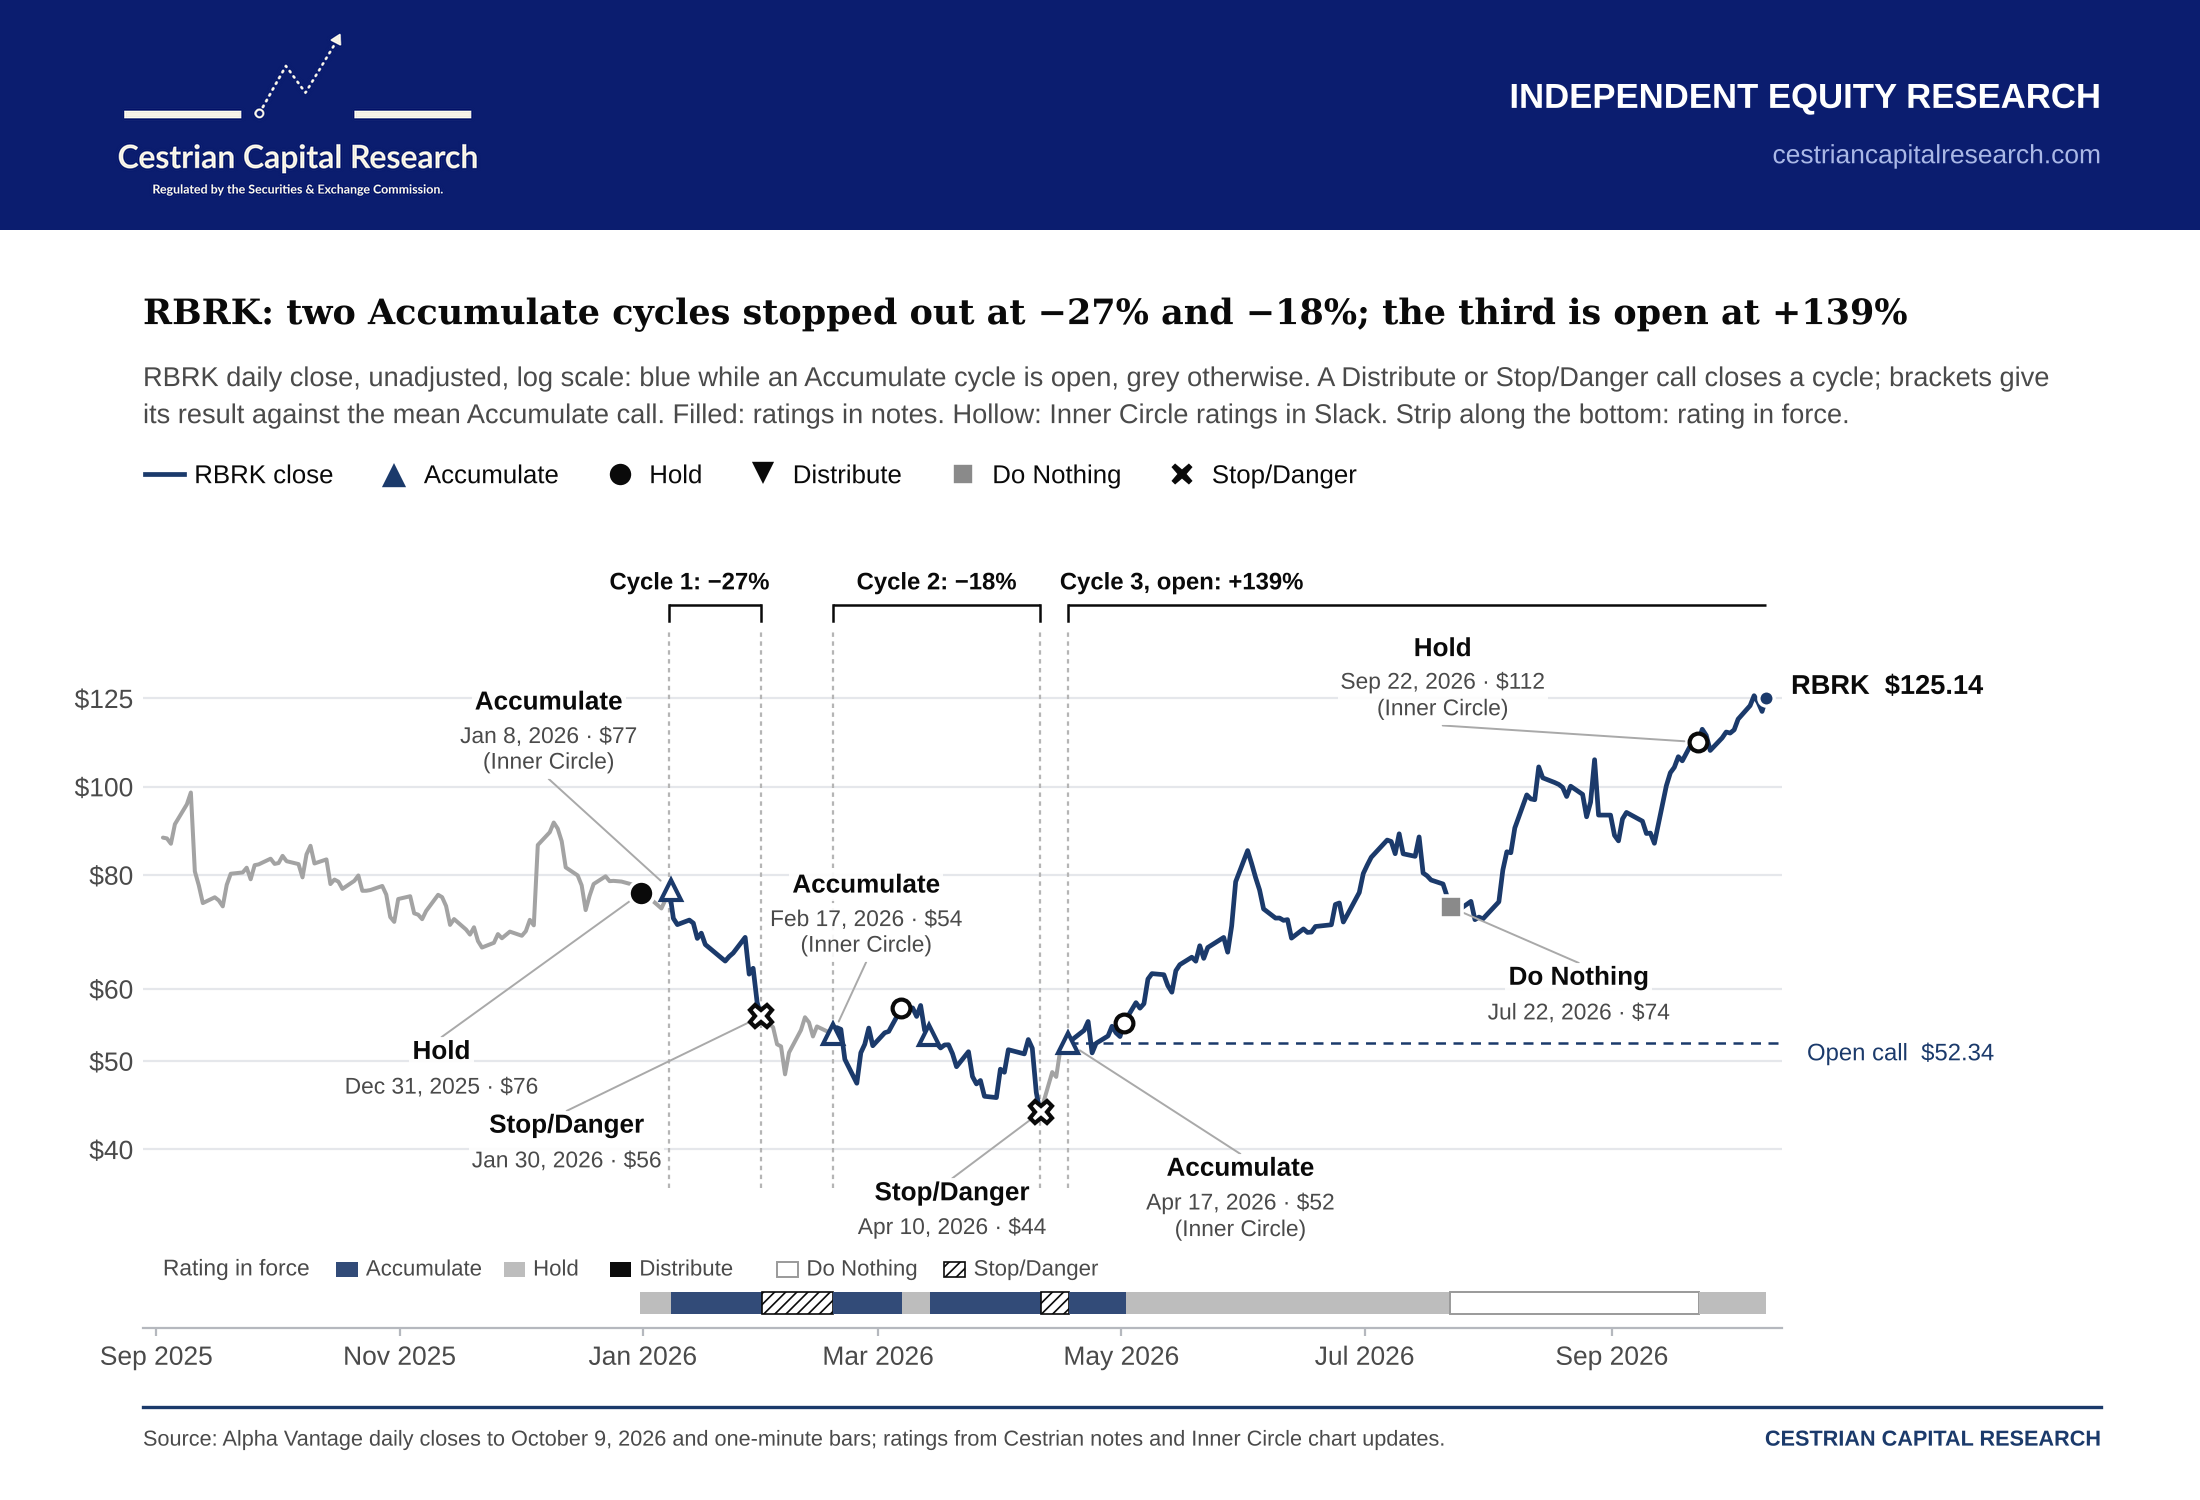
Rubrik (NYSE: RBRK) Stock Rating: DISTRIBUTE After Q2 FY1/27 Earnings
Rubrik posted 38% Q2 revenue growth to $427.3 million, but Cloud ARR growth slowed to 39% and its enterprise value reached 15.7 times trailing revenue.
Rubrik posted 38% Q2 revenue growth to $427.3 million, but Cloud ARR growth slowed to 39% and its enterprise value reached 15.7 times trailing revenue.
$EVC crashing as I’m only up 310% now. My wife is seriously pissed the heck off.
Perception <> Reality $OWL selling off on a $1bn Loparex restructuring headline, despite having already marked its second-lien exposure to 5 cents on the dollar at June 30, down from 63 cents in March. That excludes any potential equity recovery… Thx for the “gift” Bloomberg… https://t.co/5p1wrv5PzL
So, you wanna be a microcap day trader? $IMCC just body slammed early A.M. traders: Step 1: Announce acquisition with vagueish details Step 2: Pump the bitch 145% Step 3: Whoopsy! BTW, we're doing an offering below yesterday close Step 4: Stock roundtrips Step 5: Class Dismissed https://t.co/tPCwgXHwgP
Flowers Foods trades at 7.5x earnings after an 80% decline, as a 50% dividend cut and potential asset sale aim to reduce leverage following…
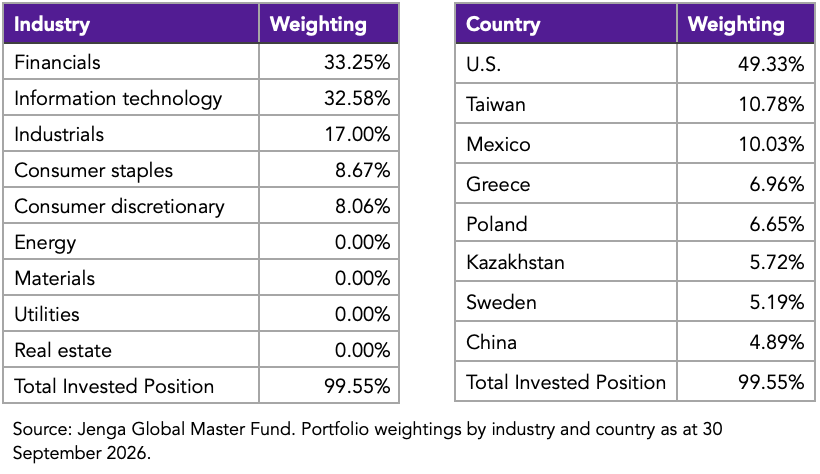
Jenga Global Master Fund returned 8.10% in Q3 2026, added Adobe and Mexican airports, and later initiated S&P Global.
Howmet Aerospace posted 24% Q2 revenue growth and 46% adjusted EPS growth, but HWM trades about 87% above a $120.69 DCF fair-value estimate.
 Alexander I. Velasquez 2 clicks
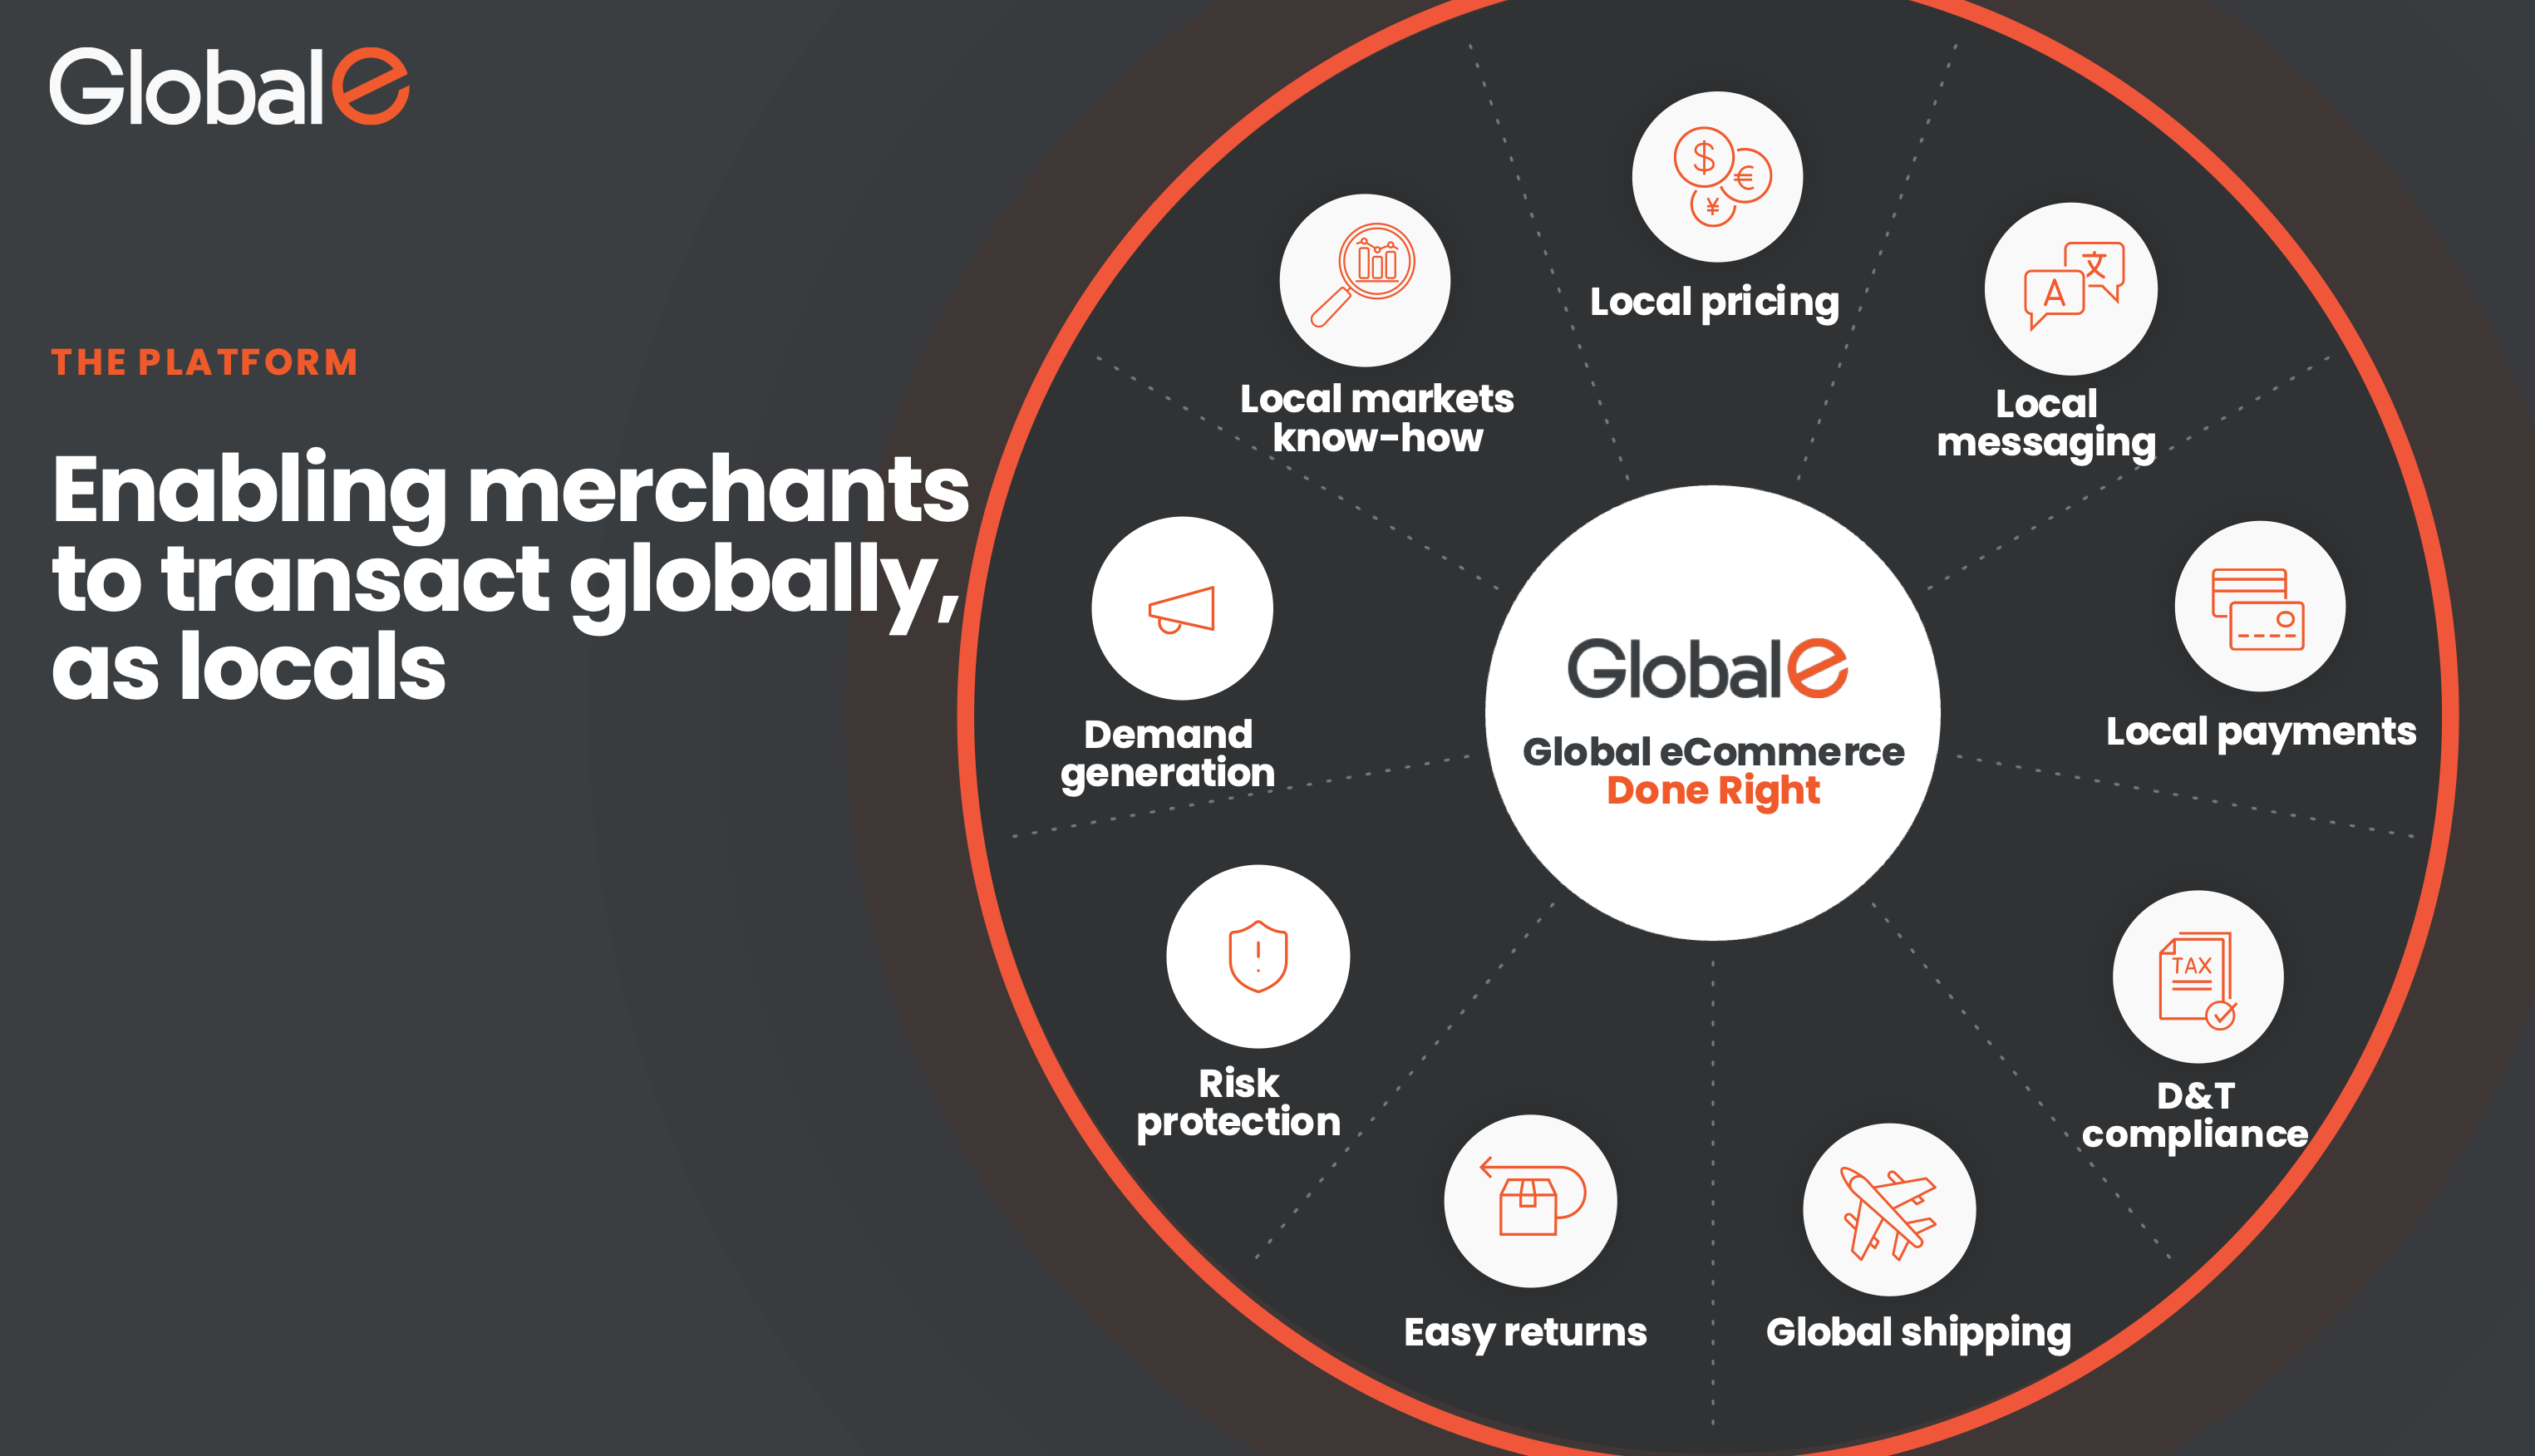
Global-e provides cross-border merchant-of-record, payments, tax and fulfillment services to more than 1,500 brands, including Shopify…
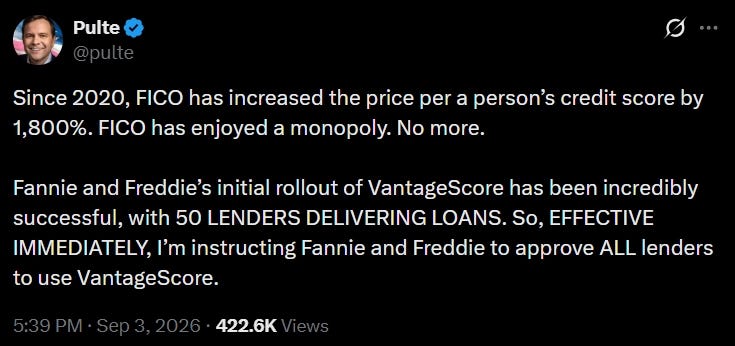
FICO’s mortgage credit-score monopoly sits at the center of a GSE-dominated U.S.
Penguin Solutions grew FY2026 revenue 26% as AI data-center and memory demand expanded, while negative free cash flow and cyclical memory…
 Investor Overview 5 clicks
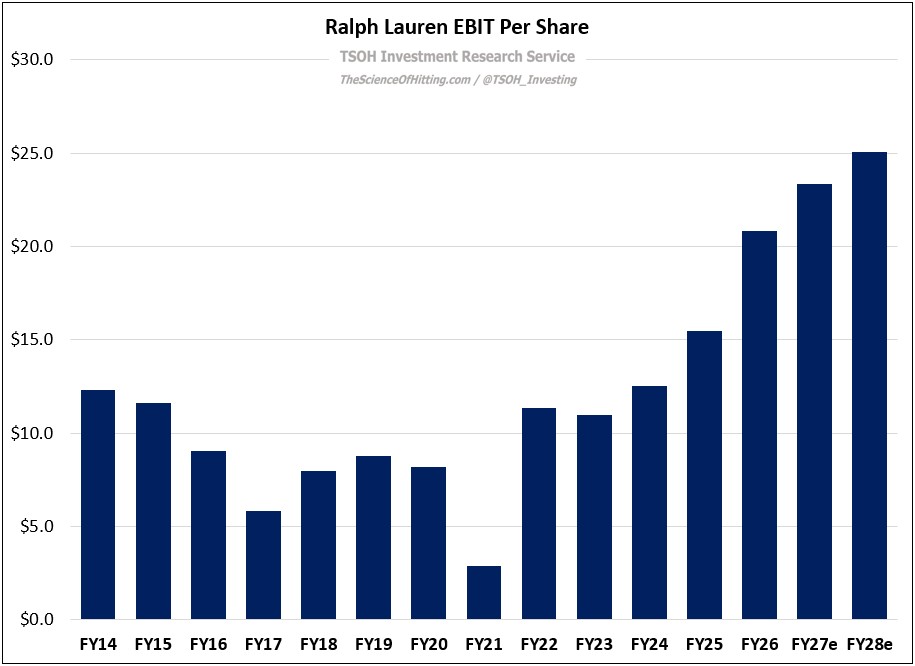
Ralph Lauren’s 2017 CEO change put Patrice Louvet in charge of reversing nine quarters of same-store sales declines and restoring the…
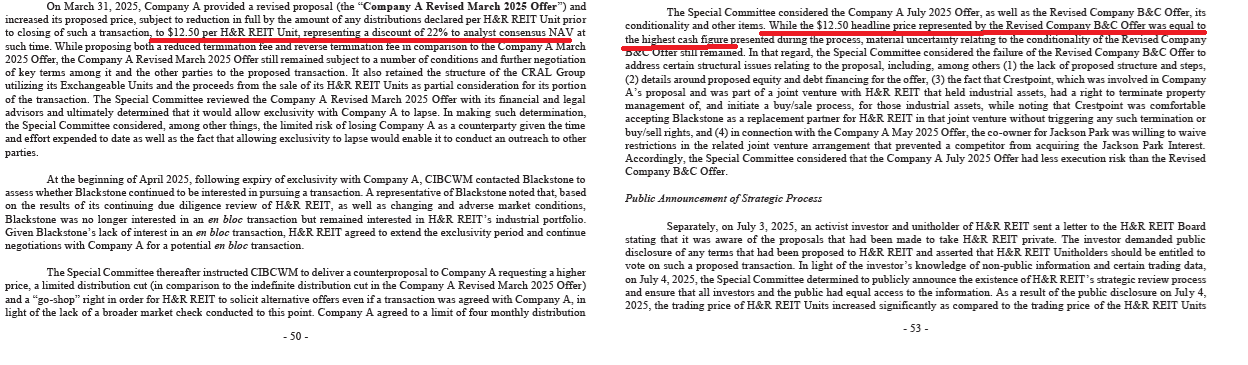
H&R REIT's proposed GO Residential transaction faces investor opposition over rejected $12.50 cash bids, insider benefits and tax…
Dassault Aviation leads a 53-pitch roundup with a €45 billion order book against €7.4 billion of sales and a 26.6% Thales stake.
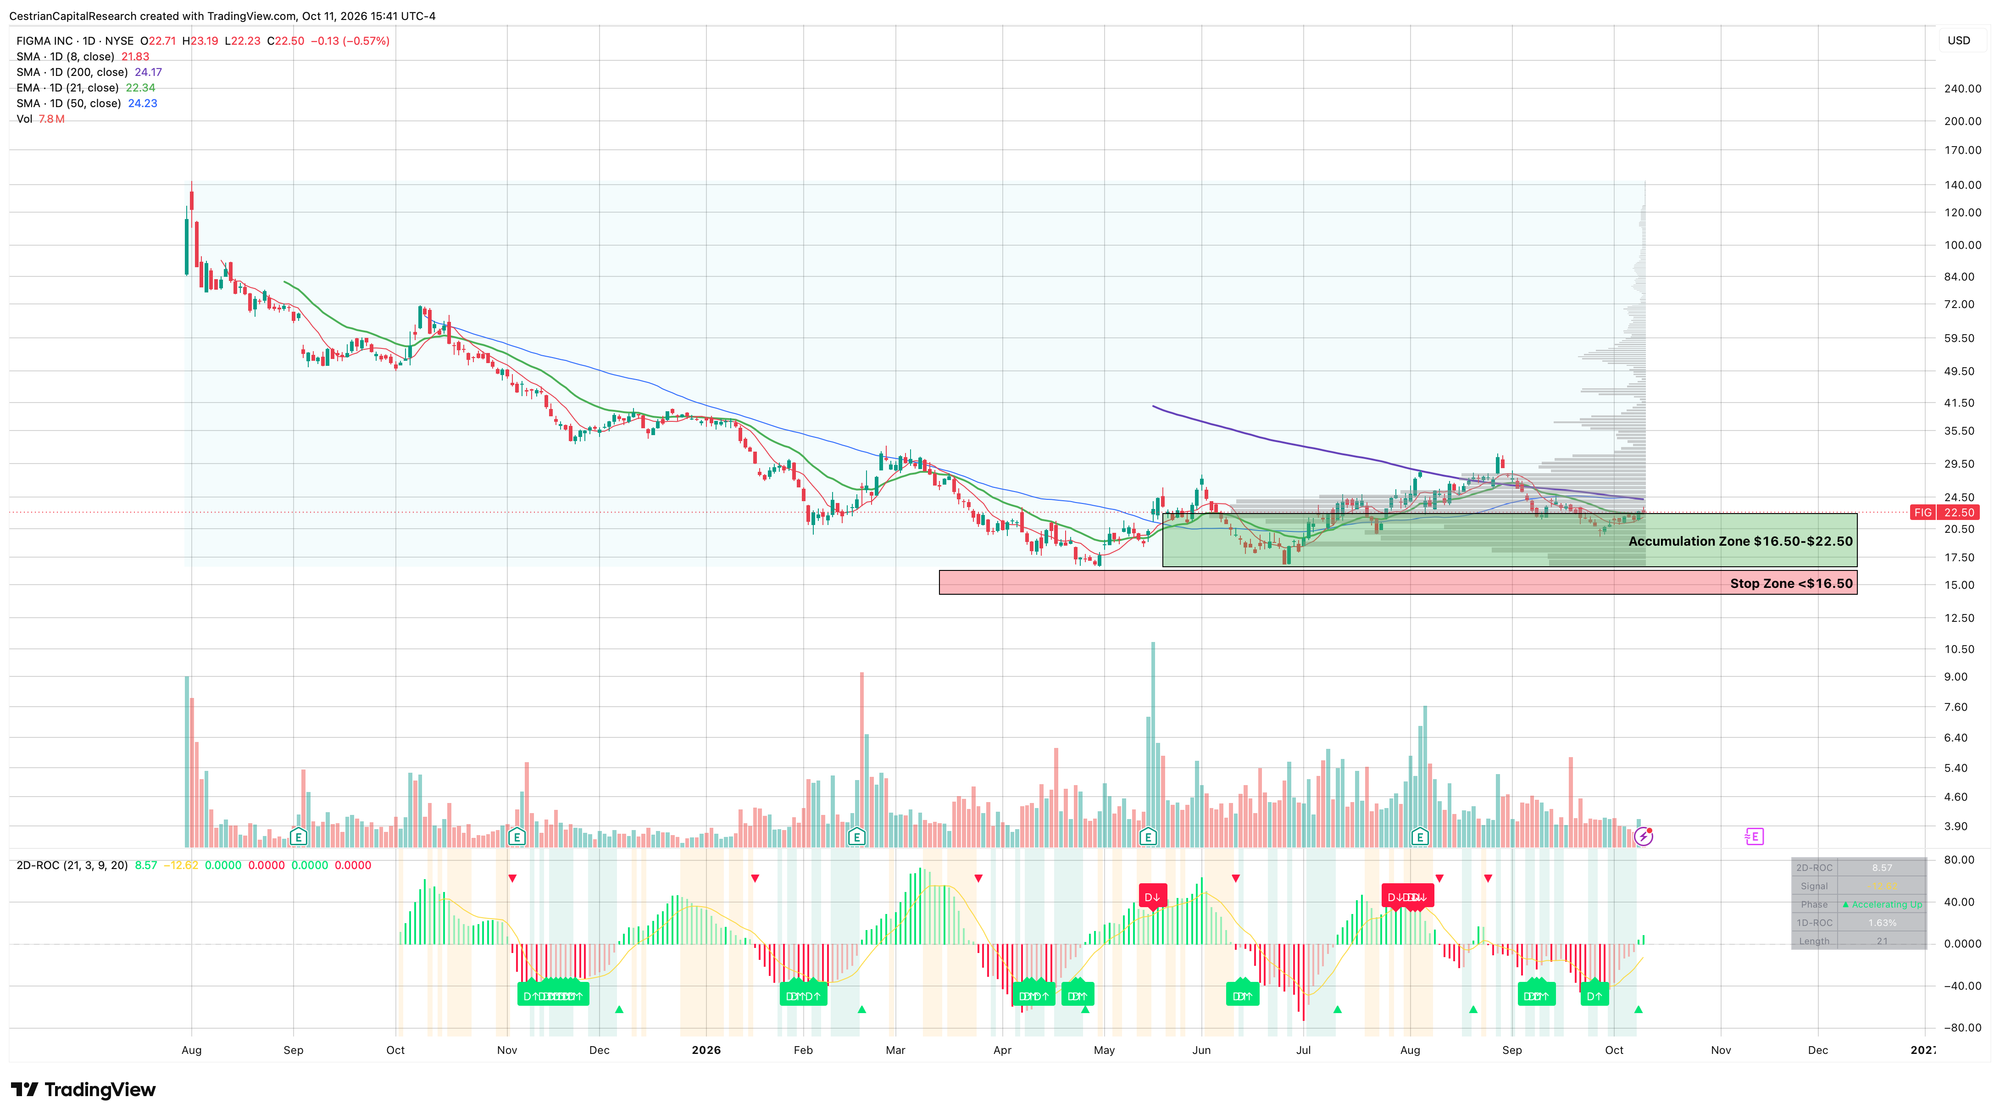
Figma’s Q2 revenue rose 48% to $370.1 million as AI credit adoption lifted retention to 136%; FY2026 revenue guidance increased to $1.463…
 DB · long
Deutsche Bank trades at 1.0x tangible book, with projected ROTCE above 13% and a favorable setup ahead of earnings.
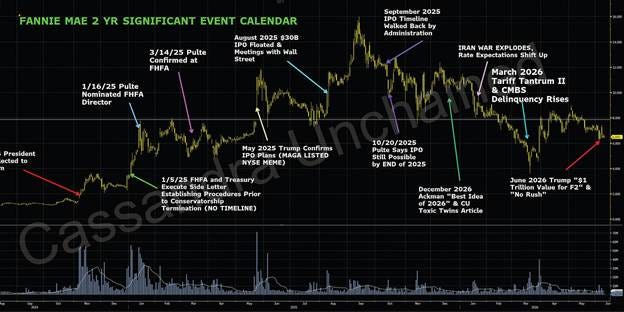
Fannie Mae and Freddie Mac common shareholders face at least 90% dilution if Treasury converts its growing senior preferred stakes into…
Rocket Lab’s $2.36 billion backlog and Iridium acquisition support growth, but delayed Neutron testing, dilution and losses leave RKLB…
 Bohdan Kucheriavyi 7 clicks
Inter & Co, Brazil’s second-largest neobank, grew over 20% with controlled delinquencies and 15% book-value compounding while trading at…
Coupang’s November 2025 cybersecurity breach tests whether a selloff is temporary despite its 28% Korean e-commerce share, 14 million-plus…
Hippo’s insurance platform posted 61% premium growth, a 95.8% combined ratio and a fifth profitable quarter as it shifted toward carrier…
Brazil Potash has secured court support and a power agreement, but financing, dilution and potash-price-sensitive EBITDA remain central…
 Wolf Report 3 clicks
Brazil’s October 25 runoff puts Bolsonaro’s likely victory at the center of a bullish regional-stock case; Golar LNG (GLNG) also reports…
Deckers trades at 11x forward earnings with $1.6 billion cash, no debt and aggressive buybacks, as HOKA growth and UGG profitability…
 TQP Research 5 clicks
Synopsys moved to Distribute after Q3 revenue rose 42% on Ansys, while organic growth was 7% and the stock traded at 11.1 times trailing…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 Kurt Christensen
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.