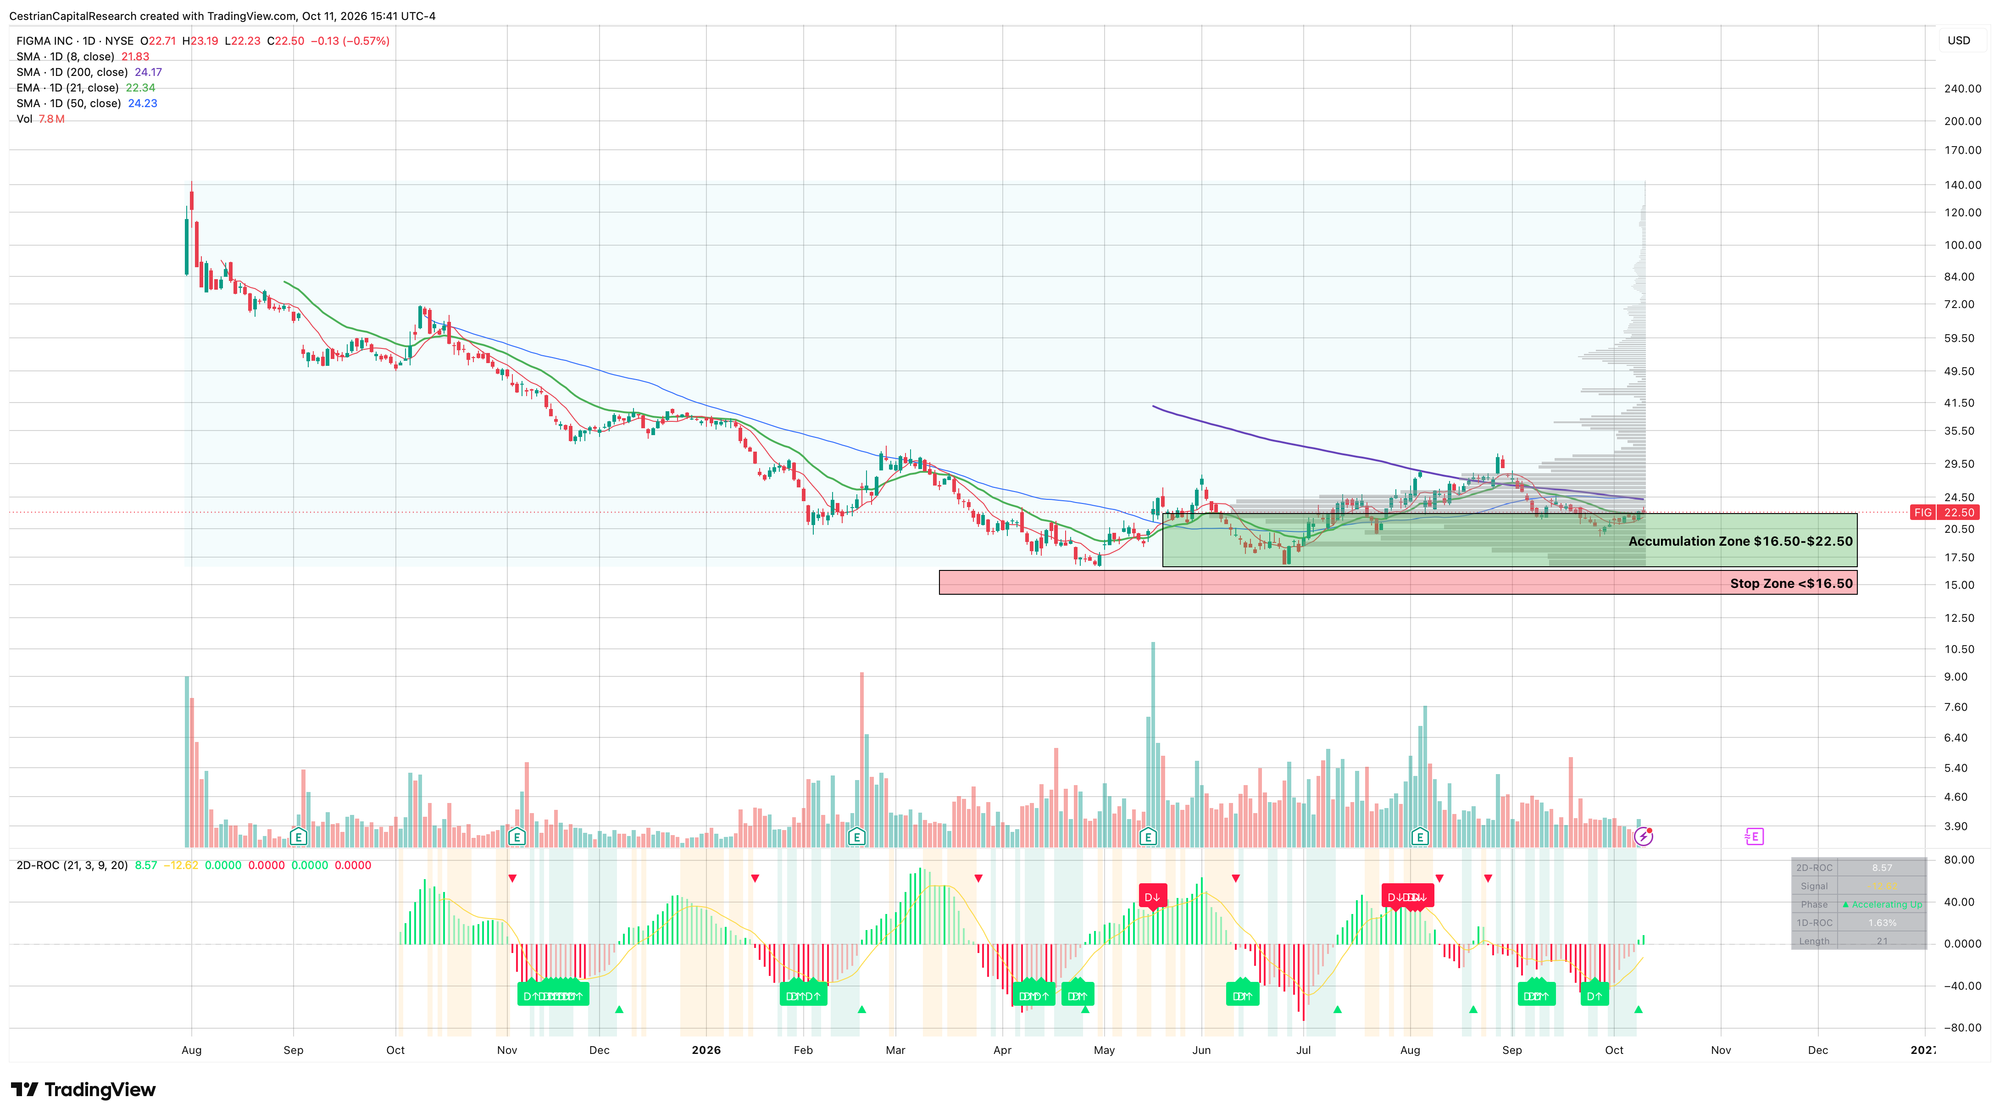
Figma (NYSE: FIG) Stock Rating: Accumulate After Q2 FY12/26 Earnings
Figma’s Q2 revenue rose 48% to $370.1 million as AI credit adoption lifted retention to 136%; FY2026 revenue guidance increased to $1.463 billion to $1.467 billion.
Figma’s Q2 revenue rose 48% to $370.1 million as AI credit adoption lifted retention to 136%; FY2026 revenue guidance increased to $1.463 billion to $1.467 billion.
What’s $FTAI worth even assuming Power is $0?
$LULU just now https://t.co/CMBjD201I0
At this point $NKE and $LULU should just merge to create one big piece of shit
A leaked GameStop $GME memo has used PlayStations trading 50% higher than MSRP because of GTA release. GameStop about to print money into the end of the year. https://t.co/niu0IXZytS
What's wrong with $BSP ? https://t.co/XXaB7KnW0R
Paramount Skydance’s debt-heavy Warner Bros. Discovery acquisition, streaming bundle pricing and alcohol-industry diversification anchor…
Consumer agents create an ethics race among AI labs and a prisoner’s dilemma for retailers, with online travel agencies framed as an…
AppLovin's Ads Manager targets middle-market e-commerce advertisers as Q3 guidance calls for 47% sales growth, while legal and compute-cost…
 Jack Elias 3 clicks
Robinhood’s AI agents, 24/7 equity trading and 10:1 crypto perpetual futures encourage higher retail trading velocity, leverage and…
Yellow Cake and Cameco say U.S. utilities have contracted only 40% of 2030 uranium needs, setting up a new contracting cycle as…
Special-situations survey profiles 26 activist, capital-return, M&A and strategic-alternative catalysts, led by buybacks at Under Armour,…
Millrose told Goldman its Lennar purchases had rent-to-own tenants lined up, but most analyzed homes were advertised for rent and showed…
Nike's 4.8% dividend yield masks payout ratios above 100% of forward EPS and inadequate free cash flow coverage, while China sales declines…
 Sensor Unlimited
Vertiv's 33% stock decline followed a 2026 forecast increase, despite a $15 billion backlog and rising AI data-center demand for power and…
Undercovered Dozen spotlights 12 lesser-covered stocks, including Brookfield Renewable, Annaly Capital and Seagate.
 The Undercovered Dozen
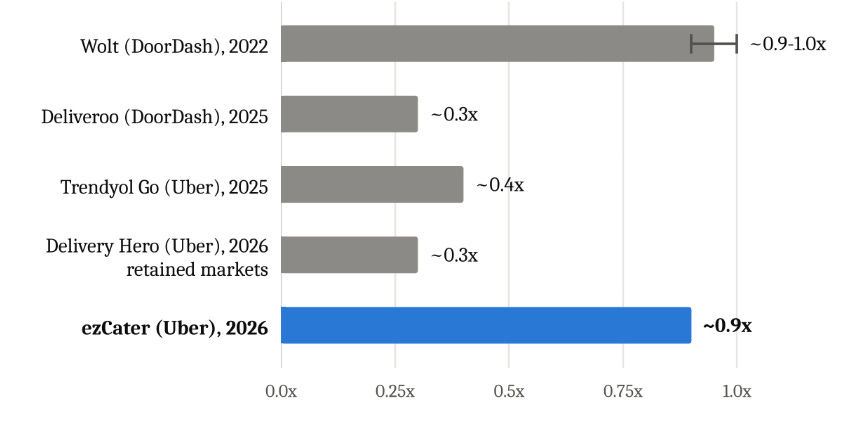
Uber’s $2.3 billion cash purchase of ezCater extends its buy-versus-build strategy and raises questions about the price and capital…
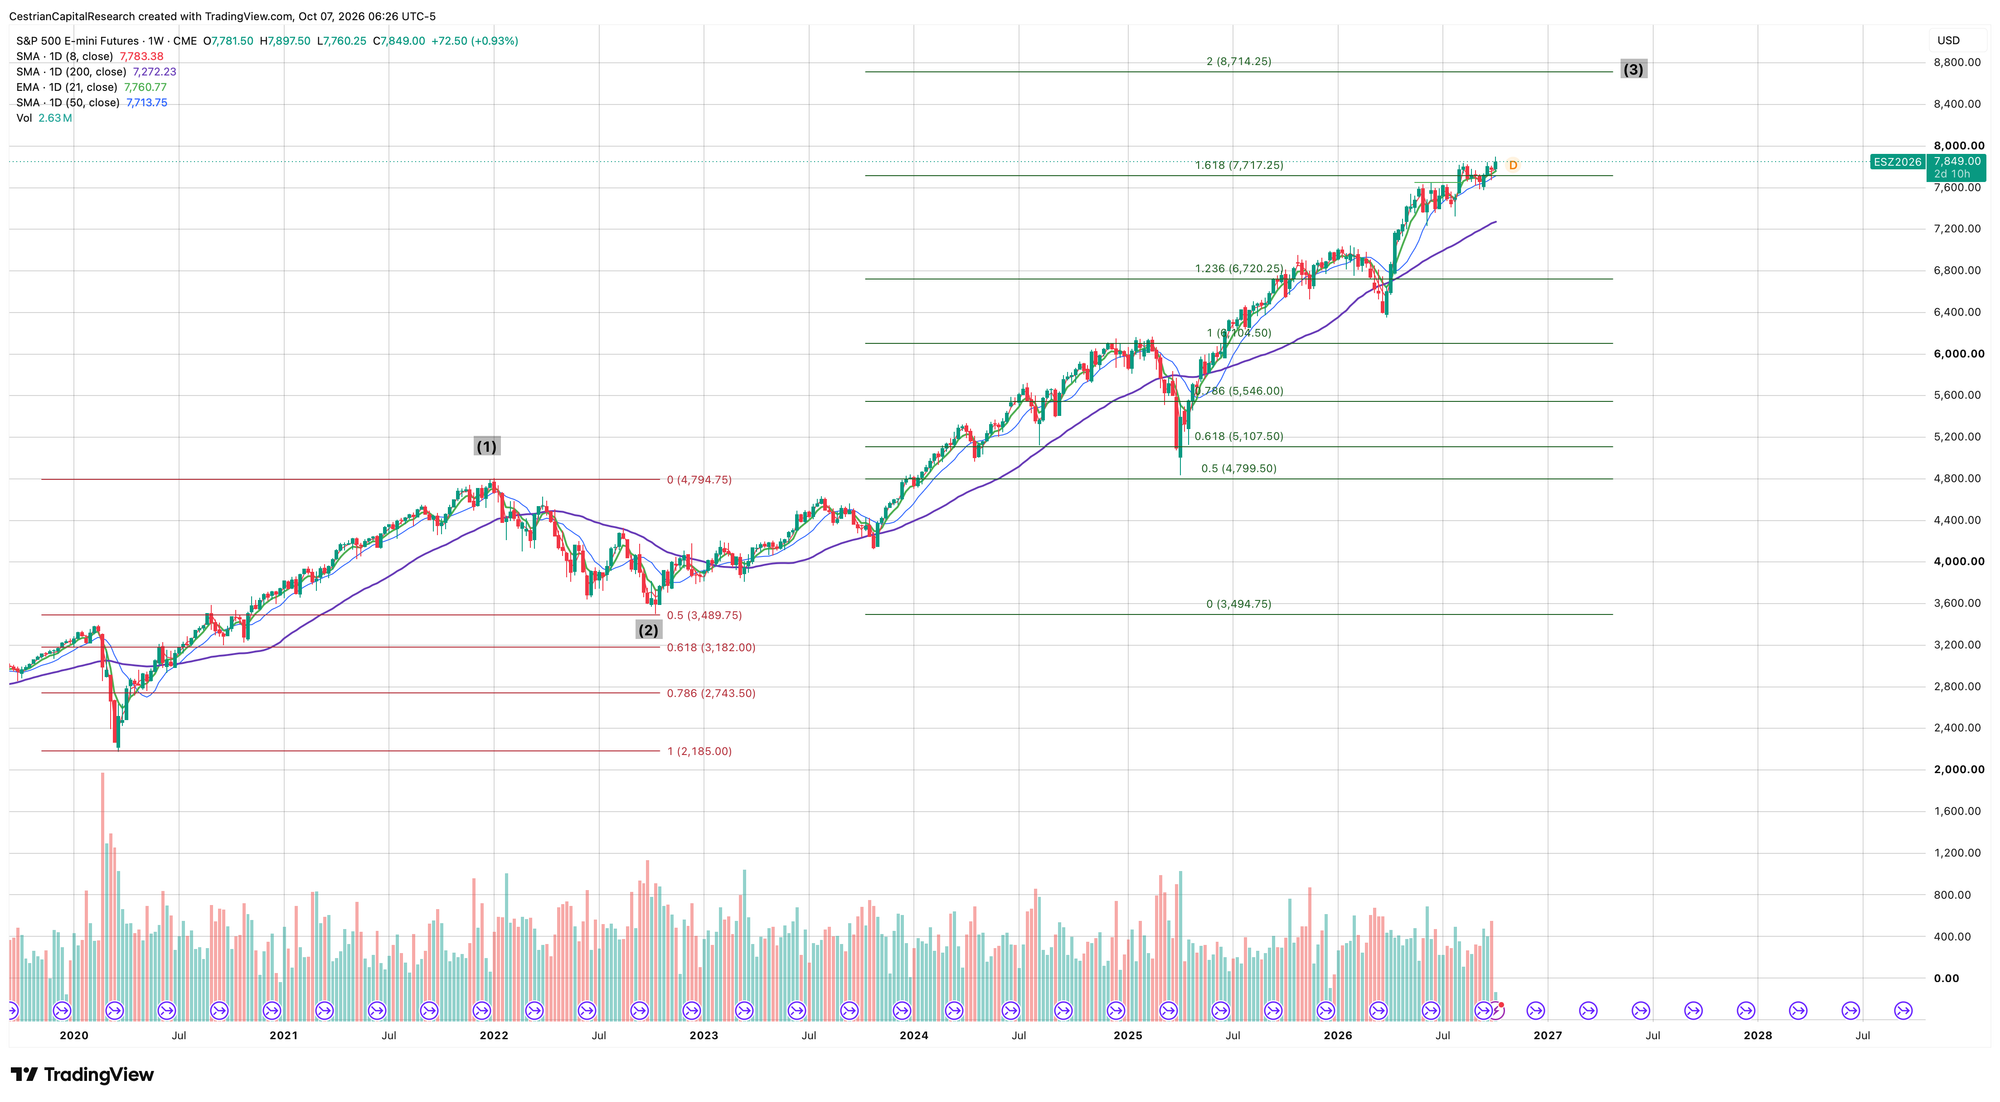
L3Harris upgraded to Accumulate after a 38% stock decline, backed by 8% Q2 revenue growth, a $42 billion backlog and planned Missile…
Cerebras retains its 750 MW commitment despite OpenAI's Nvidia move, but TSMC supply, owned capacity and gross-margin recovery remain the…
 Deep Value Investing
OpenAI’s enterprise privacy push and Synopsys’s Factory 2 royalty model anchor a technology roundup, alongside oil above $100 and Bitcoin’s…
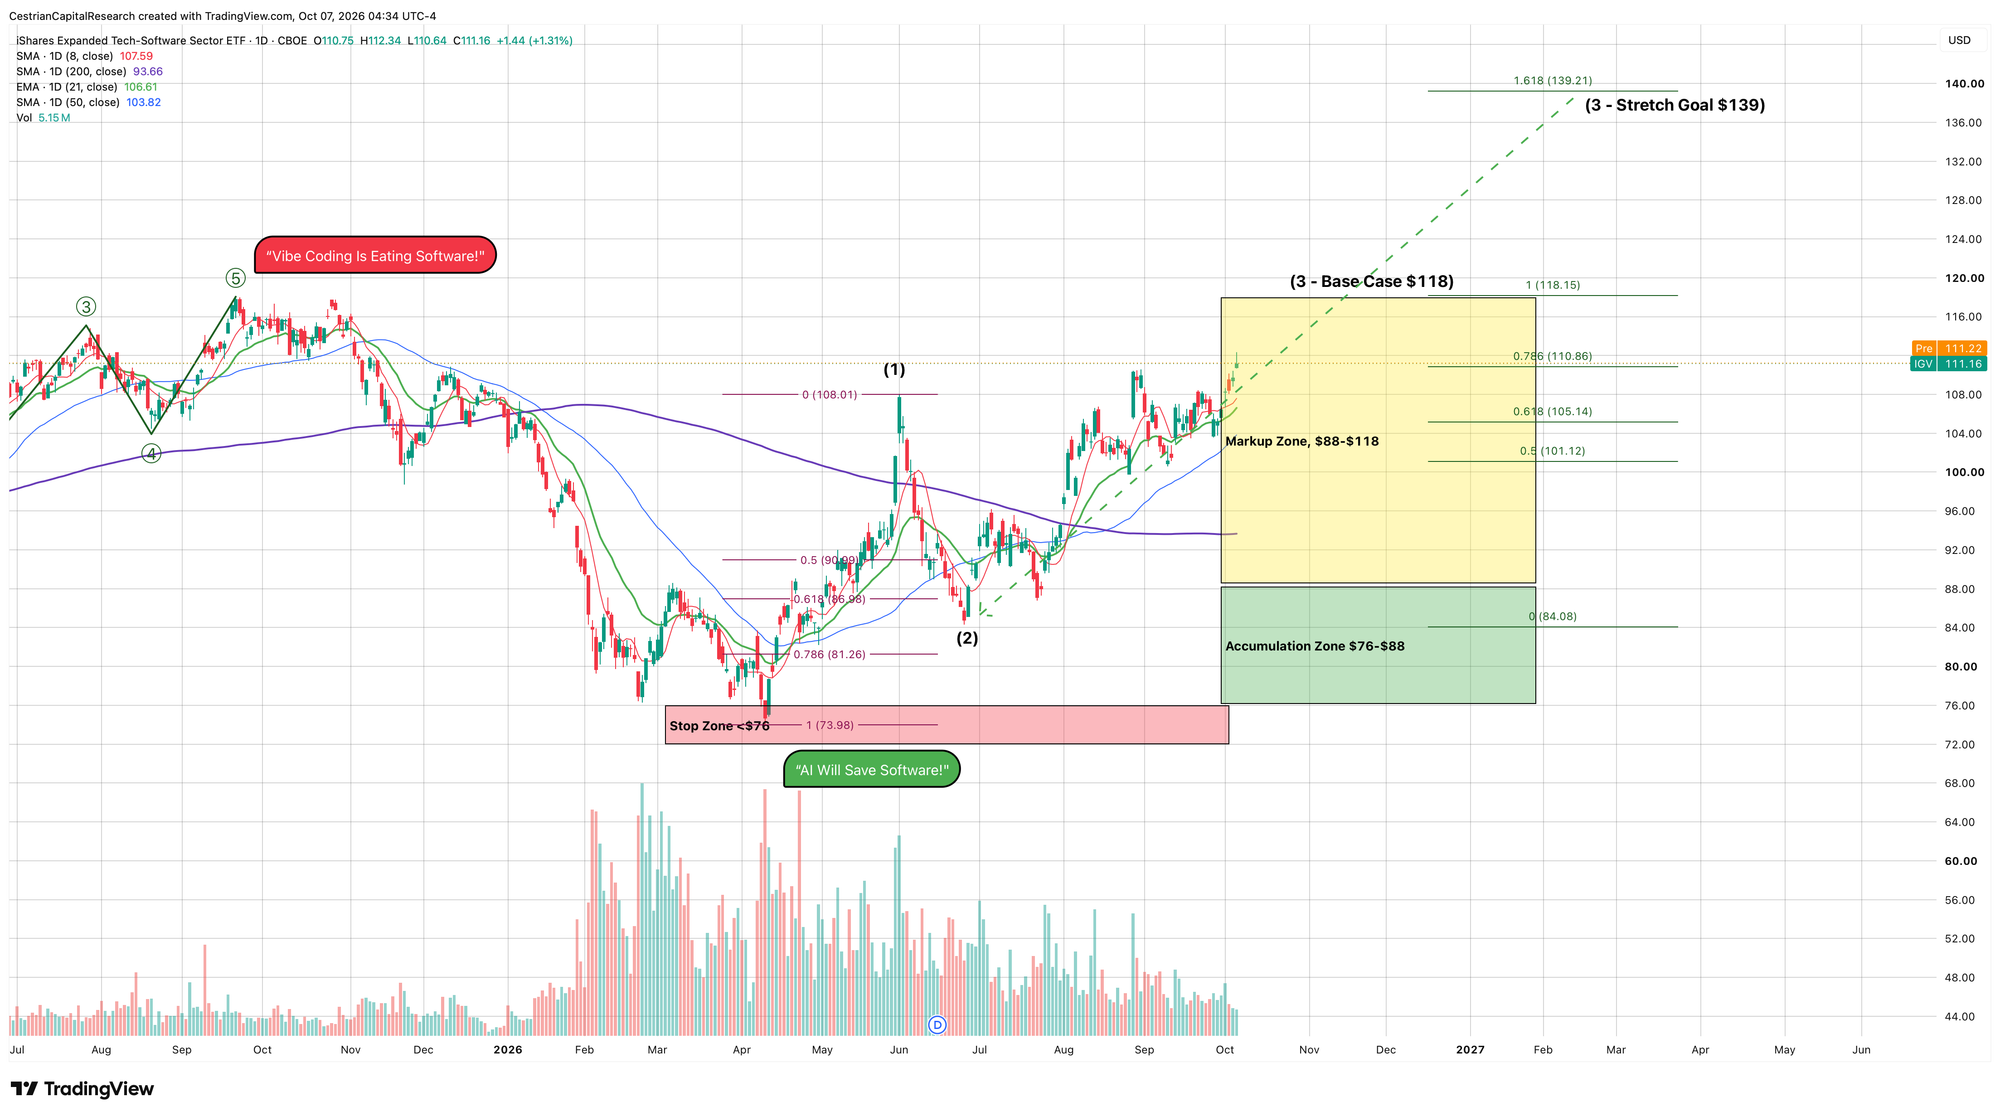
Adobe rates Accumulate at $189-$266 after Q3 FY26 revenue grew 12.9%, while management guided slower growth and RPO growth decelerated.
 VEEV · long
Veeva Systems is a vertical software company valued as if its best growth years are behind it.
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S.
Rollins’ recurring pest-control base requires ongoing spending to replace departing customers, a concern tied to its nearly 50%…
Intuit’s $21.4 billion software franchise faces AI-driven pricing pressure in tax and accounting, even as QuickBooks and TurboTax retain…
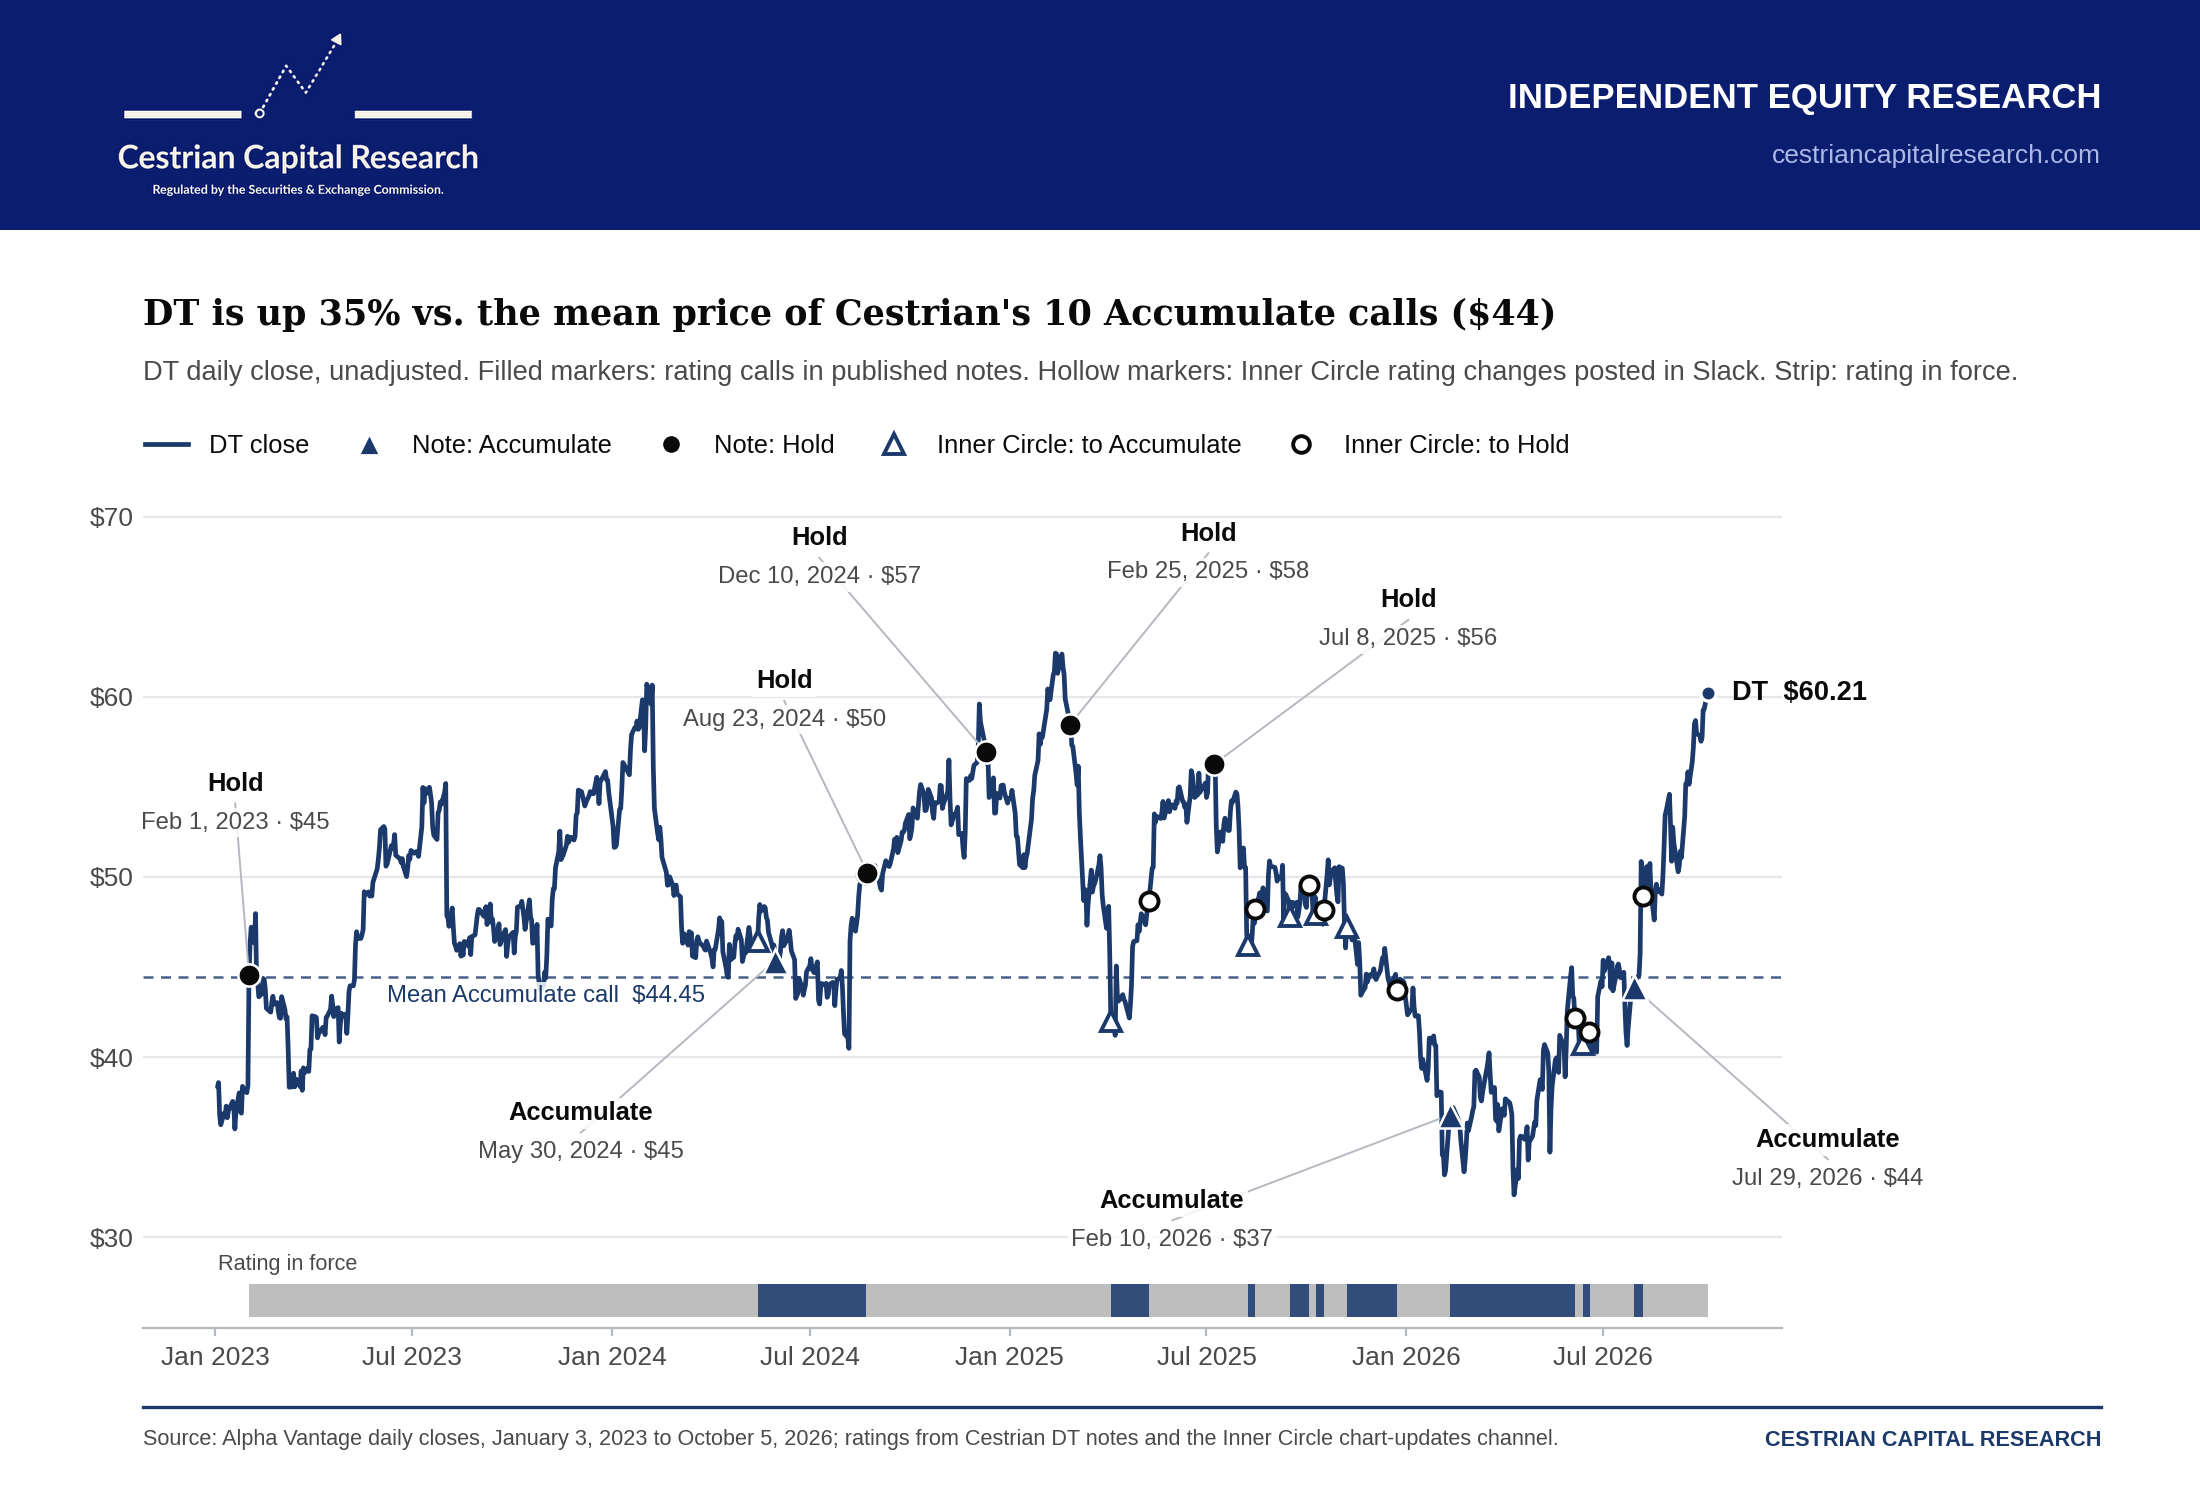
Dynatrace is rated Distribute after a 90% rally to $60.21 nears $62 resistance, while revenue and RPO growth decelerate ahead of November…
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Blake Winiecki
 Capital Connoisseur
 David Zanoni Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Julia Ostian
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Supercycle Investor The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.