What I’ve Been Up To
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Cogent Communications and AI data-center bottlenecks feature in a newsletter update on recruiting, financial media and conference takeaways.
Newest out. British American Tobacco: Harvest $BTI $PM $MO $IMBBY $HAYPP $STG https://t.co/IjOEe4izVz
$PSKY and $ORCL: The cost to insure the debt of both companies against default has converged and is increasingly moving in lock-step, a sign investors are beginning to treat the two credits as intertwined. This appears, to me, a very dangerous game the Ellison family is playing.
Great analysis on $MSCI @vachelliaequity https://t.co/LSD8XwRB6x
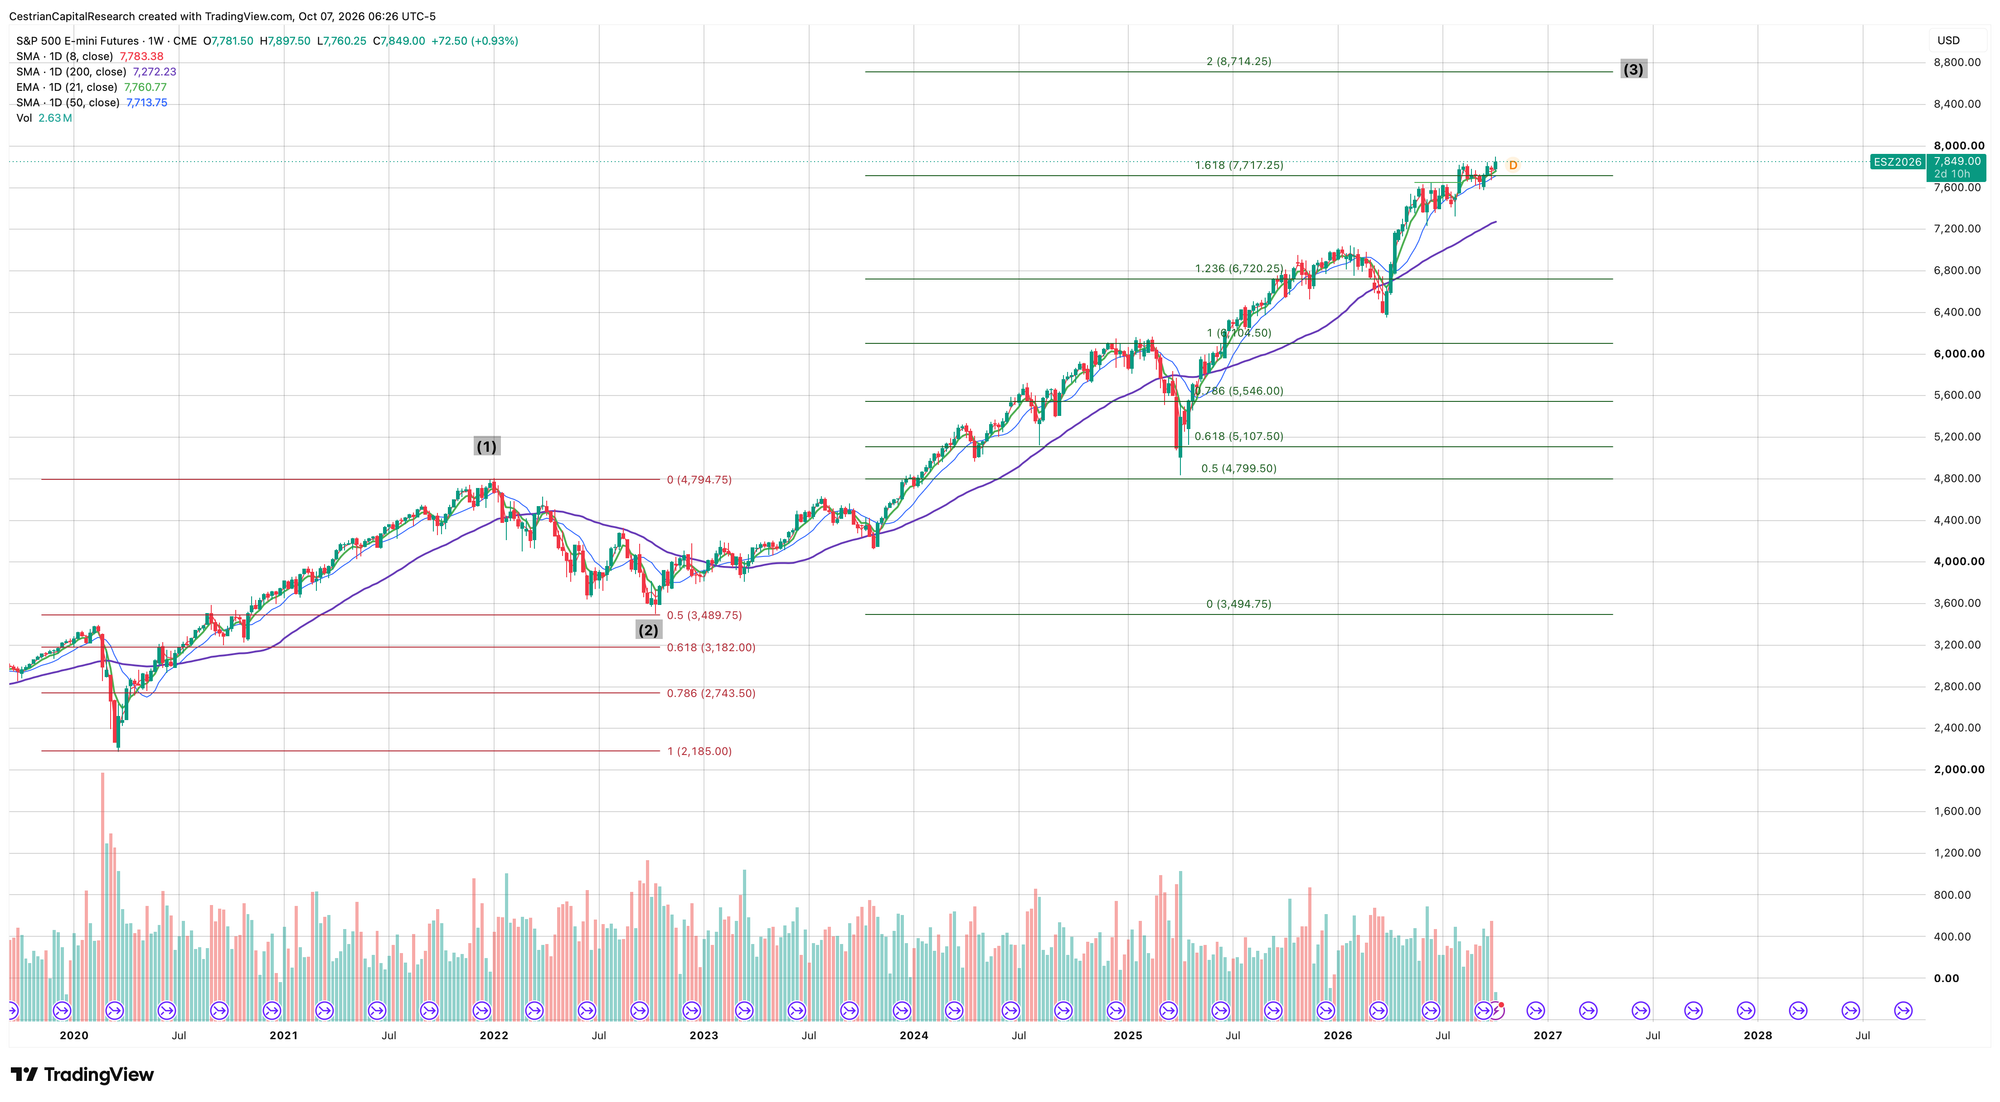
Adding long exposure (through $IWM and $RSP mainly) makes me feel sick, which backs up my belief that the timing is good to add long exposure.
@TSOH_Investing this is what $nke tried to do unsuccessfully
@coffeesnob @DELAESPRIELLAE Fun because this is 1. my local airport and 2. an $ASR property.
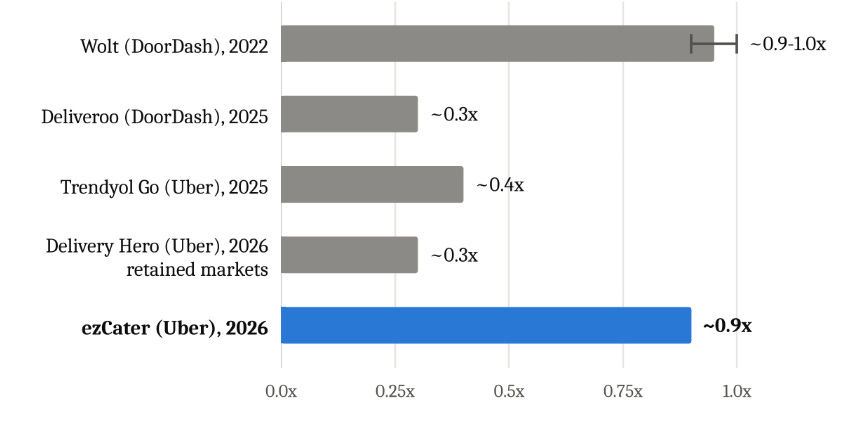
Uber’s $2.3 billion cash purchase of ezCater extends its buy-versus-build strategy and raises questions about the price and capital…
L3Harris upgraded to Accumulate after a 38% stock decline, backed by 8% Q2 revenue growth, a $42 billion backlog and planned Missile…
Cerebras retains its 750 MW commitment despite OpenAI's Nvidia move, but TSMC supply, owned capacity and gross-margin recovery remain the…
 Deep Value Investing
Salad and Go filed Chapter 11 after its Texas and Oklahoma expansion failed, seeking to sell 65 leases to Dutch Bros for $105 million as 7…
OpenAI’s enterprise privacy push and Synopsys’s Factory 2 royalty model anchor a technology roundup, alongside oil above $100 and Bitcoin’s…
Adobe rates Accumulate at $189-$266 after Q3 FY26 revenue grew 12.9%, while management guided slower growth and RPO growth decelerated.
BP is investing $10 billion annually in oil and gas through 2027 as higher crude prices, LNG expansion and debt reduction support earnings,…
 The Asian Investor 6 clicks
Marvell’s 2026 investor day draws a skeptical review of its optical connectivity, DSP and AI infrastructure claims, while crediting its…
On Holding (ONON) is gaining sportswear share, expanding store space and launching soccer with Kylian Mbappé as investors debate U.S.
Astronics targets $1.02 to $1.04 billion in 2026 revenue after adjusted operating margin reached 20.3%, with Boeing representing 12% of…
 Jordan Aquilina
 VEEV · long
Veeva Systems is a vertical software company valued as if its best growth years are behind it.
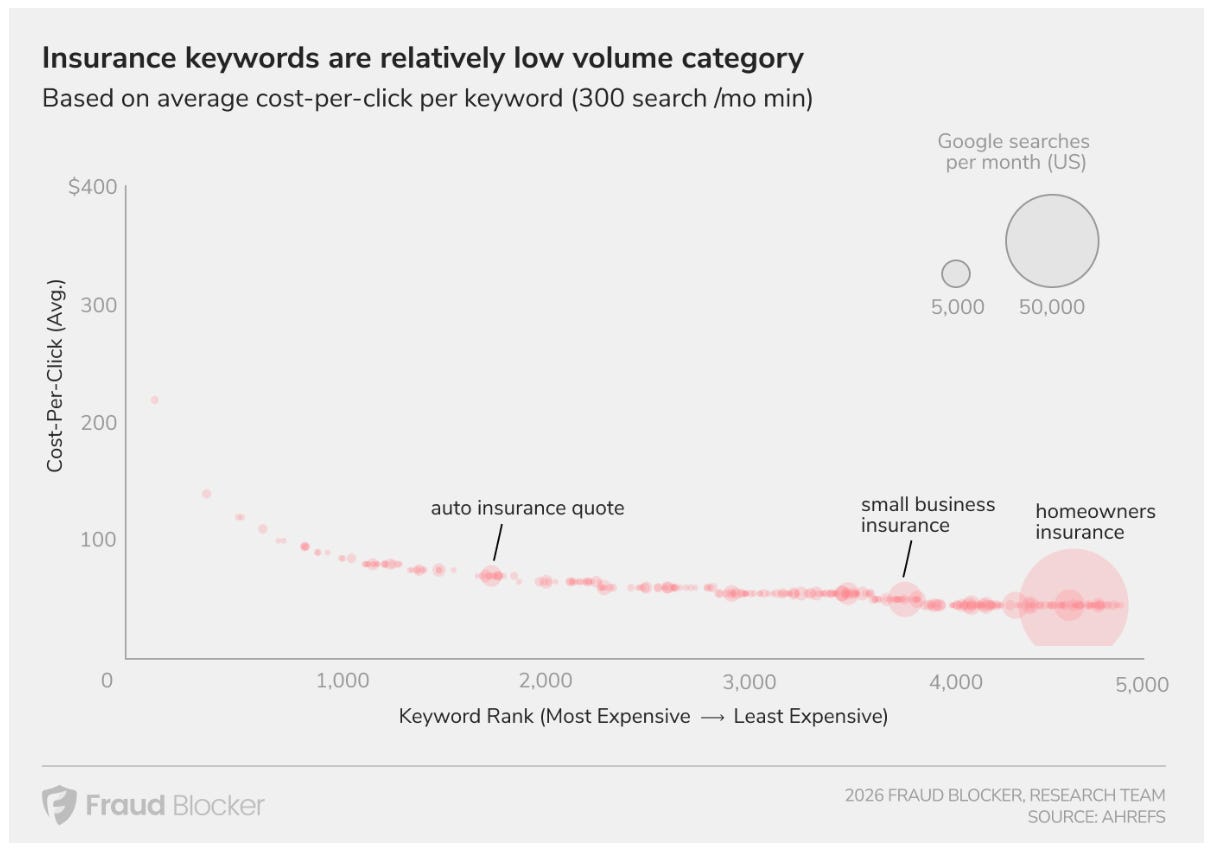
Meta’s Muse could place ads inside its AI agent by letting a private VM select offers from advertisers without sharing user data with…
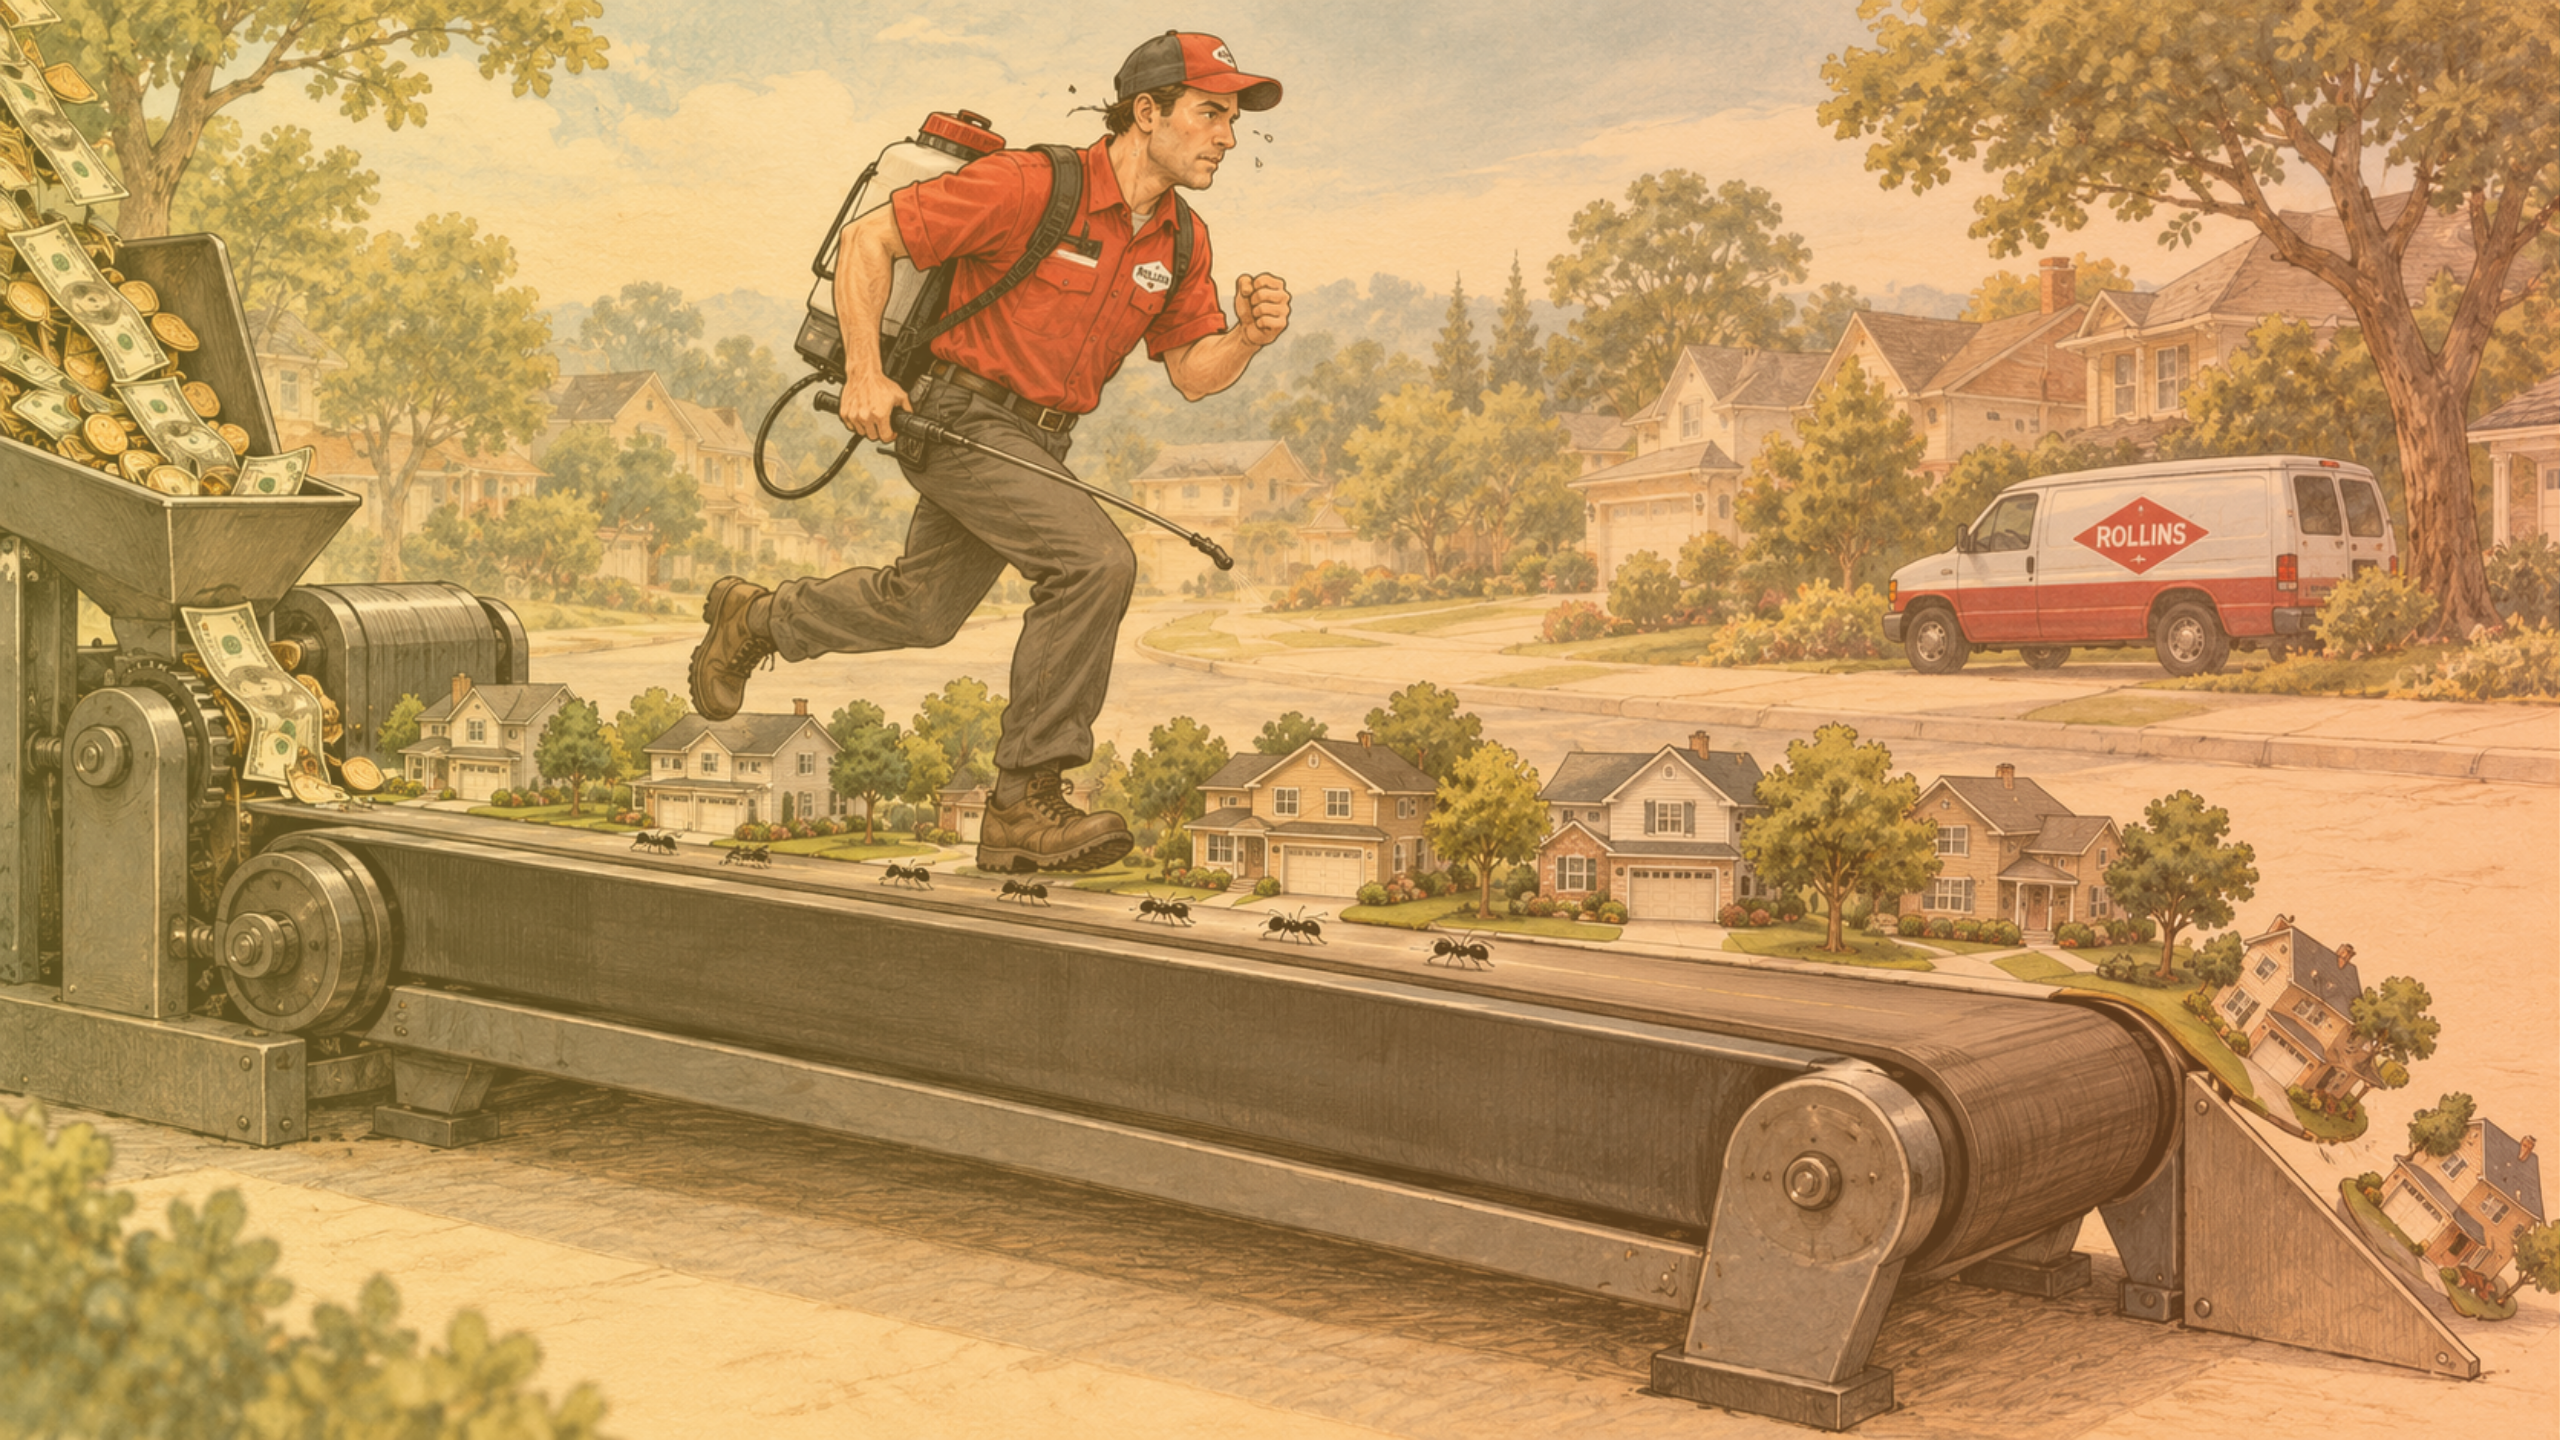
Rollins’ recurring pest-control base requires ongoing spending to replace departing customers, a concern tied to its nearly 50%…
Intuit’s $21.4 billion software franchise faces AI-driven pricing pressure in tax and accounting, even as QuickBooks and TurboTax retain…
Capitol Federal Financial's 2.31% net interest margin and $23.6 million Q3 profit support its shift toward higher-yield commercial lending,…
 Growth Stock Hunter
Golar LNG’s fourth FLNG vessel targets 3.5MTPA capacity and a 2029 delivery, supporting projected adjusted EBITDA above $1 billion in…
Uber’s valuation is framed as undervaluing ride-hailing and robotaxi growth, while record institutional ownership offsets concerns over…
 The J Thesis 3 clicks
Group 1 Automotive CEO Daryl Kenningham’s Toyota ties, capital-allocation decisions, compensation and stock sales face scrutiny after the…
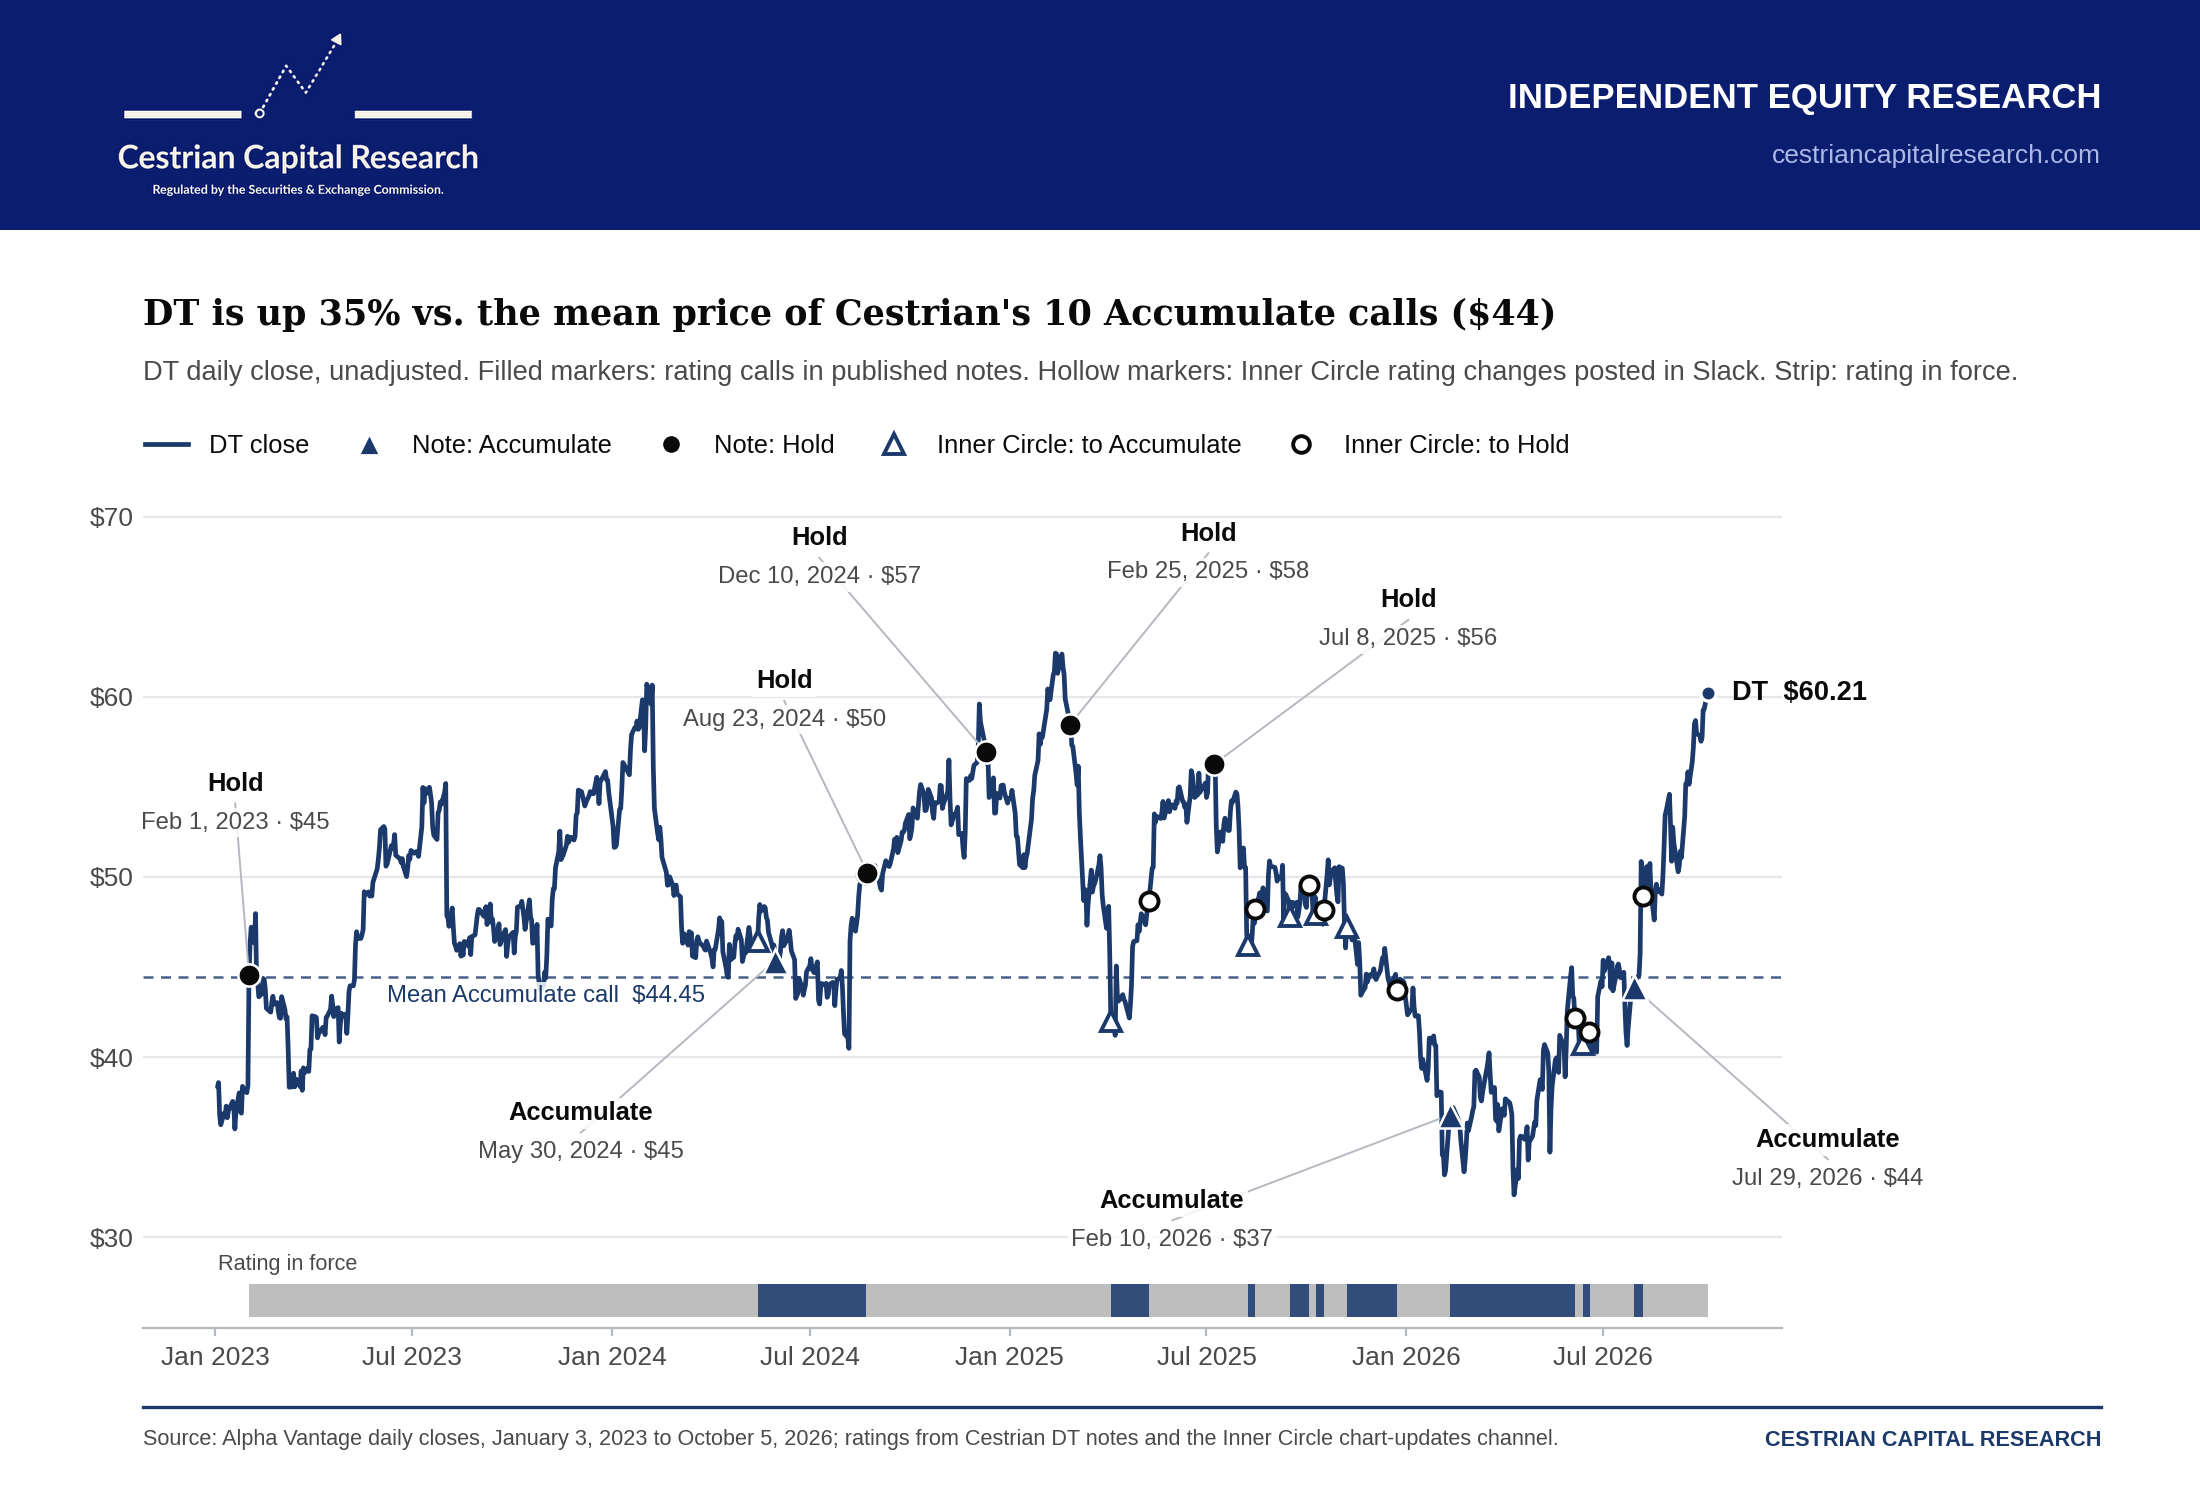
Dynatrace is rated Distribute after a 90% rally to $60.21 nears $62 resistance, while revenue and RPO growth decelerate ahead of November…
Nebius gains preferred sovereign infrastructure status for Palantir’s enterprise AI stack, using its customer base to accelerate modular…
 Petri Dish Reports 3 clicks
Every publication on this site, hand-picked.
 Albert Anthony
 Andres Veurink
 Bay Area Ideas
 Capital Connoisseur
 David Zanoni Deep Value Investing
 Dhierin Bechai
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil
 Henrik Alex
 High Alpha Professor
 Investor Overview
 IWA Research
 Jaden Mealy
 Khaveen Investments
 LL Insights
 Long Player
 Marc Gerstein
 Melissa Tucker
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Myriam Alvarez Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PV Research
 Quantryon Capital
 Robert J. Lake
 Ron Ferrie
 Sam Mancini
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 The Alpha Analyst The Asian Investor
 The Bullionaire
 The Curious Analyst The J Thesis
 The Supercycle Investor
 The Undercovered Dozen
 Value Capital Research
 Vishal Jadaun
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 Adam D. Wyden
 AltayCap
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 David Orr
 Deep Sail Capital
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital
 RiverRoadPartners
 Rusholme Capital
 Sahil Khetpal
 SG
 Sheel Mohnot
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.