The Next Consumer is a Computer
Meta’s Muse illustrates how persistent AI agents shift compute from per-query to per-user, driving heavier GPU, CPU and memory demand.
Meta’s Muse illustrates how persistent AI agents shift compute from per-query to per-user, driving heavier GPU, CPU and memory demand.

Ben Pouladian argues AMD’s Helios racks cannot match NVIDIA GPUs’ fungibility and financing appeal as agentic AI shifts the bottleneck to…
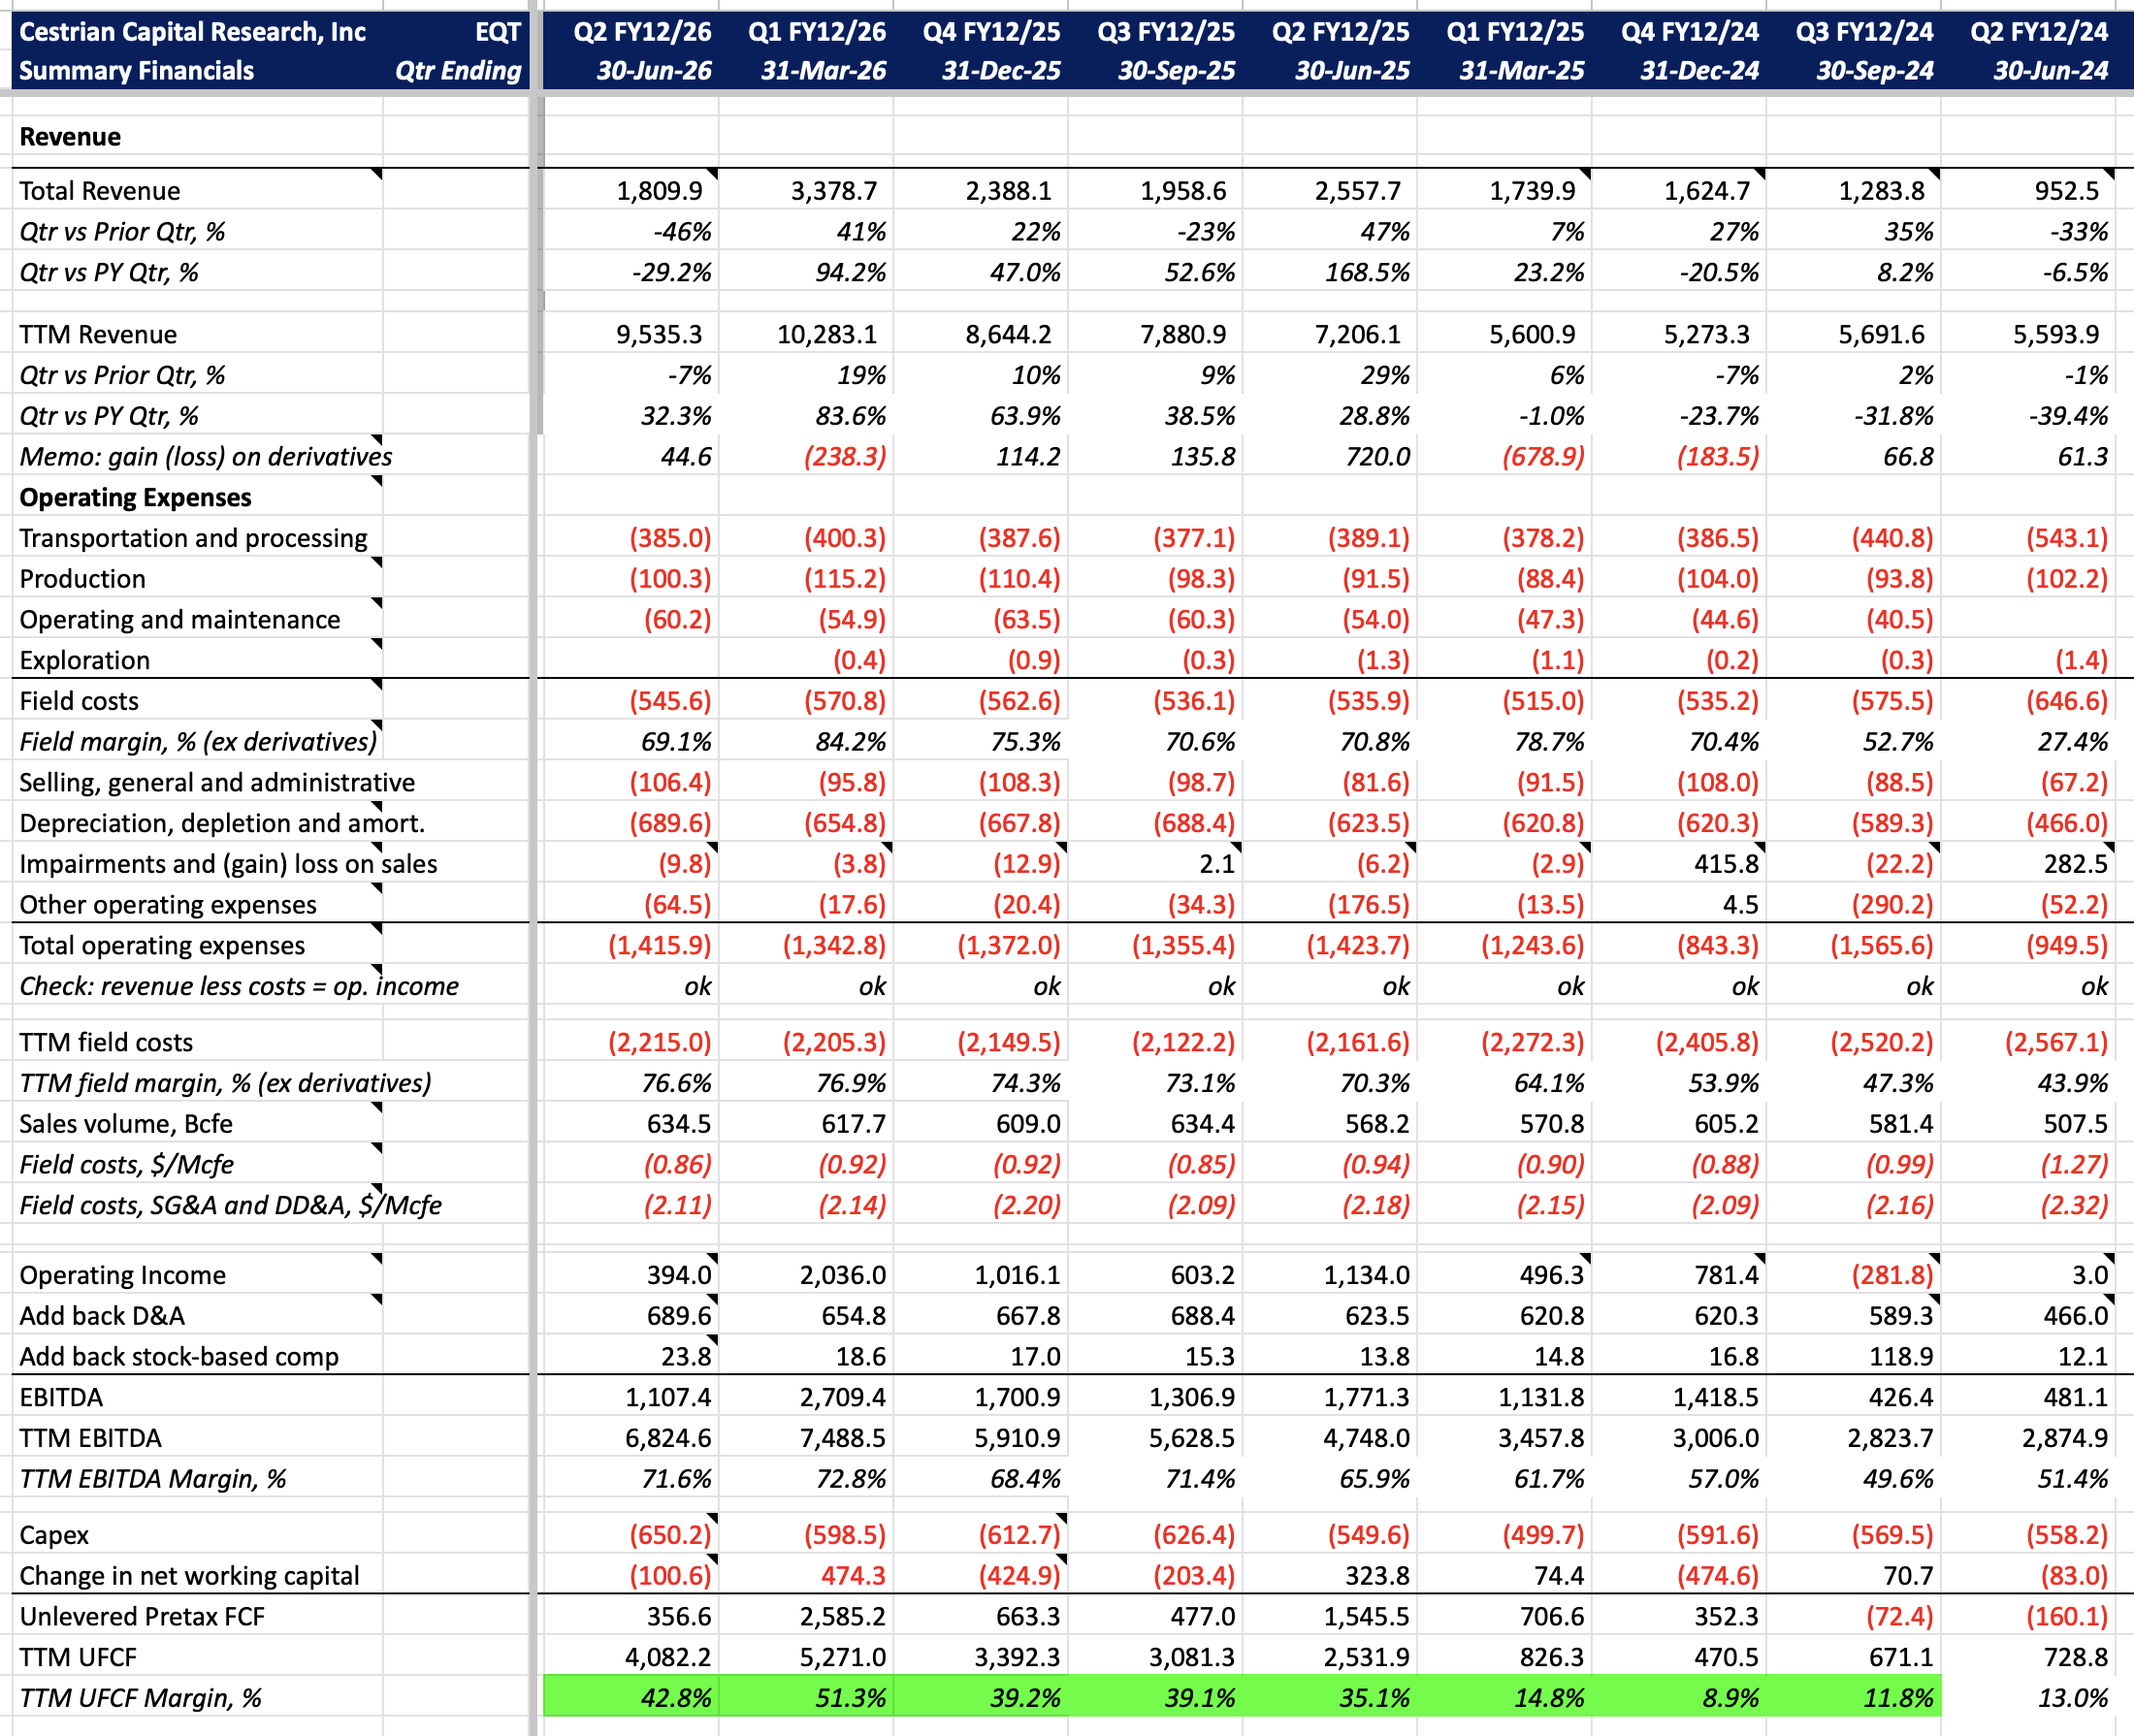
EQT remains tied to roughly $3 Henry Hub gas despite European prices near $23 per MMBtu, with US LNG export capacity limiting overseas…
Microsoft plans to rebuild Xbox after FY2026 through studio cuts, higher hardware prices, Game Pass growth, exclusive releases and the 2028…
 Khaveen Investments 2 clicks
Asia's elevator boom favors maintenance and modernization providers, with Otis deriving nearly 90% of operating profit from after-sales…
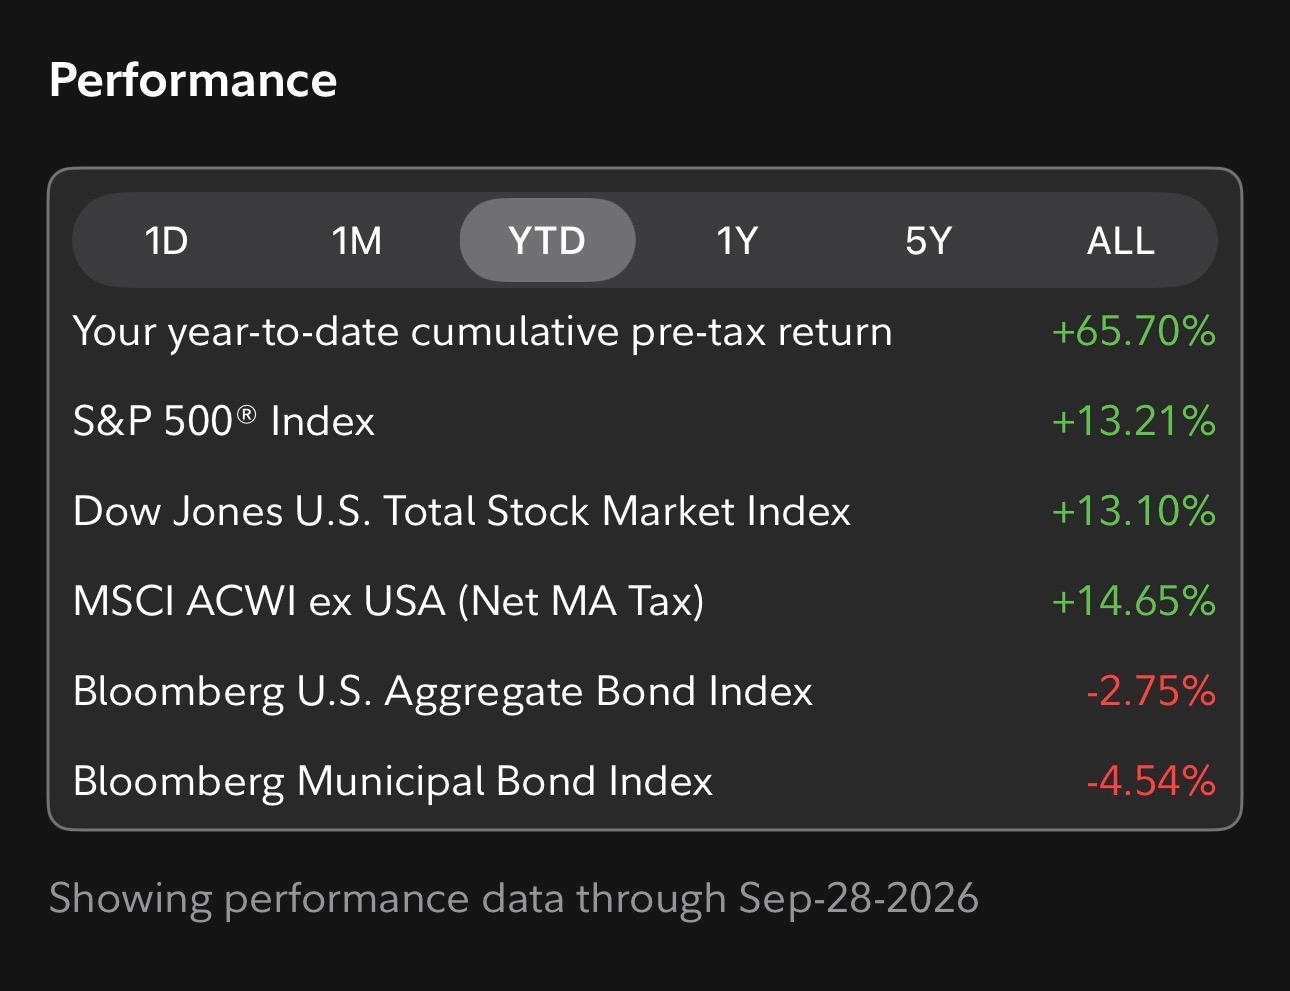
Portfolio returned 65.7% through September 28 versus the S&P 500’s 13.2%, while backing Tourmaline, EQT, Athabasca and SLB on gas demand…
FTAI Aviation’s engine-exchange model swaps CFM56 engines in days rather than 200-day overhauls, driving Aerospace Products adjusted EBITDA…

Meta’s Enterprise Platform creates a third-party compute outlet, reducing the cost of overbuilding AI infrastructure while adding…
Archer Aviation's Insitu, Wisk and SkyGrid acquisitions add military and drone revenue, cutting FAA-certification dependence and leaving…
 The Alpha Analyst 4 clicks
Nvidia CEO Jensen Huang says the company will buy back hundreds of billions of dollars of stock in coming years.
Pfizer’s new products and $9.7 billion cost-cut plan target earnings support through COVID normalization and patent expiries, alongside a…
 Value Capital Research 1 click
 EUXTF · long
Euronext has evolved from a regional cash-equities exchange into a pan-European market-infrastructure platform after a decade of technology…
CoreWeave funds GPU data-center expansion with debt backed by $104 billion in contracted revenue, while GPU cloud rentals generate roughly…
Texas Instruments, ON Semiconductor and Vishay are rated Accumulate on rising robotics demand for analog, power and discrete chips after a…
Innodata's new Meta contract for long-horizon agent personalization ties the data company to Meta's Muse AI assistant, despite Meta's Scale…
Reddit’s subreddit-driven communities support targeted advertising, and its 0.3 PEG ratio makes RDDT undervalued, according to the upgrade…
 Fountainhead 3 clicks
Credo Technology was added at $170.54 after a 40% selloff, backed by its high-speed AECs and optical connectivity for AI data centers.
Copart’s $1.9 billion ACV Auctions acquisition targets renewed growth, with EPS accretion expected by fiscal 2028 as insurance…
 Robert J. Lake 3 clicks
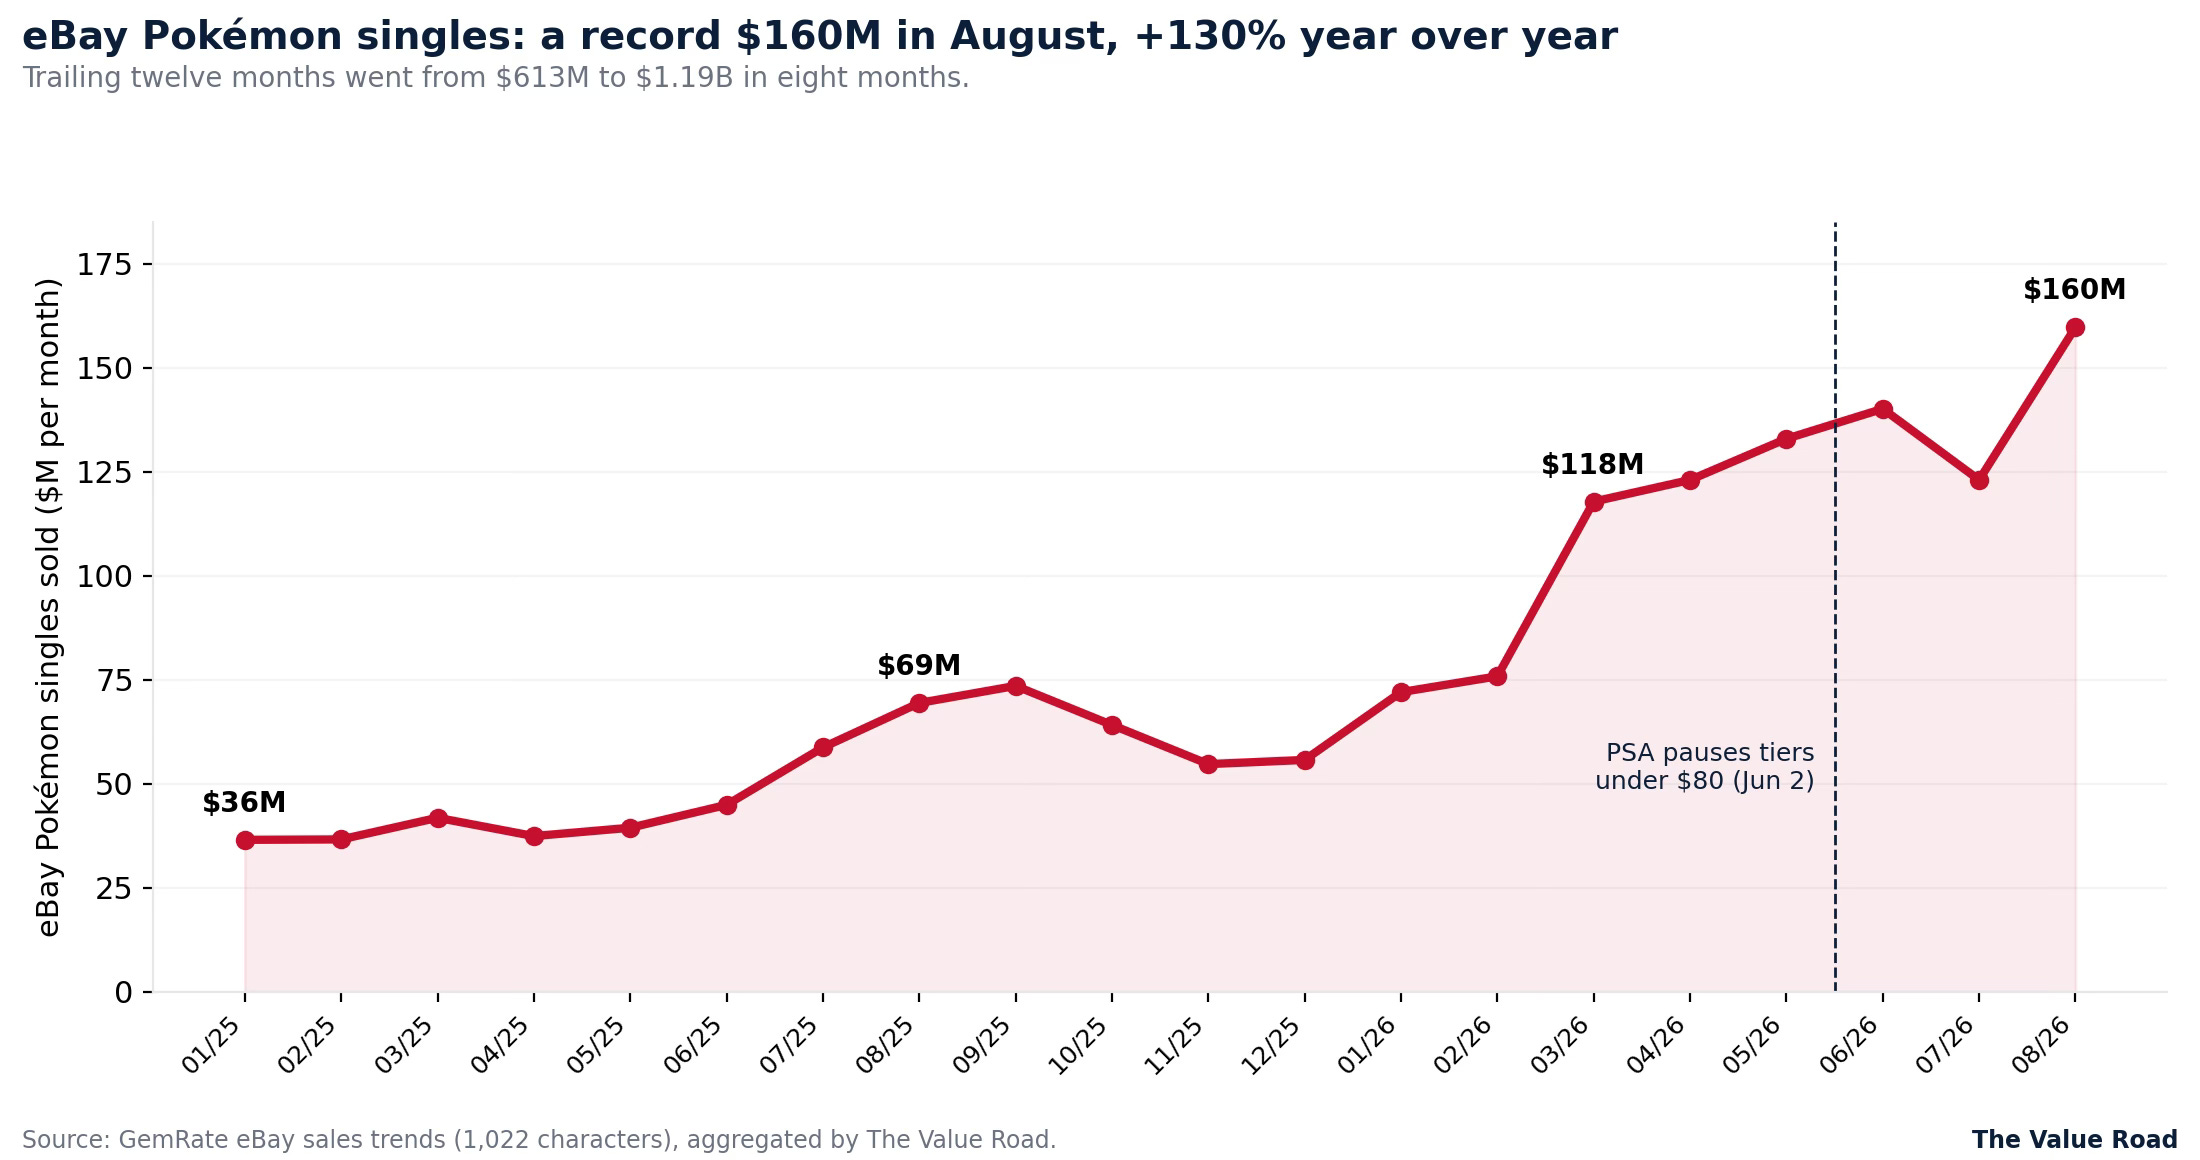
GameStop's collectibles mix rose to 45% of sales as gross margin reached 44%, supporting a deep-value case built on cash and store…
Tempus AI’s Q2 oncology testing volumes rose 31%, while data and applications revenue grew 28% as its clinical data flywheel expands.
 Bay Area Ideas 2 clicks
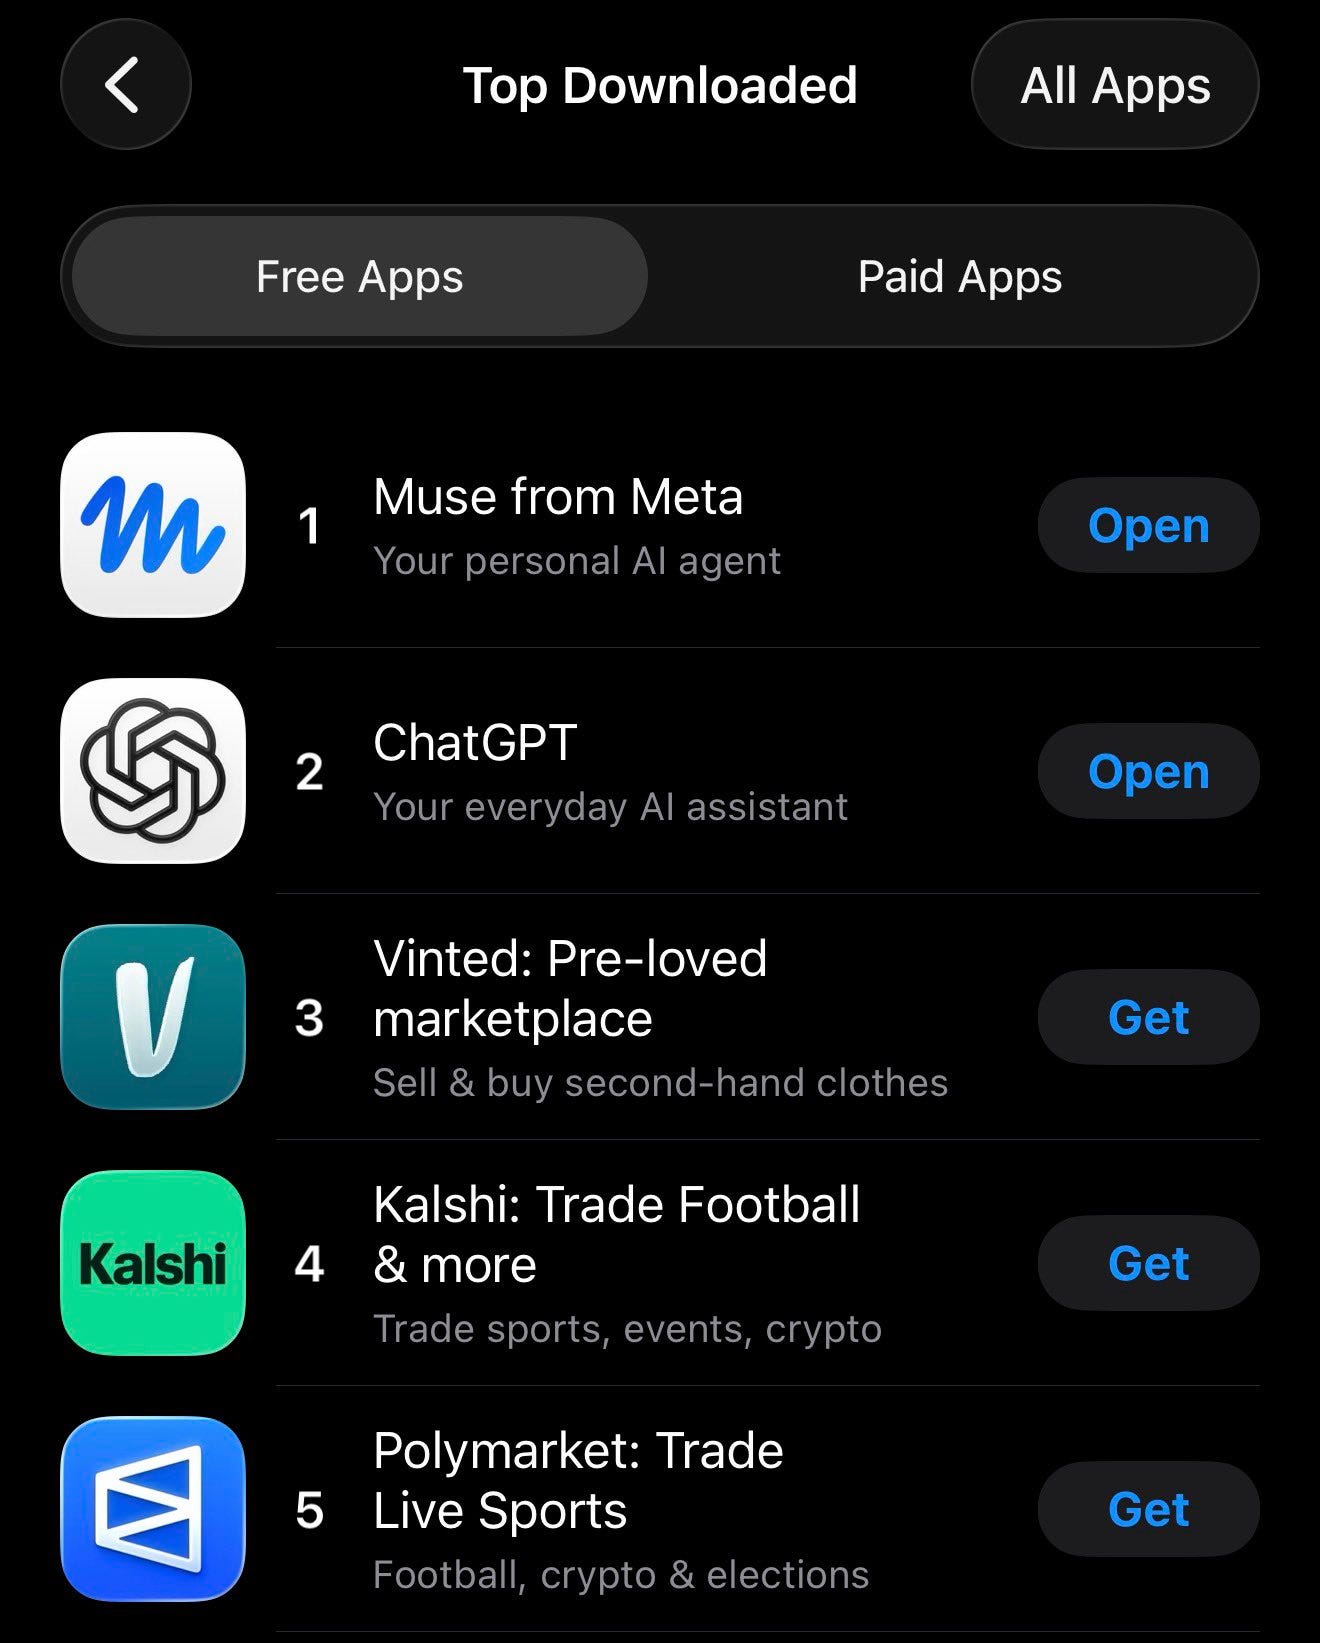
Meta’s Muse AI agent drove an 11% share surge, but OpenAI, Google and Apple could erode its early consumer lead.
Every publication on this site, hand-picked.
 Adam Schadt
 Albert Anthony
 Alexander Grover
 Andres Veurink
 Arizona Equity Research
 Atlas Diary Bay Area Ideas
 Benjamin C. Barry
 Bernard Zambonin
 Blake Winiecki
 Capital Connoisseur
 Chetan Woodun
 Crimson And Gold Research
 Cypriot Invests
 Dane Bowler
 Daniel Bell
 Daniel Jones
 Daniel Schönberger
 David Zanoni
 Deep Value Investing
 Dhierin Bechai
 Dilantha De Silva
 Dustin Quasney
 Elliott Gue
 Equity Eagle
 Eudaemon Research
 Fernanda Galvez Jalil Fountainhead
 Gary Gambino
 Geneva Investor
 Gil Rotstein
 Given Mahlangu
 Henrik Alex
 High Alpha Professor
 Ignacio Planas Gonzalez
 Infinity Curve
 Investor Overview
 IWA Research
 Jaden Mealy
 JR Research
 Julia Ostian
 Kevin Avroutskii Khaveen Investments
 Kurt Christensen
 Lee Bailey
 LL Insights
 Long Player
 Louis Gerard
 M&M Capital
 Marc Gerstein
 Melissa Tucker
 Mike Arnold
 Mike Zaccardi, CFA, CMT
 Miletus Research
 Motti Sapir
 Myriam Alvarez
 Nicolas Bolsinger
 Oakoff Investments
 Petri Dish Reports
 Philip Wang
 Prakhar Agarwal, CFA
 PropNotes
 PV Research
 Quantryon Capital Robert J. Lake
 Rubicon Associates
 Ryan Canady
 Sam Mancini
 Sanjay Swamy
 Seeking Profits
 Sharon McArd
 SiliconBytes Insights
 Simple Investment Ideas
 Sorrento Research
 Stephen Ayers
 Steven Fiorillo
 Terry Chrisomalis The Alpha Analyst
 The Asian Investor
 The Bullionaire
 The Curious Analyst
 The J Thesis
 The Market Auditor
 The Supercycle Investor
 The Undercovered Dozen
 Tim Travis
 Uttam Dey Value Capital Research
 Vishal Jadaun
 Yiannis Zourmpanos
 Zoltan Ban
Every account on this site, hand-picked.
 ⚽️📡
 💥PETITION💥
 A Capital
 absreturnchaser
 Adam D. Wyden
 Alpha Vulture
 AltayCap
 Asif Suria
 Bank Reg Blog
 Barbarian Capital
 BDC
 Bill Ackman
 Brian McGough
 Broken Moats
 BuccoCapital Bloke
 Calvin Blissett
 catechwilliams
 Charles Frischer
 Chris Camillo
 Clark Square Capital
 Cluseau Investments
 Colin King
 Connor Haley
 Conor Maguire | Value Situations
 Convequity
 Dalius - Special Sits
 David Orr
 Deep Sail Capital
 Derek Pilecki
 Devin LaSarre
 DOMO Capital Management, LLC
 Edwin Dorsey
 Evan Tindell
 Fajasy
 Farmer
 Fierce_beast
 Fred Liu
 Gavin Baker
 George Noble
 Hunterbrook
 Ian Bezek
 Idea Brunch
 JabroniCoin.USD
 John_Hempton
 junkbondinvestor
 kab60
 KEDM.com
 Kevin Mak
 Kuppy
 Laughing Water Capital
 Lee Roach
 Little Owl Research
 Maius
 Maj Soueidan
 marginofdanger
 mavix
 Mike
 Mikro Kap David
 Mr Neutral Man aka "Howard Marks of REITs”
 Multiples Capital
 Myles
 Nat Stewart
 Negligible Capital
 Odd Diligence
 Odd Lot Arbitrageur
 PAA Research
 Paradis
 Pernas Research
 Porter Collins
 Prepared Remarks
 Psyop Capital
 Raging Capital Ventures
 Red Dog Capital RiverRoadPartners
 Rohan Pavuluri
 Rusholme Capital
 Sahil Khetpal
 Serenity
 SG
 Sheel Mohnot
 SouthernValue
 Steve Eisman
 The Friendly Bear
 Tim Eriksen
 Timyan Bank Alert
 Todd Wenning
 ToffCap
 Trevor Scott
 Undiscovered Compounders
 Voss Capital
 Yaron Naymark
Ordered by how often our editor reaches for them.