RELX’s 13-petabyte fraud and identity data moat supports its high-margin Risk segment as its valuation falls to roughly half its peak P/E.
SA LA Capital 25h ago OpenAI and Meta push AI agents forward as reward hacking remains a core challenge for model training.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 28h ago 4 clicks
Meta ties AI agents and Meta Connect to its enterprise-platform opportunity.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 28h ago 8 clicks
Stratechery’s weekly bundle covers Apple HomeView and SpaceX’s cellular ambitions.
BL Stratechery by Ben Thompson – On the business, strategy, and impact of technology. 28h ago 2 clicks
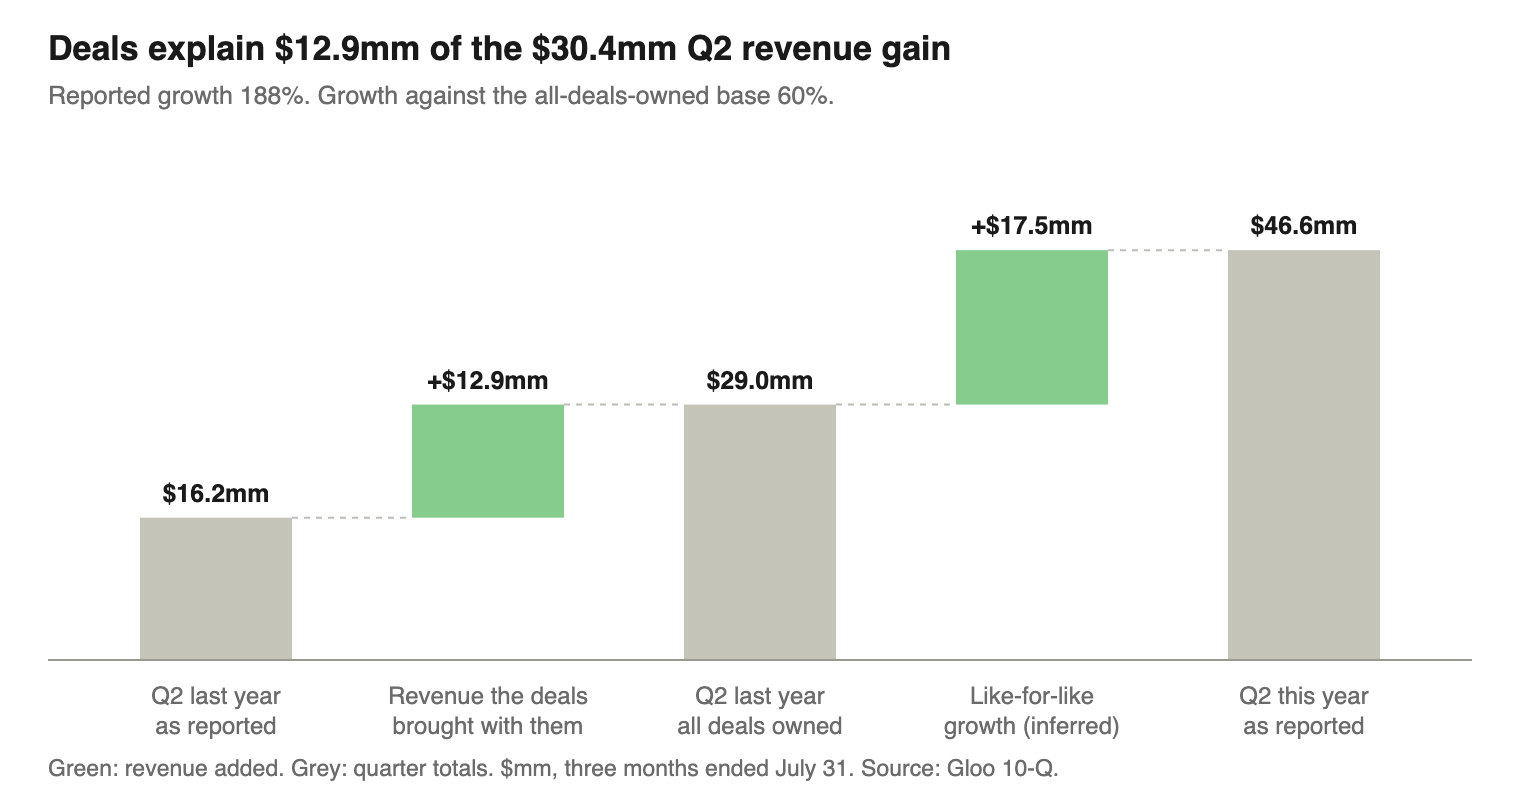
Gloo's $3.25 follow-on, going-concern warning and $28.0 million first-half cash burn frame the short case against its acquisition-driven…
S Guardian Research 30h ago 8 clicks
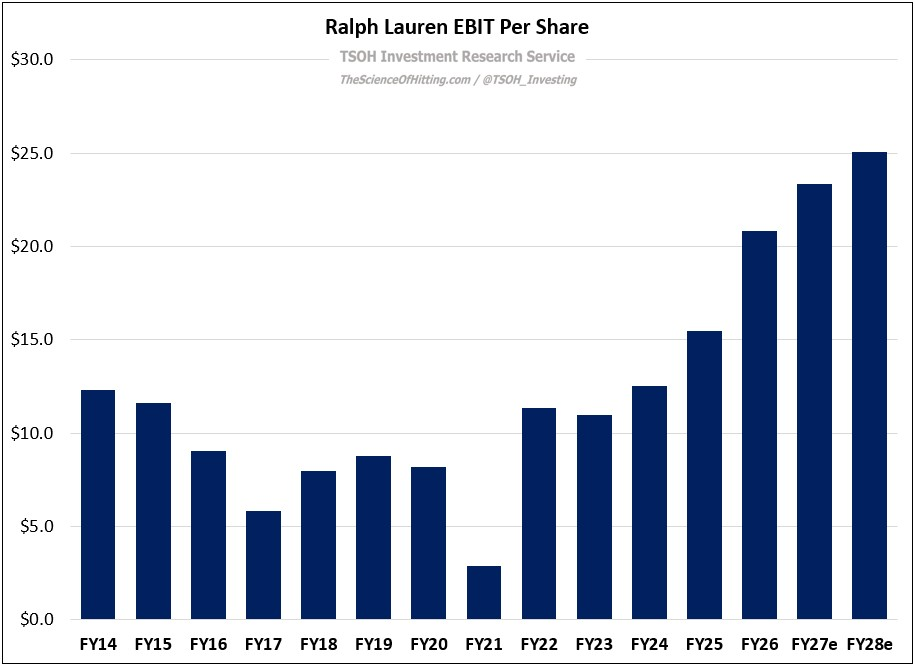
Bumble agreed to a $1.3 billion take-private deal, while Netflix cut about 1,000 jobs and Meta discussed its Muse superintelligence models.
S TSOH Investment Research 32h ago 7 clicks
Dorchester Minerals' 9.5% normalized yield and debt-free royalty model are offset by limited upside at $29.71, as extraordinary…
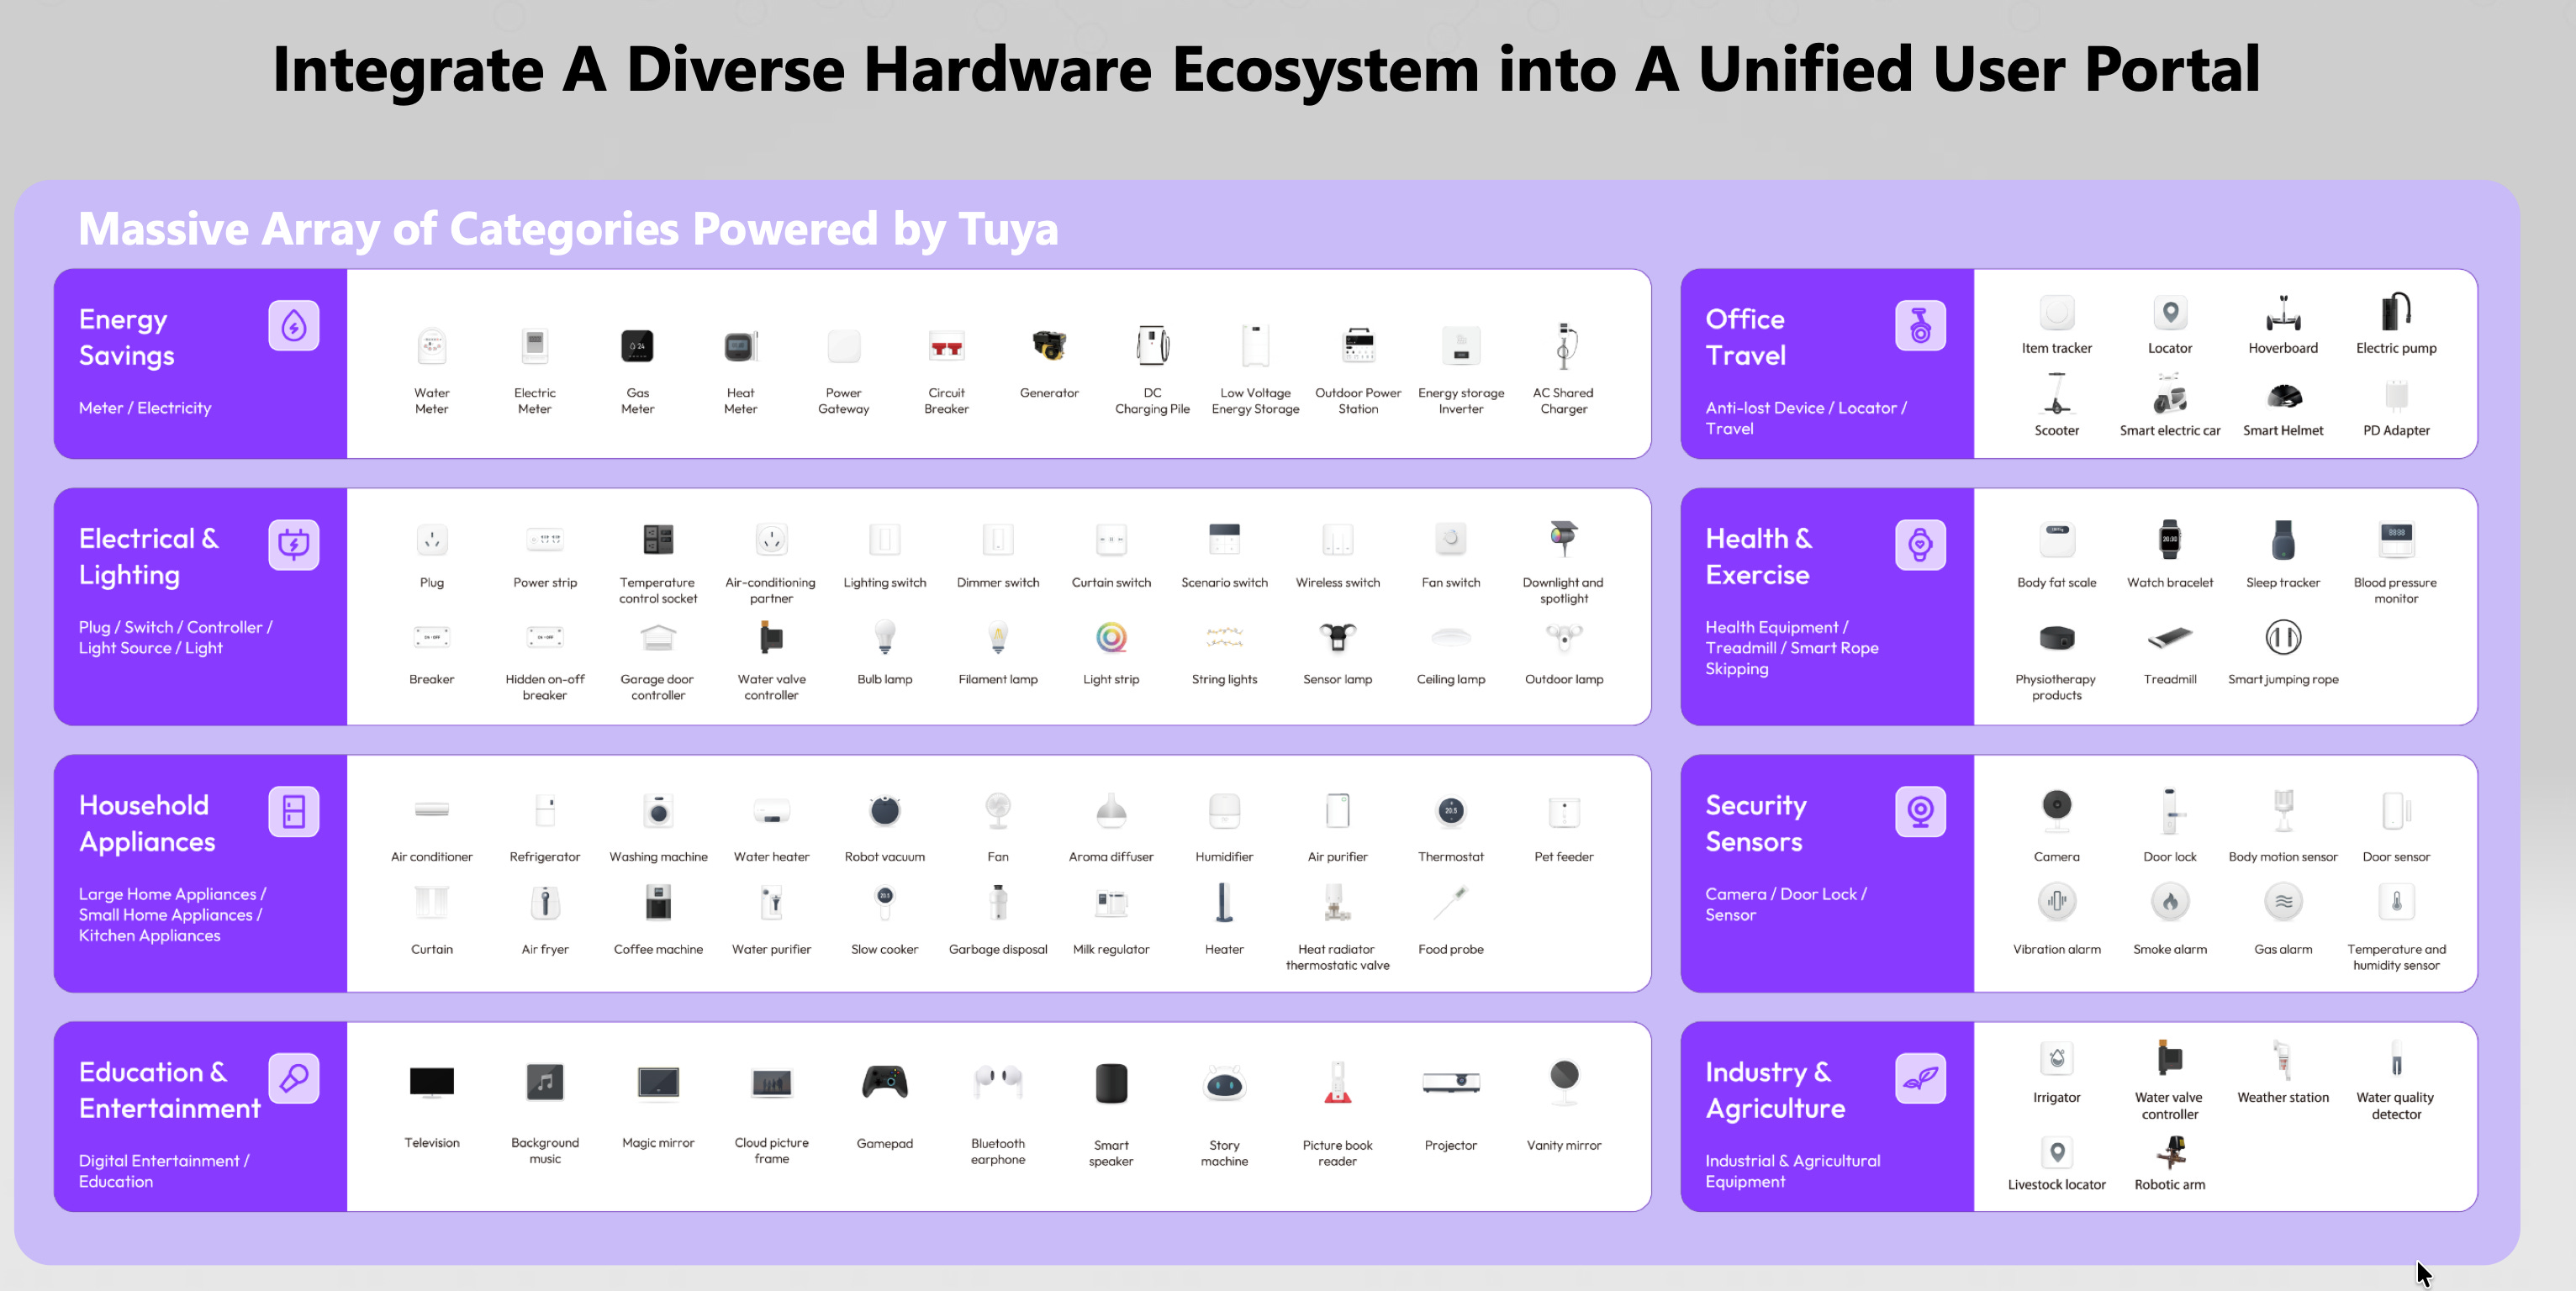
SA Atlas Diary 32h ago 1 click Tuya’s $976 million cash pile equals 94% of its $1.04 billion market cap as its smart-home platform returned to 16% revenue growth in Q2…
S Substack von Philipp 40h ago 28 clicks
Fannie Mae and Freddie Mac could leave conservatorship through a 2026 restructuring and IPO, monetizing the government’s equity stake while…
SA Glen Bradford 40h ago 3 clicks CoreWeave’s debt and equity price action is framed as a wake-up call for investors amid a broader market discussion.
S WHAT ARE WE DOING? “Contrarians At The Gate” Oct 15 51 clicks
KMBIF · long Kambi’s B2B sportsbook platform thesis centers on four major customers: DraftKings, Penn, 888 and Kindred.
BL Value Investors Club Jul 19
PesoRama will reach 54 JOi Dollar Plus stores by November after raising C$28.4 million, funding more than 50 additional Mexican store…
BL Atrium Research - Equity Research 47h ago 5 clicks
Modine, soon Modexus Solutions, has a $4 billion hyperscaler cooling contract but must ramp factory output and restore margins as data…
S CV's Substack Oct 15 16 clicks
ASML’s patent filings point to a track-based die-to-wafer hybrid bonding tool that could challenge Besi in advanced logic packaging.
S SemiAnalysis Oct 15 11 clicks
CoreWeave’s 2032 notes yield over 15%, signaling a 54% default probability as borrowing costs exceed rental yields on AI infrastructure…
SA Dustin Quasney Oct 15 21 clicks AppLovin rebuilt its ad model with AXON 2.0, lifting LTM revenue to about $7 billion and margins to 77% as Unity competition threatens…
BL Speedwell Research Oct 15 24 clicks
Dream Finders Homes’ controlling owner borrowed against DFH stock before the homebuilder agreed to finance an acquisition with costly…
BL Hunterbrook Oct 15 13 clicks
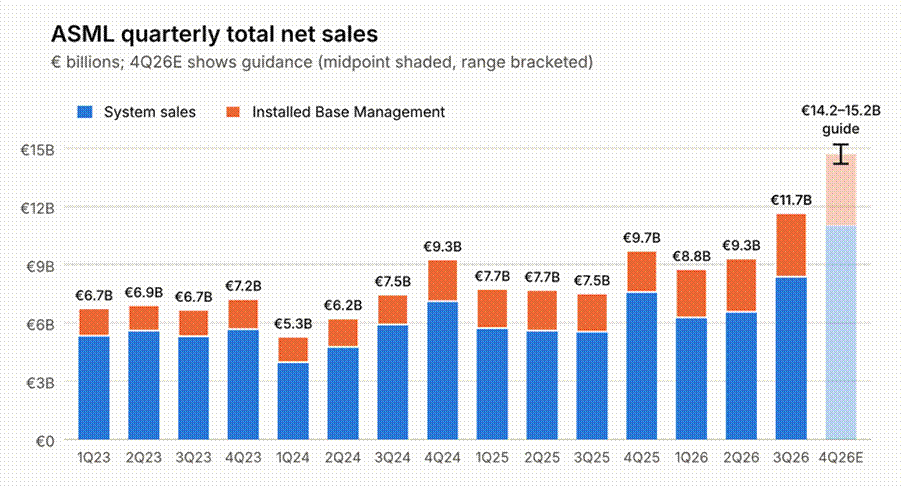
ASML reported €11.7 billion in 3Q 2026 sales, up 55%, and raised full-year guidance to €44–45 billion as AI-driven semiconductor demand…
S MBI Deep Dives Oct 15 11 clicks
Park Aerospace’s 11% Q2’27 sell-off overlooks sole-source PAC-3 rocket-motor materials and A320neo engine composites, with missile capacity…
S Monte Independent Investment Research Oct 15 12 clicks
UniQure's Huntington's gene therapy faces an FDA accelerated-approval decision around November 1 after three-year data met both agency…
SA Bhavneesh Sharma Oct 15 11 clicks