UnitedHealth fell over 10% after the proposed CRUSH rule put roughly $9 billion of annual Medicare Advantage clawbacks at risk across the…
SA Edmund Ingham 40h ago 2 clicks Palo Alto Networks posted 39% Q1 revenue growth to $3.45 billion, raised FY27 guidance and agreed a $4.5 billion all-stock acquisition of…
BL Cestrian Capital Research 40h ago 4 clicks
Knife River expects FY26 EBITDA margin to fall 138 basis points as project delays and fuel costs bite, while Sharper EDGE targets…
S Monte Independent Investment Research 41h ago 5 clicks
AMD has committed up to $161.1 billion in customer equity rights and $33.1 billion in guarantees, leases and investments, while holding…
BL Hunterbrook 41h ago 6 clicks
AMD firmware reached blacklisted IEIT Systems after U.S. restrictions, while tighter rules threaten Singapore sales and expose China-linked…
BL Hunterbrook 41h ago 5 clicks
November purchases include Public Storage preferred shares and MercadoLibre, with a focus on preferred-stock income and Latin American…
S Ian’s Insider Corner 41h ago 6 clicks
Rick Rule argues copper needs $250 billion of capital and says 30-year uranium contracts are reshaping mine financing.
YT The Monetary Matters Network 41h ago 5 clicks
AST SpaceMobile’s 79% decline improves its risk-reward case, but satellite deployment delays, rising costs and Blacklift commitments raise…
SA Infinity Curve 42h ago 6 clicks India’s 236 GWh battery target boosts local electrolyte-salt makers, while Mirion’s radiation monitors and Overwatch’s passive drone…
S Trade Ideas Flow 43h ago 5 clicks
Take-Two's GTA VI is expected to drive a long sales tail, but a DCF using analyst estimates values TTWO below its current price.
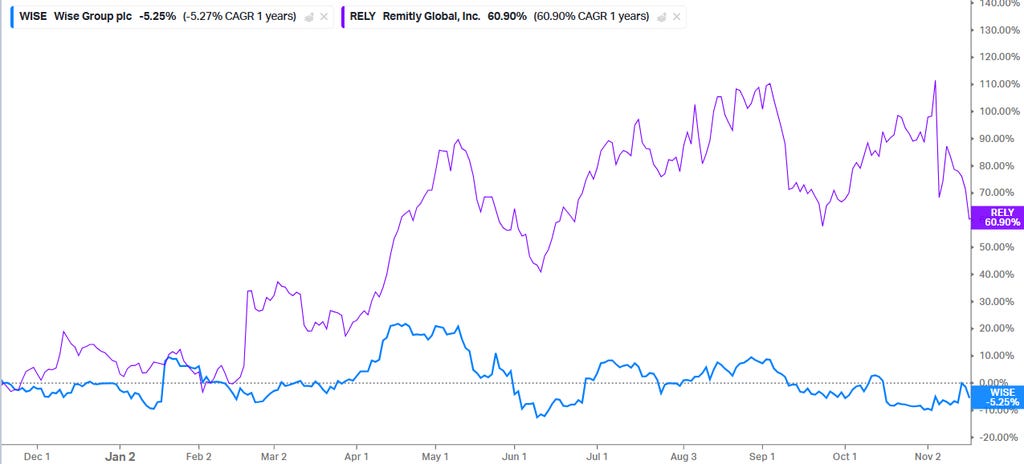
SA Gytis Zizys 43h ago 5 clicks Remitly’s Q3 revenue growth accelerated to 22% as lower transaction losses lifted margins, while recipient-facing products build a…
S scuttleblurb 43h ago 4 clicks
Intel’s data-center growth reached 78% as Xeon capacity expands, while weak PC demand, foundry losses and capital spending pressure margins…
SA Capital Minded 43h ago 2 clicks Netflix’s $20 billion 2026 content budget spreads fixed costs across 325 million members, but generative AI and content abundance threaten…
S Jimmy's Journal 44h ago 3 clicks
PLOW · long Douglas Dynamics, North America’s largest snowplow and ice-control equipment maker, holds 50-60% U.S. and 60-70% Canadian market share.
BL Value Investors Club Aug 21 1 click
Copel’s recurring EBITDA rose 35% year over year as distribution growth and margins offset weaker generation and transmission results.
SA Multiplo Invest Nov 18 Everpure and Palo Alto Networks posted their largest sales upside in years, alongside a chip-company rejuvenation.
BL The Technology Letter Nov 18 5 clicks
Sea Limited’s revenue rose 43% and adjusted EBITDA 29% in Q3 as slowing Shopee and stagnant Garena shift focus to Sea Cloud.
SA Riyado Sofian Nov 18 5 clicks Nvidia faces allegations over China and Southeast Asia sales, financial reporting and governance ahead of Q3 FY27 results.
S Kakashii's Materials Nov 18 4 clicks
GFL’s halted sale process sets a $52 to $58 per-share range, while its Secure acquisition could redirect investor attention toward…
S 310 Value’s Newsletter Nov 18 9 clicks
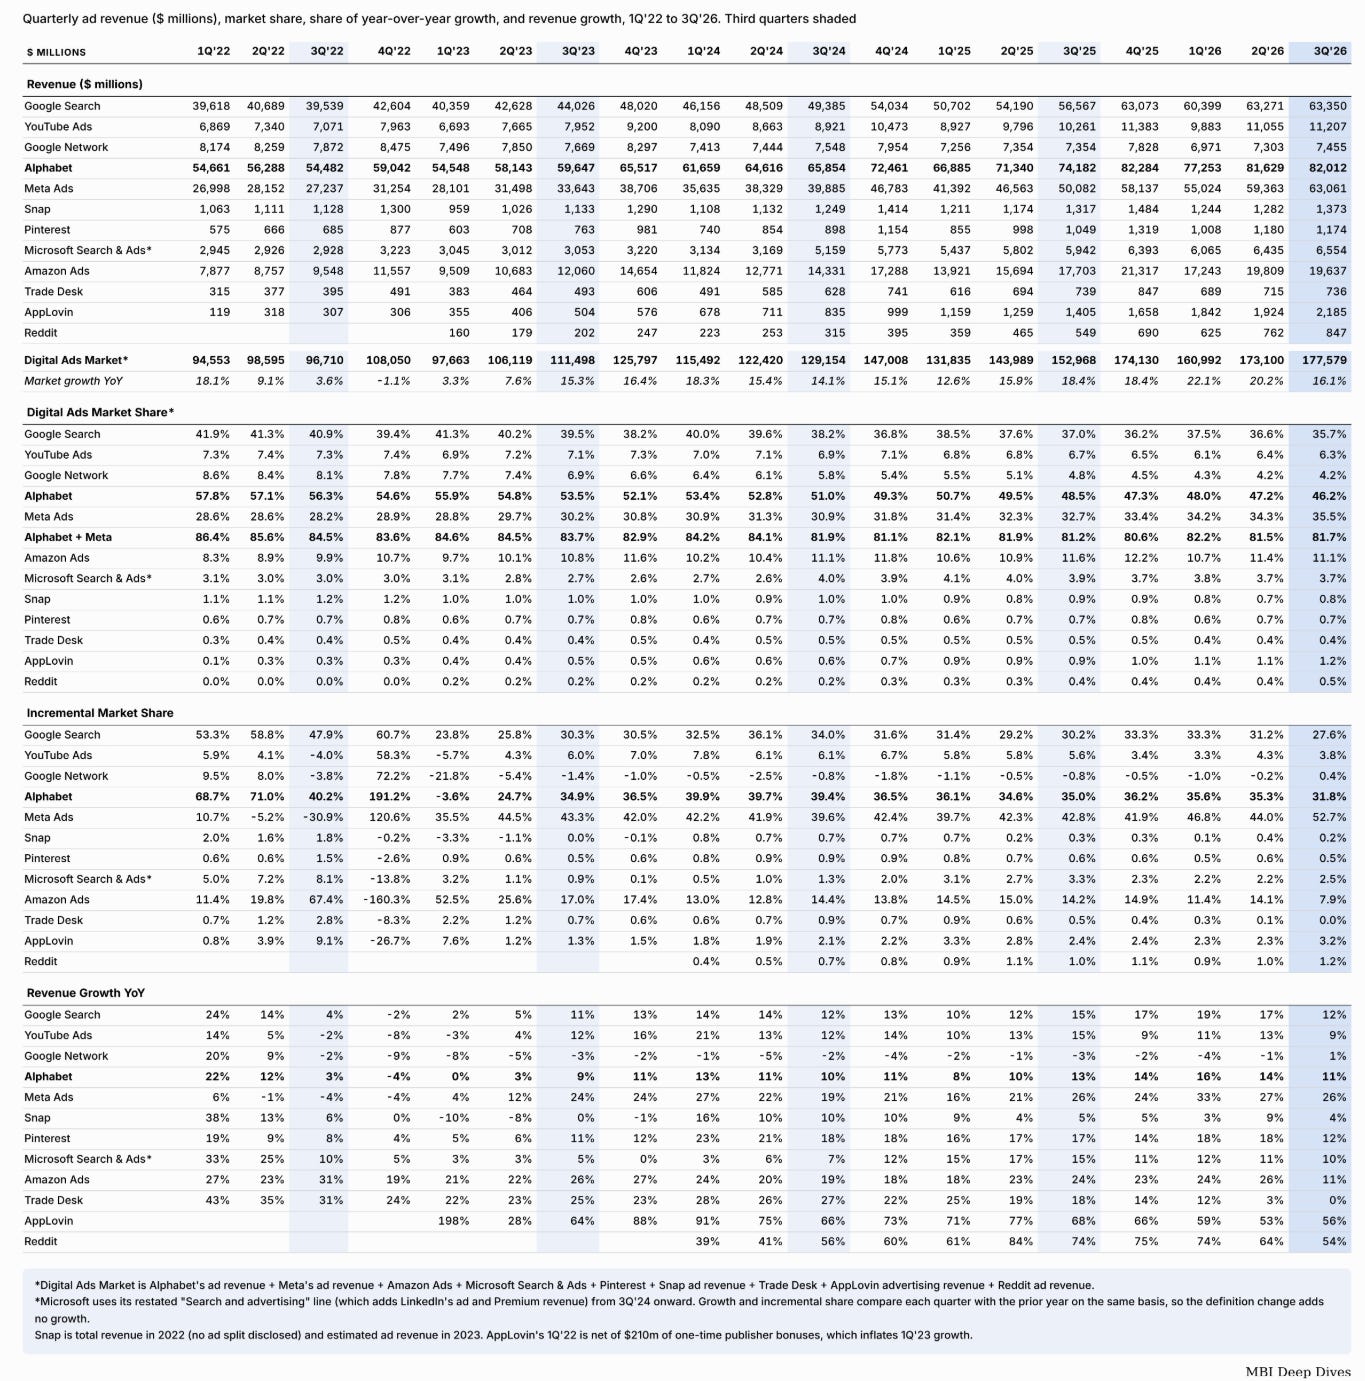
Digital advertising growth slowed to 16.1% in 3Q26 from 20.2% in 2Q26, while Meta captured 52.7% of incremental spending.
S MBI Deep Dives Nov 18 4 clicks